
AGC (TSE:5201) Could Be 12% Undervalued After Its Recent Pullback
AGC (TSE:5201) has come onto investors’ radar after recent share price swings, with the stock closing at ¥5,728. The move has drawn attention to its diversified glass, electronics, and chemicals operations.
Over the past year, AGC’s share price has swung between shorter term weakness and longer term strength, with a 90 day share price decline of 10.86% set against a year to date share price return of 9.63% and a 1 year total shareholder return of 22.83%. This points to momentum that has cooled recently after a stronger run.
Spot 74 high quality undiscovered gems that share AGC’s blend of established operations and recent price swings, so you can compare this move against other under the radar opportunities.AGC’s mix of long run shareholder gains and a recent 90 day pullback puts the focus squarely on price. Do the current numbers still compensate you for the risks from here?
Most Popular Narrative: 12% Undervalued
AGC’s most followed valuation narrative puts fair value at ¥6,516, which sits above the last close at ¥5,728 and frames the recent pullback as a pricing gap that investors need to explain with fundamentals, not just charts.
The company is poised to benefit from a medium-term demand recovery in architectural glass, supported by increasing requirements for energy-efficient renovations in Japan and a likely rebound in Asian markets, which should drive higher shipment volumes and improved pricing, positively impacting revenue and operating profit.
AGC is advancing product mix upgrades in automotive and electronics (including smart technologies and value-added glass), leveraging R&D investments and pricing policies that are already beginning to yield better margins and are expected to enhance both gross and net margins over the coming cycles.
See why 4 investors see AGC as 12% undervalued.
Result: Fair Value of ¥6,516 (UNDERVALUED)
Still, the AGC narrative depends on demand holding up in Asia and on Life Science losses not dragging on longer than analysts currently factor in.
Find out about the key risks to this AGC narrative.
Another View on AGC’s Valuation
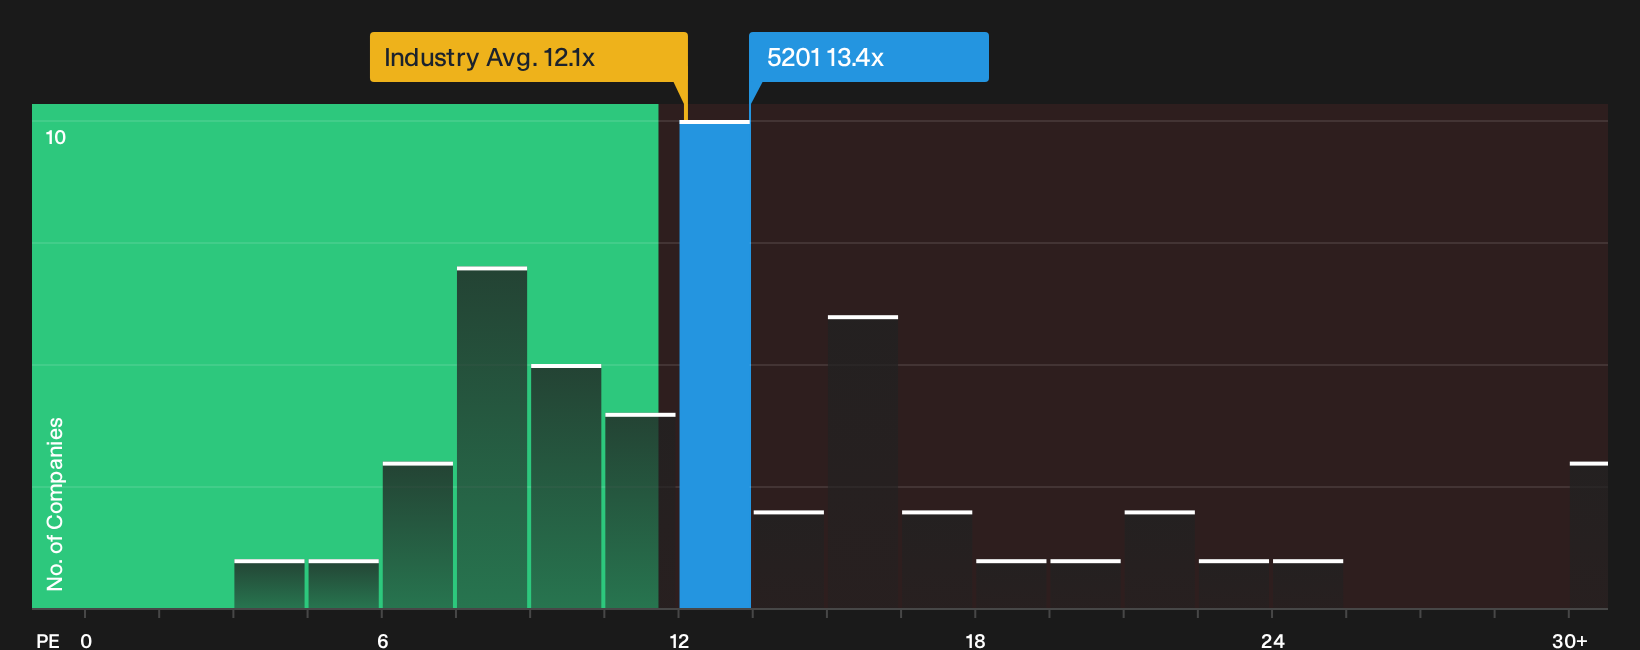
While the popular AGC story leans on fair value around ¥6,516 from analyst forecasts, the current market multiple sends a different message. The shares trade on a P/E of 13.4x, which is higher than the JP Building industry at 12.1x, yet below a fair ratio of 18.7x. That mix of slight premium to sector and discount to the fair ratio raises the question of whether the market is pricing in enough execution risk or leaving room for upside if the narrative holds.
To see how the current P/E compares in more detail and how that gap to the fair ratio could close, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on AGC’s valuation and execution risk can feel uncomfortable, which is exactly why it helps to dig into both sides quickly and stress test your own thesis. To weigh the trade off between concerns and potential upside in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more AGC-like investment ideas?
If AGC has sharpened your focus on pricing, quality, and risk, do not stop here. Broader ideas often surface where you least expect them.
- Target potential mispricing by scanning a curated set of 12 high quality undervalued stocks that combine quality fundamentals with prices the market has not fully rewarded yet.
- Prioritise resilience and smoother sleep at night by reviewing a 23 resilient stocks with low risk scores that screens for businesses with sturdier financial and risk profiles.
- Build your shortlist around balance sheet strength by working through a list of solid balance sheet and fundamentals (23 results) that filters for robust cash positions and lower leverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com