
3 Stocks That May Be Trading Below Their Estimated Value In October 2026
Over the last 7 days, the United States market has risen 1.2%, and over the past 12 months, it is up 13%, with earnings expected to grow by 18% per annum in the coming years. In this environment of growth, identifying stocks that are potentially trading below their estimated value can offer investors opportunities for capital appreciation while aligning with broader market trends.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $62.73 | $121.81 | 48.5% |
| Textron (TXT) | $73.22 | $141.94 | 48.4% |
| TD SYNNEX (SNX) | $267.46 | $521.98 | 48.8% |
| Signet Jewelers (SIG) | $105.89 | $211.23 | 49.9% |
| Pegasystems (PEGA) | $35.49 | $69.59 | 49% |
| KeyCorp (KEY) | $20.10 | $39.74 | 49.4% |
| Insteel Industries (IIIN) | $29.50 | $57.37 | 48.6% |
| EOG Resources (EOG) | $148.51 | $296.27 | 49.9% |
| Civista Bancshares (CIVB) | $26.94 | $53.30 | 49.5% |
| Addus HomeCare (ADUS) | $114.26 | $226.18 | 49.5% |
Here's a peek at a few of the choices from the screener.
Ally Financial (ALLY)
Overview: Ally Financial Inc. is a digital financial-services company offering a range of digital financial products and services in the United States and Canada, with a market cap of $11.26 billion.
Operations: The company's revenue segments include $4.85 billion from Automotive Finance Operations, $1.74 billion from Insurance operations, and $556 million from Corporate Finance Operations.
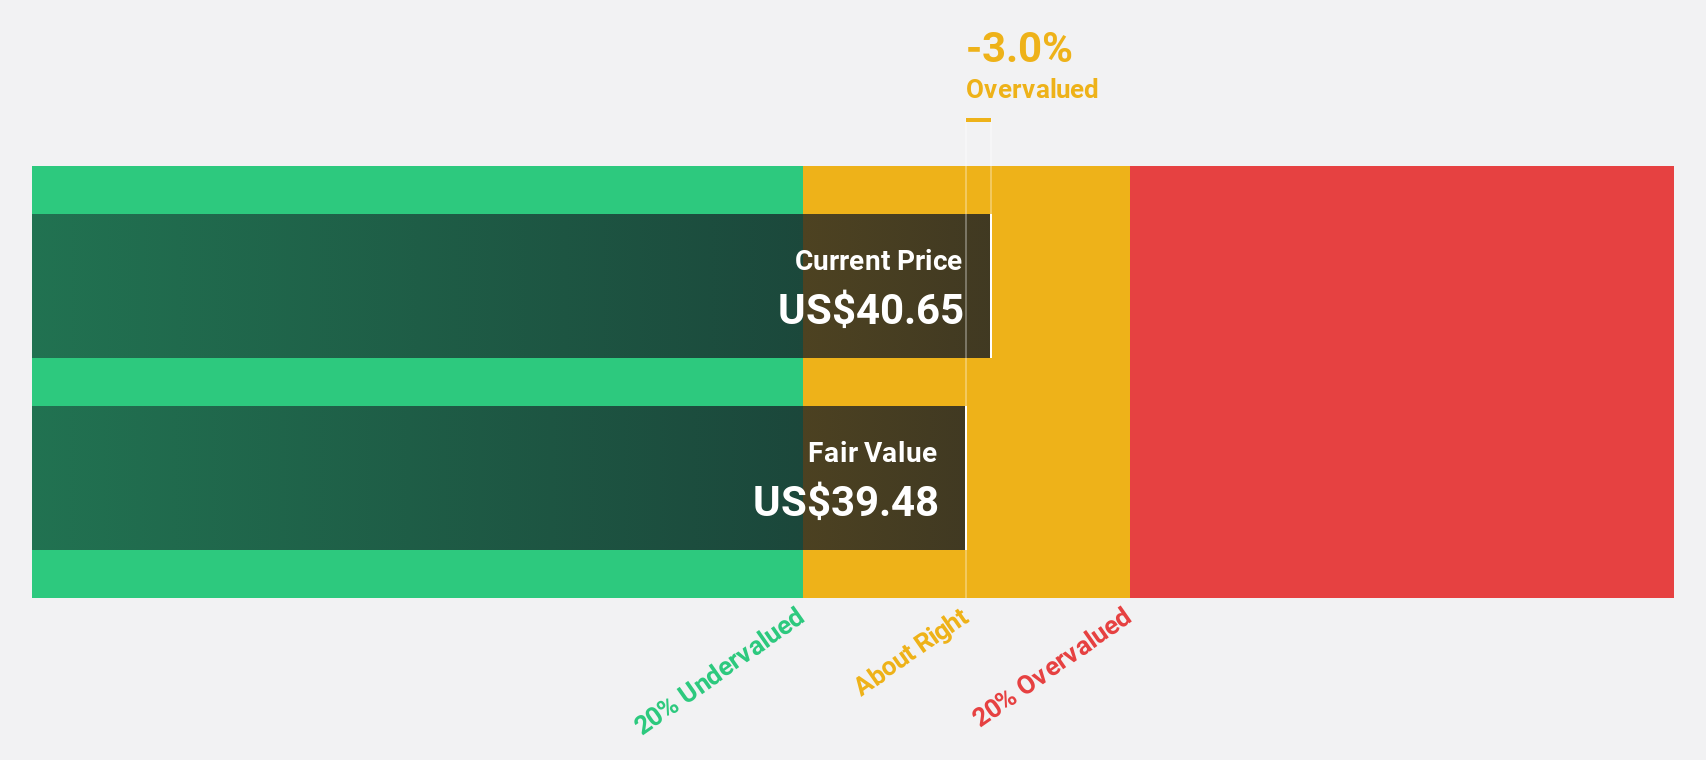
Estimated Discount To Fair Value: 20.7%
Ally Financial is trading at a significant discount to its estimated future cash flow value, with shares priced at US$37.83 compared to an estimated US$47.73. Despite slower forecasted revenue and earnings growth than the broader US market, Ally's strong cash flow position highlights potential undervaluation. Recent initiatives like the Loyally program aim to enhance customer engagement and value proposition, while strategic buybacks and stable dividends bolster investor confidence amidst evolving corporate governance practices.
- In light of our recent growth report, it seems possible that Ally Financial's financial performance will exceed current levels.
- Click here and access our complete balance sheet health report to understand the dynamics of Ally Financial.
Gates Industrial (GTES)
Overview: Gates Industrial Corporation Ltd. manufactures and sells engineered power transmission and fluid power solutions across various regions including the United States, Europe, and Asia, with a market cap of approximately $6.94 billion.
Operations: Gates Industrial's revenue is derived from two main segments: Fluid Power, contributing $1.31 billion, and Power Transmission, generating $2.19 billion.
Estimated Discount To Fair Value: 30.8%
Gates Industrial is trading at a significant discount to its estimated future cash flow value, with shares priced at US$26.74 compared to an estimated US$38.65. Despite slower forecasted revenue and earnings growth than the broader US market, Gates' strong cash flow position underscores potential undervaluation. Recent share repurchase activities worth US$144.37 million reflect strategic capital management, while voluntary deregistration may impact investor access but aligns with corporate restructuring efforts for enhanced operational focus.
- Our expertly prepared growth report on Gates Industrial implies its future financial outlook may be stronger than recent results.
- Click here to discover the nuances of Gates Industrial with our detailed financial health report.

Signet Jewelers (SIG)
Overview: Signet Jewelers Limited is a diamond jewelry retailer with operations in the United States, Canada, the United Kingdom, and the Republic of Ireland, and has a market cap of approximately $3.96 billion.
Operations: The company's revenue is primarily derived from its North America Segment at $6.38 billion and its International Segment at $422.60 million.
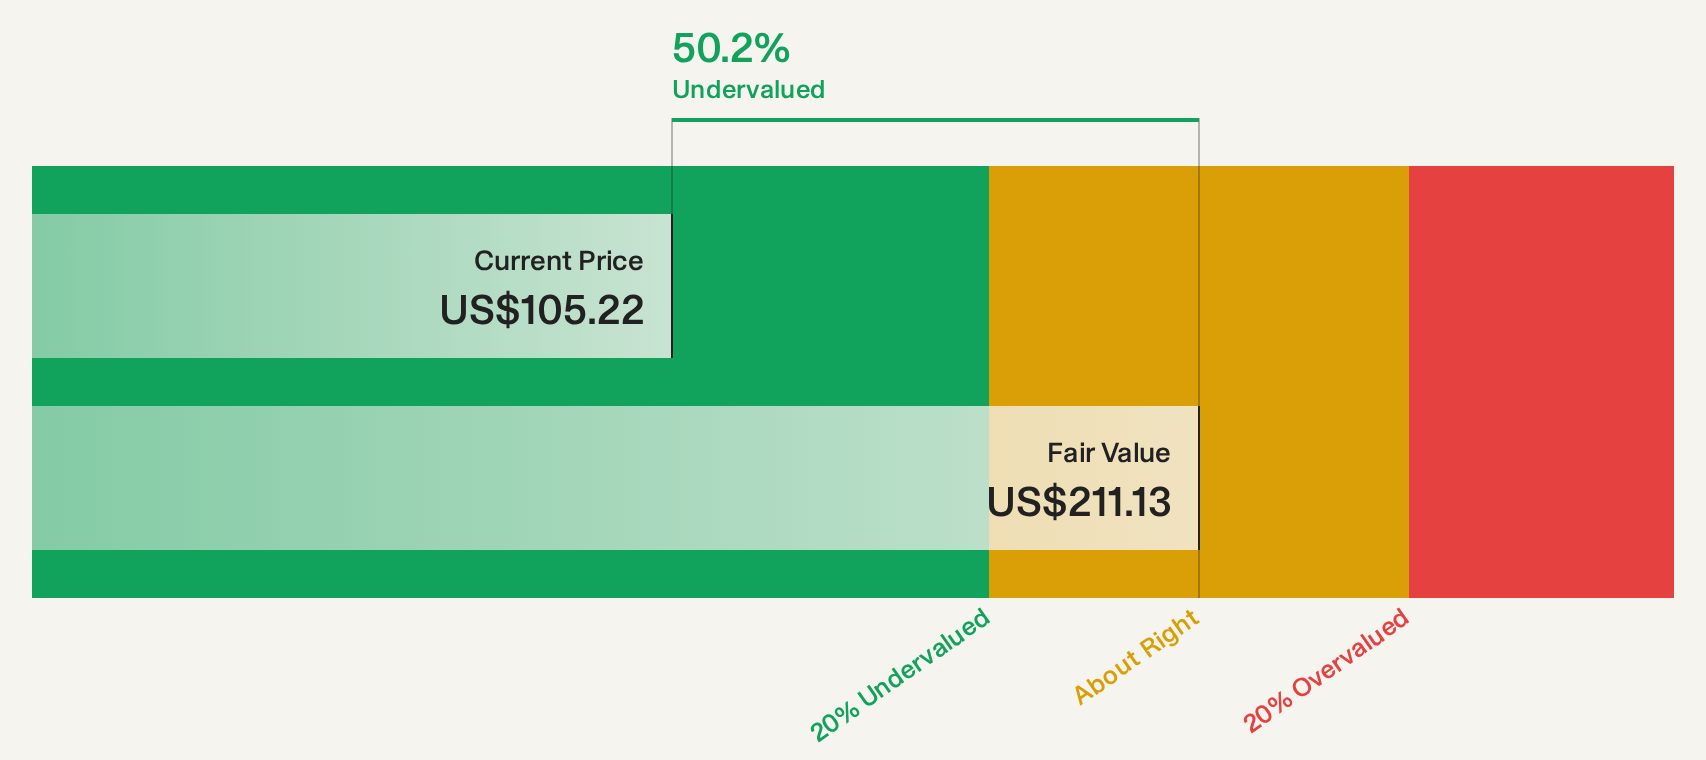
Estimated Discount To Fair Value: 49.9%
Signet Jewelers is trading at a significant discount to its estimated future cash flow value, with shares priced at US$105.89 against an estimated US$211.23. Despite slower revenue growth forecasts of 1.8% per year, earnings are expected to grow by 14.19% annually, underscoring potential undervaluation based on cash flows. Recent strategic moves include a long-term renewal with Bread Financial and ongoing share repurchases totaling US$87.2 million, reflecting robust capital management and commitment to enhancing shareholder value.
- Upon reviewing our latest growth report, Signet Jewelers' projected financial performance appears quite optimistic.
- Dive into the specifics of Signet Jewelers here with our thorough financial health report.
Key Takeaways
- Unlock more gems! Our Undervalued US Stocks Based On Cash Flows screener has unearthed 97 more companies for you to explore.Click here to unveil our expertly curated list of 100 Undervalued US Stocks Based On Cash Flows.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com