
Japan Airlines (TSE:9201) Could Be 33% Undervalued On Its Cargo Partnership Push
Japan Airlines (TSE:9201) is back in focus after launching a cargo partnership with Nippon Express. The partnership uses a Boeing 747 freighter on high-demand routes linking Los Angeles, Narita, Taipei and Singapore.
Against that backdrop, Japan Airlines’ recent share price return of 2.7% over the past 90 days and 2.6% year to date points to gradually building momentum, while the 36.1% five year total shareholder return shows how the longer term story has been more rewarding for patient holders.
Spot opportunities tied to the same AI and semiconductor cargo trend driving Japan Airlines’ partnership by scanning our handpicked 92 AI infrastructure stocks.So after this cargo push and a steady run in Japan Airlines’ share price, does the current valuation still offer an attractive balance between potential upside and the risks you are taking on?
Price-to-Earnings of 11.6x: Is it justified?
On simple earnings terms Japan Airlines looks inexpensive, with a P/E of 11.6x against a last close of ¥3,023 while peers and the wider market trade on richer levels.
The P/E ratio compares the current share price to earnings per share and gives you a quick read on how much investors are paying for each unit of profit. For an airline group with both full service and low cost operations, as well as cargo, travel and peripheral businesses, that benchmark helps frame how the market is pricing a diversified earnings stream.
Japan Airlines trades on a lower multiple than the JP market, which sits at 13.7x, and below the Asian Airlines peer group on 13.8x. The firm also screens as good value against an estimated fair P/E of 17.3x. That level may be seen as a potential reference point if sentiment around its earnings quality and growth outlook changes.
Explore the SWS fair ratio for Japan Airlines.
Result: Price-to-Earnings of 11.6x (UNDERVALUED)
Still, Japan Airlines depends heavily on travel and cargo demand, so any sharp drop in passenger volumes or freight pricing could quickly challenge the current valuation story.
Find out about the key risks to this Japan Airlines narrative.
Another view on Japan Airlines’ value
The SWS DCF model tells a very different story. On this view, Japan Airlines at ¥3,023 screens as expensive against an estimated future cash flow value of ¥1,517.27. This leans toward an overvalued verdict and raises a simple question for you: Which signal do you trust more, earnings or cash flows?
Look into how the SWS DCF model arrives at its fair value.
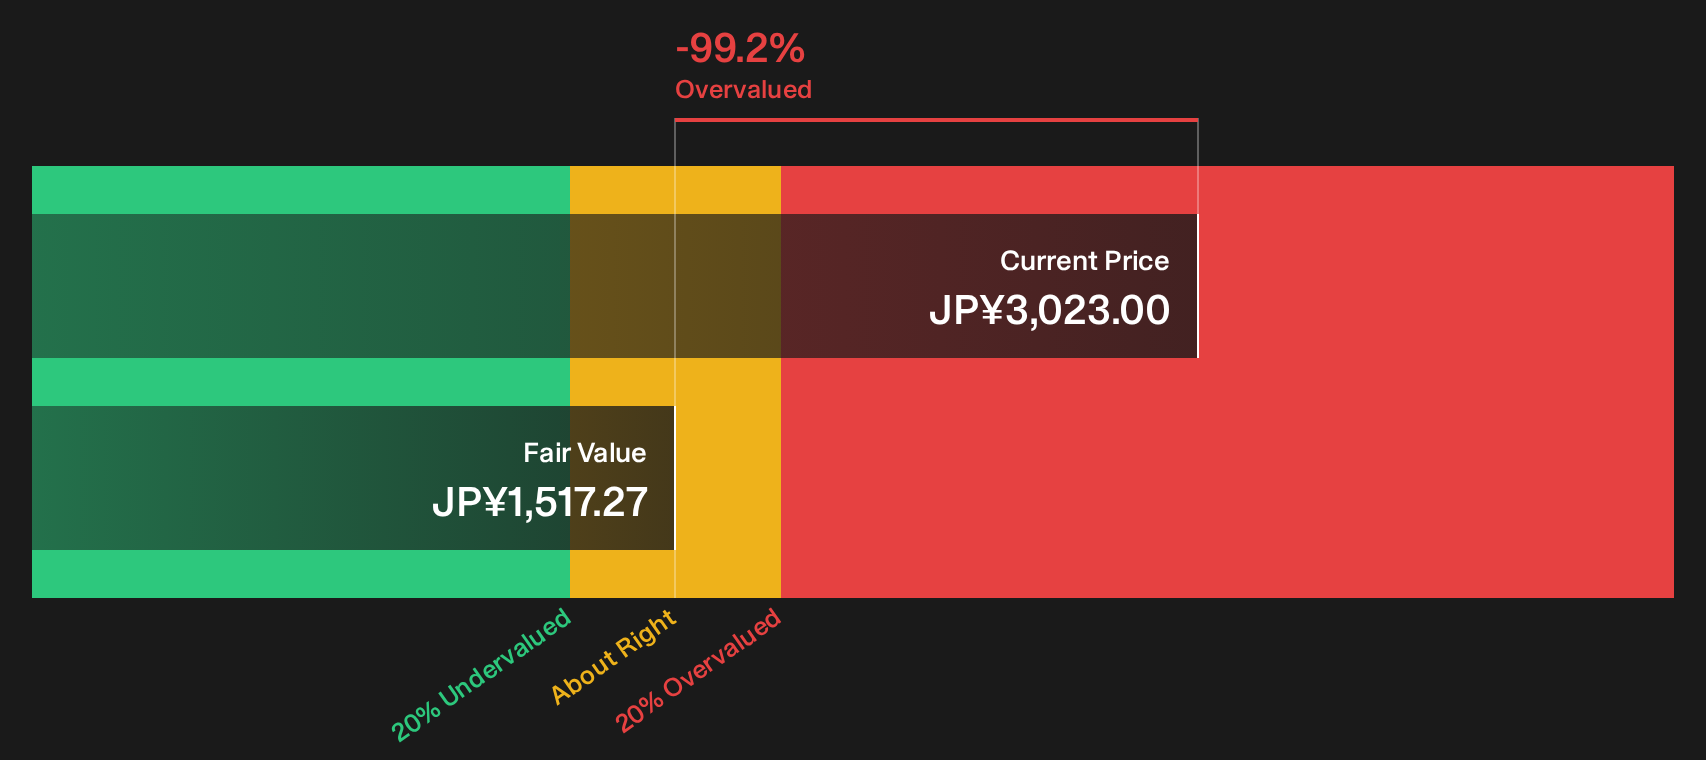
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Airlines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of signals around Japan Airlines leaves you on the fence, treat it as your cue to move fast and review the evidence yourself. The quickest way to weigh both the upside and the hazards in one place is to start with 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Japan Airlines?
If Japan Airlines has sharpened your focus on valuation, do not stop here. Cast the net wider with fresh ideas that might better suit your goals.
- Target mispriced quality by scanning our hand picked list of 12 high quality undervalued stocks that pair robust fundamentals with more modest valuations.
- Build a steadier income stream by checking companies in the 28 dividend fortresses that combine higher yields with resilient payout profiles.
- Prioritise resilience first by using the 23 resilient stocks with low risk scores to find businesses with stronger balance sheets and lower risk scores before sentiment catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com