
ImmunityBio Stock Draws Interest Ahead Of Rare Cancer Data Presentation
- ImmunityBio recently presented new immunotherapy data at the Thoracic Rare Cancer Symposium in Ottawa and remains involved in a cancer-care initiative that uses NantIQ's Eviti platform with Aetna.
- The combination of real world care delivery through the Aetna partnership and the upcoming Anktiva label decision in January 2027 highlights how ImmunityBio is working to connect clinical evidence, payer alignment and regulatory milestones into a single commercial narrative.
- We will now assess how ImmunityBio's rare cancer data presentation may influence the broader investment perspective on its immunotherapy platform.
ImmunityBio Investment Narrative Recap
To own ImmunityBio, you need to believe its immunotherapy platform can move beyond a single bladder cancer use and support a broader franchise in oncology and immune related conditions. The near term story still revolves around execution on Anktiva commercialization and real world uptake across partners and countries. The Thoracic Rare Cancer Symposium data may shape longer term pipeline perception, but it does not change that core operational focus.
The biggest short term catalyst remains the FDA decision on Anktiva label expansion expected in January 2027. That decision could influence how concentrated future revenue is in the current indication. The main operational risk is that trials outside bladder cancer or Saudi lung cancer fail to show clear clinical benefit or meet regulatory expectations. In that scenario, ImmunityBio would remain heavily reliant on a single approved setting while it carries a large net loss of US$992.4 million and negative equity.
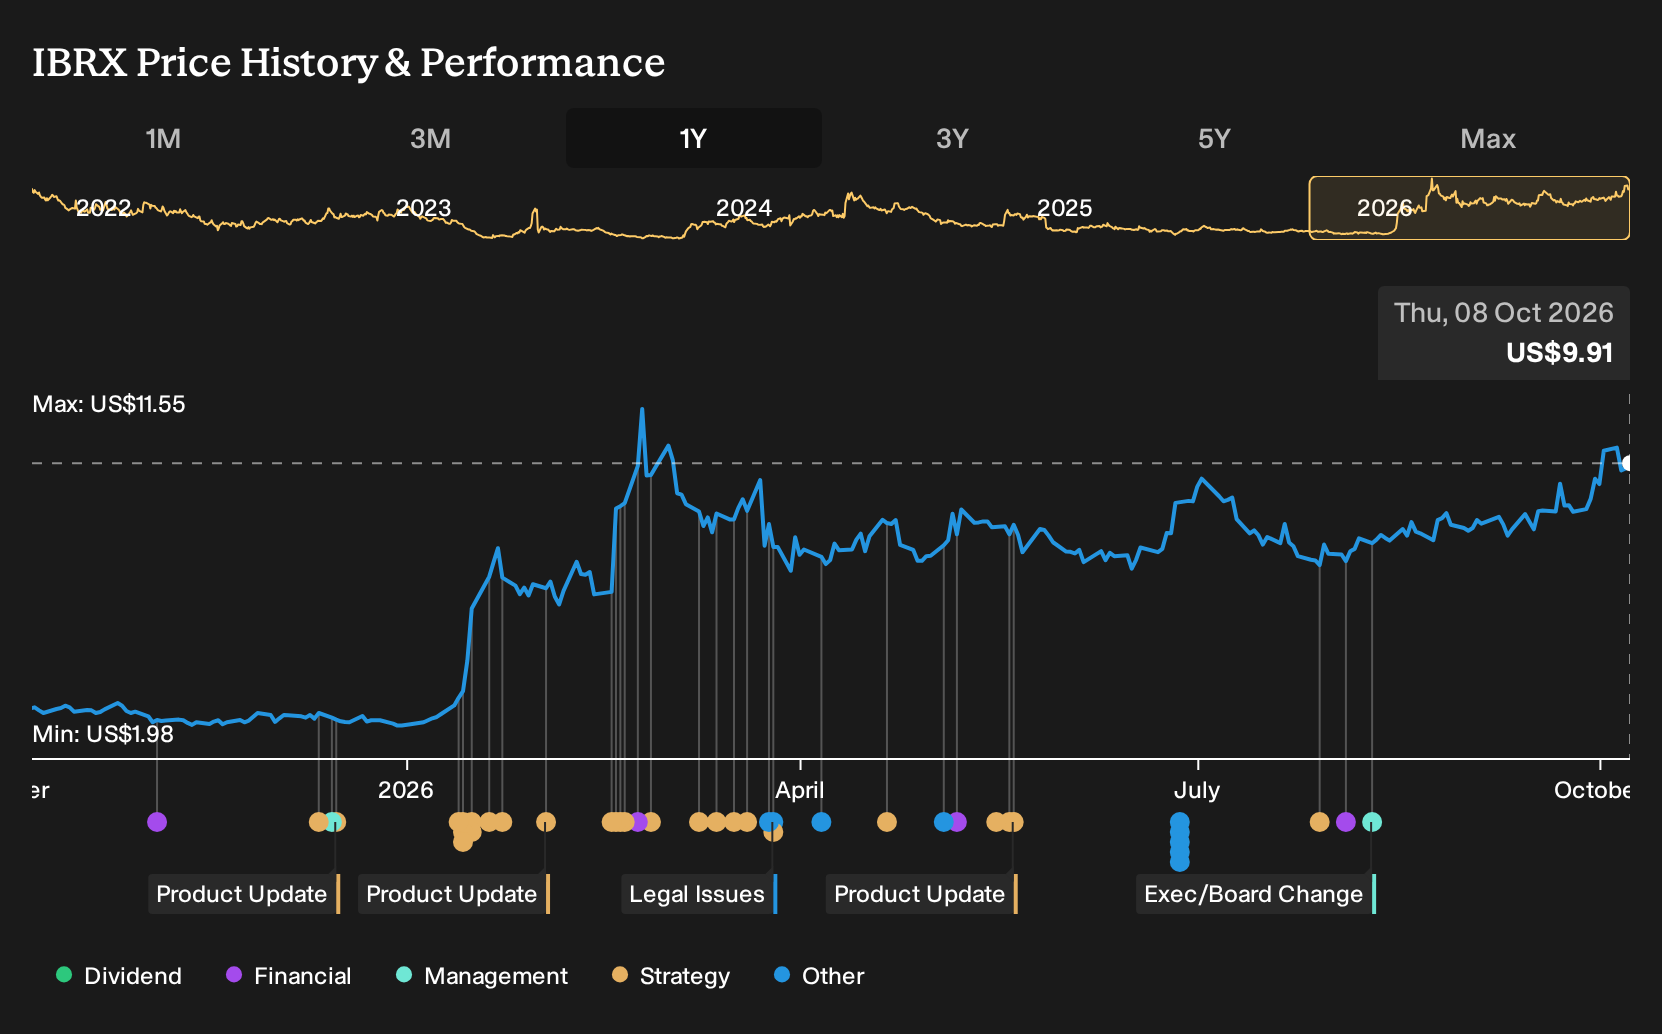
The most relevant recent development for this story is ImmunityBio presenting new immunotherapy data at the Thoracic Rare Cancer Symposium in Ottawa on 2 October 2026. Fresh data in rare thoracic cancers feeds into the broader thesis that Anktiva and related agents could serve as a backbone in multiple tumor types, particularly after checkpoint inhibitor failure, where the firm already runs combination studies.
For you as an investor, that conference appearance matters because it offers another read on execution in trials that aim to diversify future product revenue beyond non muscle invasive bladder cancer. Any signal on response durability, safety or patient selection will intersect with the upcoming Anktiva label decision, the reliance on higher risk funding sources, and the need to eventually support a much larger commercial footprint if the platform secures more approvals.
ImmunityBio's current analyst narrative points to revenues of US$1.6b and earnings of US$673.2 million by 2029, based on a very large 125.9% yearly revenue growth rate and a swing in earnings of about US$1.53b, from a loss of US$854.5 million today to the 2029 consensus figure.
Uncover why ImmunityBio's fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ImmunityBio forecasts focus on the risk that ANKTIVA remains a single product story, even with new thoracic cancer data in play. Those analysts were still penciling in about US$1.7b of revenue and US$719.9 million of earnings by 2029, yet saw only US$12.0 of value per share. You can treat this rare cancer update as a fresh reason to compare that more cautious setup with your own expectations.
Explore 4 other ImmunityBio fair value estimates, including one that suggests it could be worth just $12.00!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ImmunityBio research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ImmunityBio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ImmunityBio's overall financial health at a glance.
Looking For More Investment Ideas Beyond ImmunityBio?
If ImmunityBio has sharpened your interest in immunotherapy and higher risk, higher reward setups, it can help to compare it with other businesses filtered by clear, quantitative rules. The Simply Wall St Screener lets you quickly narrow the universe of stocks to a shorter list that matches the kind of balance sheet strength, income profile, or risk level you want to focus on next.
- For investors who want sturdier foundations, start with companies that show resilient financials and steadier balance sheets by reviewing our 31 resilient stocks with low risk scores.
- If you care most about dependable income, scan for businesses that combine higher yields with an emphasis on stability through the 8 dividend fortresses.
- For those hunting for underappreciated quality, widen your watchlist with the 20 high quality undiscovered gems that couple solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com