
Leadership Expansion Might Change The Case For Investing In Warner Music Group (WMG)
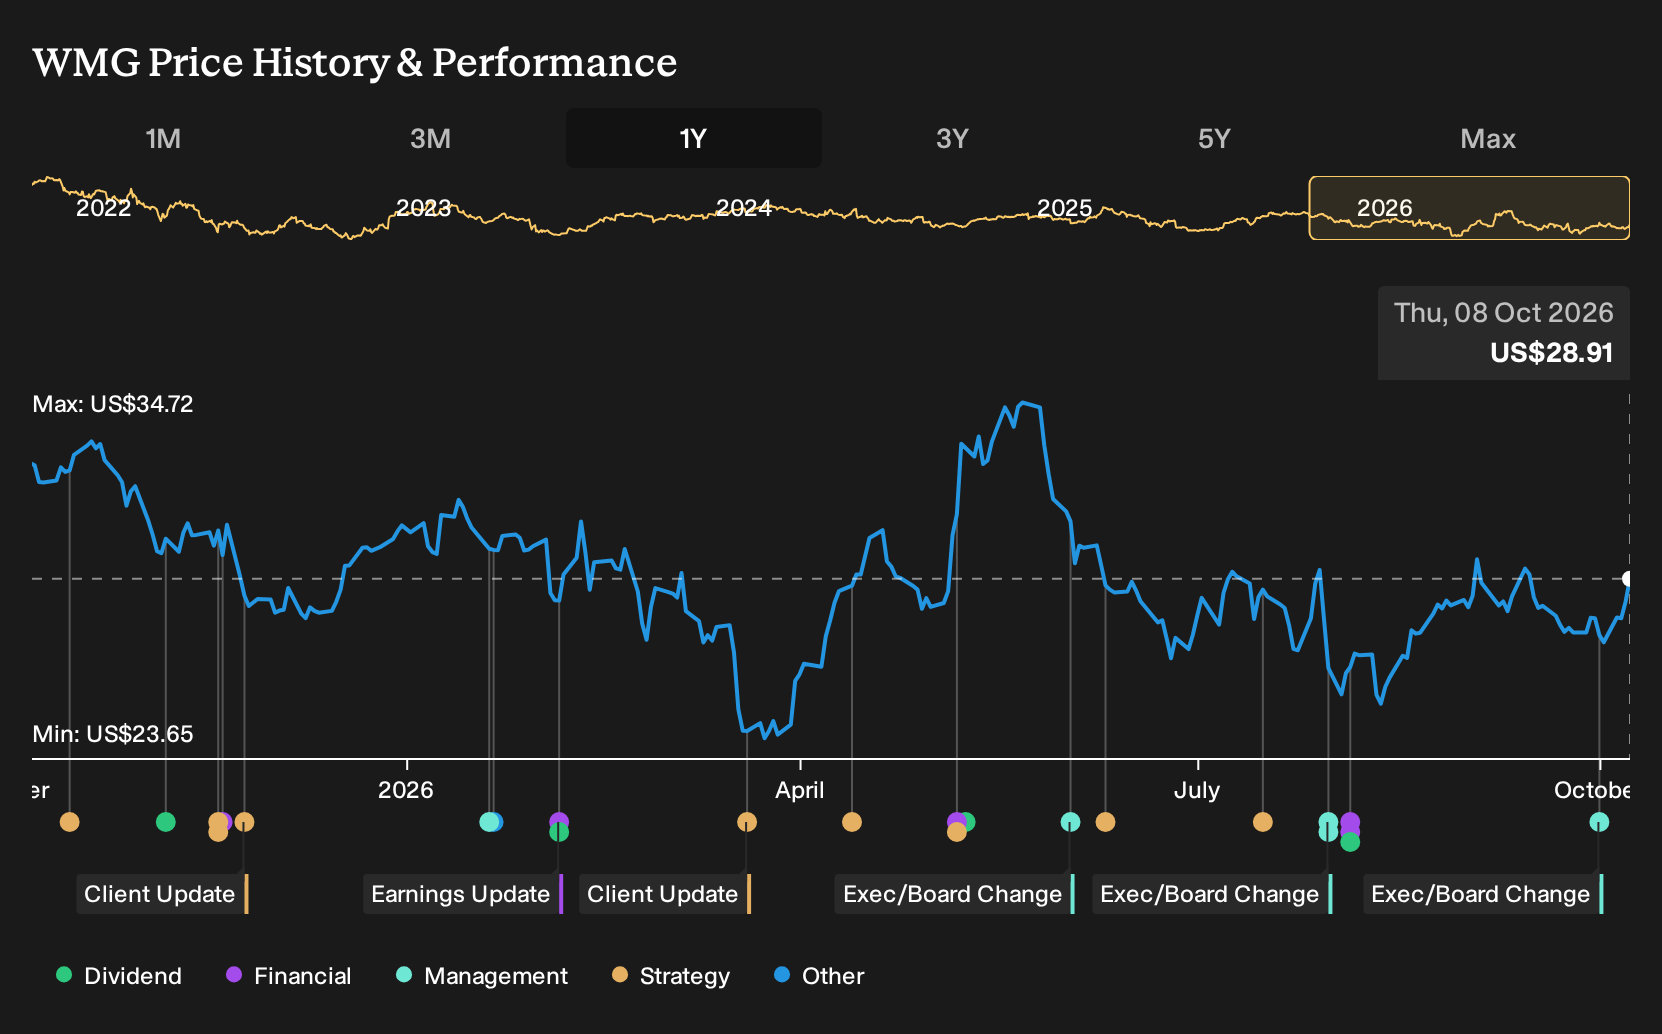
- Warner Music Group has reshaped its international organisation by promoting Ahmed Nureni to Managing Director MENA, hiring Ahmad Alghawanmeh as General Manager MENA, and appointing Nici Ochmann as Head of Culture & Creator Marketing for Central Europe, a role she assumed in October 2026 after a decade at Adidas.
- The hires concentrate operational firepower in two growth-oriented areas for Warner Music Group: creator-led marketing in GSA, and regional leadership in MENA. Together, these moves affect how efficiently the business can develop artists, structure partnerships, and scale catalog usage across streaming and social platforms.
- We will now look at how Warner Music Group's expanded MENA leadership and creator marketing focus could influence the broader investment narrative.
Scan how Warner Music Group’s creator push in GSA and leadership build-out in MENA compares with other content and IP players by reviewing our curated 20 high quality undiscovered gems.
Warner Music Group Investment Narrative Recap
For Warner Music Group, the long term belief is that streaming, catalog monetization and new digital formats can support sustainable earnings, while cost programs and AI tools protect margins. The short term story still hinges on execution of cost savings and how quickly earnings quality stabilizes after the recent one off loss of US$262 million.
The MENA build out and creator focused hire in Central Europe look more like targeted execution choices than a major shift in risk profile. They may support streaming and social performance over time, but they do not change the near term swing factors of debt coverage, dividend sustainability and progress on the multi year restructuring.
Ochmann’s appointment as Head of Culture & Creator Marketing in Central Europe lines up most closely with the digital monetization catalyst. The role focuses on creator channels and cross industry partnerships in GSA, which directly connects to Warner Music Group’s efforts to deepen superfan style engagement, improve catalog usage and push higher value streams on social and subscription platforms.
This matters most where the story already leans on margin improvement and better returns on past catalog spending. Strong execution in creator marketing could help support the thesis that earnings can grow faster than revenue. Analysts currently model 21.4% profit growth versus 5.4% top line growth, while still leaving legal and AI licensing disputes as a separate operational risk to track.
How Warner Music Group’s Targets Line Up With Analyst Models
Warner Music Group’s new MENA leadership and creator marketing push sit on top of a fairly clear analyst model for the next few years. The current framework still starts with streaming scale, margin work and catalog returns, then layers in AI tools and regional expansion as potential incremental supports to that story.
Analysts are building their forecasts on revenue rising by 5.4% a year over the next three years, profit margins lifting from 9.1% today to 14.9% and earnings moving from US$665.0 million now to US$1.3b by 2029. That step up in profitability underpins a consensus P/E of 20.7x on the 2029 earnings, slightly above the 20.5x multiple cited for the wider US Entertainment sector.
Within that framework, the creator push in GSA and the leadership expansion in MENA look like attempts to support the existing assumptions rather than rewrite them. If these hires help Warner Music Group squeeze more value from catalog, lock in better economics on partnerships and widen its monetization across social platforms, they feed directly into the margin and earnings path analysts already expect.
The share count is modeled to rise only modestly, at about 0.14% a year over three years. This means most of the heavy lifting in those forecasts comes from margin expansion and top line growth instead of dilution. With that context, investors can treat the new appointments as execution levers inside a pre set earnings and valuation framework that already bakes in cost savings targets, AI plans and catalog deployment.
Warner Music Group’s narrative projects US$8.6b revenue and US$1.3b earnings by 2029. This builds on 5.4% yearly revenue growth and an earnings increase of about US$635 million from current earnings of US$665.0 million.
Discover how Warner Music Group's fair value indicates a 31% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate view focuses on earnings risk if Warner Music Group’s AI and creator deals deliver less value than hoped. The most bearish analysts were only penciling in about US$8.7b revenue and US$1.2b earnings by 2029 before this news. That is a more cautious story. Use this appointment as a prompt to compare those assumptions and explore several different analyst viewpoints.
Explore 2 other Warner Music Group fair value estimates, including one that suggests it could be worth just $37.81!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Warner Music Group research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Warner Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Warner Music Group's overall financial health at a glance.
Looking for more Warner Music Group style investment ideas?
If the Warner Music Group story has sharpened your thinking about earnings quality, leverage and long term cash generation, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who want income that aims to be both high and better supported by fundamentals, start with a shortlist of 8 dividend fortresses that may warrant a closer look.
- If capital preservation sits high on your priority list, focus on resilience first and returns second by reviewing a curated group of 31 resilient stocks with low risk scores that clear strict risk filters.
- When the goal is to back financially sound businesses rather than chase hype, concentrate on balance sheet strength and cash flow quality through our targeted list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com