
Bilibili (BILI), What Is Behind The Fresh Attention?
Fresh equity overhang from new ESOP shelf
Bilibili (NasdaqGS:BILI) has filed a new shelf registration for American Depositary Shares, covering up to 13,500,000 ADS worth about US$199.53 million, in connection with an employee share ownership plan related offering.
Bilibili’s latest share price of US$14.85 comes after a small pullback over the past week and a steeper slide, with the 30 day share price return down 8.33% and the year to date share price return down 43.69%. The 3 year total shareholder return of 6.30% contrasts sharply with a 49.40% decline over the past year, suggesting longer term holders have seen mixed momentum that may frame how investors read this new ESOP related shelf registration and any future equity issuance risk.
Scan how Bilibili compares to other fast-moving media and tech platforms by running your eye over our curated list of 20 high quality undiscovered gems that may be flying under most investors' radar.
Bilibili now trades at a sharp discount to both analyst targets and intrinsic value estimates, so the real puzzle is where fair value actually clusters along that gap.
Most Popular Narrative: 44% Undervalued
Bilibili’s most followed narrative pegs fair value at about $26.42. This is well above the last close of $14.85 and frames today’s price as heavily discounted against those long range cash flow assumptions.
The expansion and monetization of Bilibili's creator ecosystem is creating new revenue streams through value-added services (memberships, fan charging, e-commerce), tapping into the rising demand for user-generated content and the growth of the creator economy; this supports higher ARPU and margin improvement.
See why 26 investors see Bilibili as 44% undervalued.
Result: Fair Value of $26.42 (UNDERVALUED)
Still, that story can break if Bilibili’s China heavy, Gen Z focused audience plateaus, or if tighter online content rules bite into creator activity and revenue.
Find out about the key risks to this Bilibili narrative.
Another Look At Bilibili’s Valuation
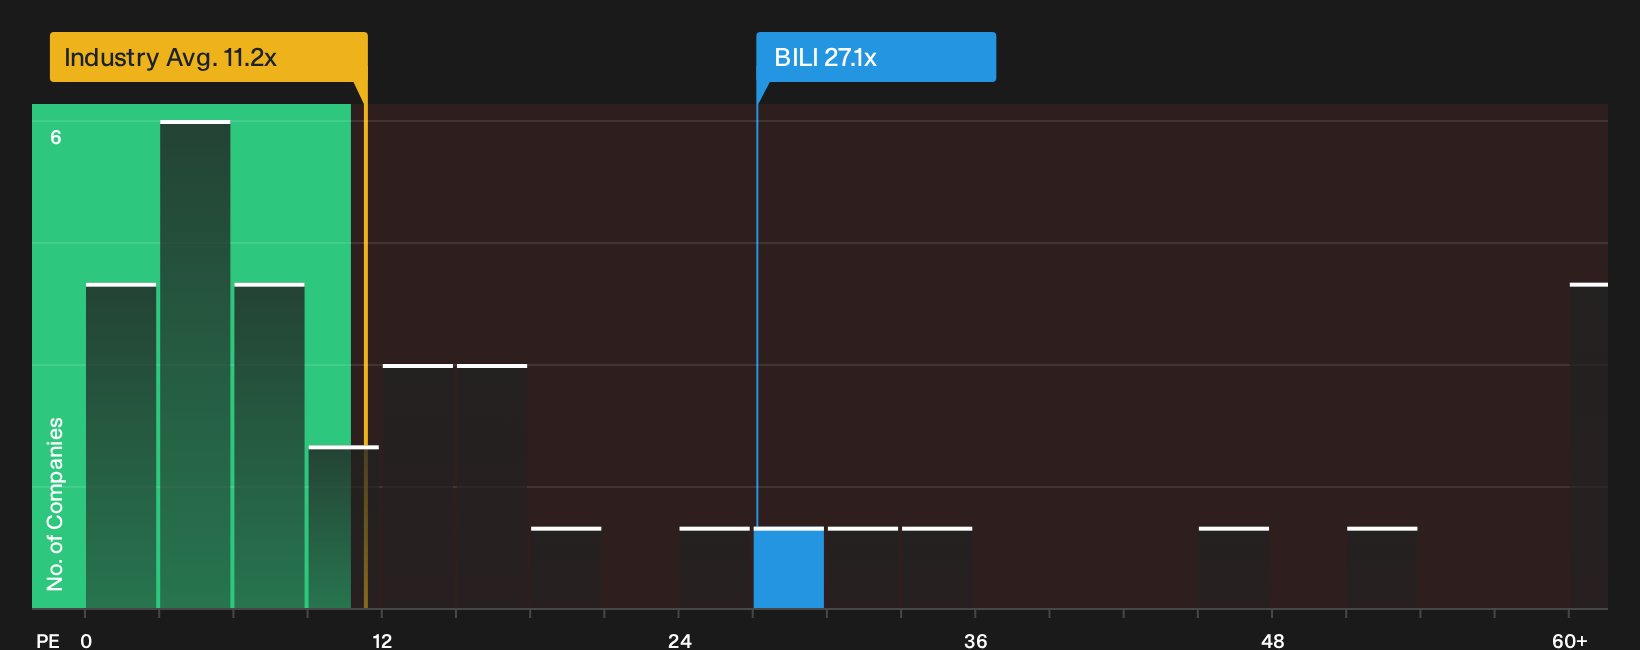
The earlier narrative leans heavily on discounted cash flows and analyst targets that frame Bilibili as heavily undervalued. A simple check on the current P/E ratio tells a very different story. At about 27.1x earnings versus a fair ratio of 24.5x, the stock is priced richer than that regression based anchor.
That premium also runs against both the US Interactive Media and Services industry at 11.2x and a peer average of 26.1x. For anyone weighing new capital, the question is whether the extra multiple reflects genuine quality or simply reduces the margin of safety.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this breakdown leans cautious, so move quickly. Review the underlying metrics yourself and judge whether the optimism around 3 key rewards really stacks up.
Looking for more Bilibili sized opportunities?
If Bilibili has sharpened your focus on price and quality, do not stop here. Cast the net wider and you could spot the next outlier earlier.
- Hunt for quality at a discount by scanning our universe of 27 high quality undervalued stocks that pair solid fundamentals with attractive pricing.
- Prioritise resilience and capital preservation by reviewing a curated 31 resilient stocks with low risk scores that screens for sturdier business profiles.
- Target stronger balance sheets by zeroing in on our list of solid balance sheet and fundamentals (25 results) and stress test how companies might handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com