
Pebblebrook Hotel Trust (PEB) Stock May Be 11% Undervalued On Cash Flow
Pebblebrook Hotel Trust has logged a strong share price run in the past year, which naturally raises the question of whether the current valuation lines up with the cash the business can produce. With the stock now far above where it traded a year ago, the key issue is how that move stacks up against the intrinsic value suggested by its cash flows.
- The share price has returned 80.9% over the past year, putting real pressure on the question of whether recent buyers are paying a fair amount for Pebblebrook Hotel Trust based on the cash it can generate.
- Pebblebrook relies on its hotel portfolio to turn operating performance into cash, so factors like occupancy, room rates and capital spending plans can all affect how comfortably its current price is backed by future cash flows.
- What if you looked at Pebblebrook Hotel Trust through its sales instead? See what Pebblebrook Hotel Trust's 1.4x P/S says about the price.
The issue now is whether Pebblebrook Hotel Trust's recent share price level is adequately supported by the intrinsic value suggested by its cash flows.
To see how Pebblebrook Hotel Trust's cash flow story compares with other opportunities, line it up against companies in the 27 high quality undervalued stocks.
Does Pebblebrook Hotel Trust Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach here uses Pebblebrook Hotel Trust's adjusted funds from operations as a proxy for what can ultimately flow to equity holders. The latest twelve-month free cash flow comes in at about $187.4 million, and the model then assumes that cash generation eases back before growing at a relatively steady pace rather than surging or collapsing.
Projected annual free cash flows over the next decade mostly cluster in the $150 million to just under $200 million range in today's money. This points to a mature hotel portfolio where value is driven less by rapid expansion and more by how consistently those properties can generate cash. On that basis, the DCF output sits modestly above the current $18.98 share price, implying the market is not fully crediting those forecast cash streams at the moment. Find out what Pebblebrook Hotel Trust could be worth using our Discounted Cash Flow (DCF) estimate.
The Pebblebrook Hotel Trust Narrative: What Would Justify Today's Price?
Narratives pick up where the DCF puzzle leaves off for Pebblebrook Hotel Trust by spelling out which paths for growth, margins and earnings would need to hold for the equity to be worth materially more or less than today’s price. Each one ties a specific fair value to a clear storyline about Pebblebrook Hotel Trust's potential catalysts and key risks, so you can track over time which version of events aligns with actual results on Simply Wall St's Community page.
The Pebblebrook Hotel Trust community is split, with one camp seeing meaningful upside and the other arguing expectations already look stretched.
Bull case: 14% undervalued
"Most major redevelopments (e.g., Newport Harbor Island Resort, Estancia, 1 Hotel San Francisco) are still ramping, indicating multiple years of strong EBITDA growth and margin expansion ahead..."
Discover why this Narrative puts Pebblebrook Hotel Trust at 14% undervalued.
Bear case: 34% overvalued
"Sustained adoption of remote and hybrid work models is likely to result in structurally lower corporate and group travel demand, especially for high-cost urban hotels in Pebblebrook's portfolio..."
Explore why this Narrative puts Pebblebrook Hotel Trust at 34% overvalued.
One more piece of the Pebblebrook Hotel Trust story to check
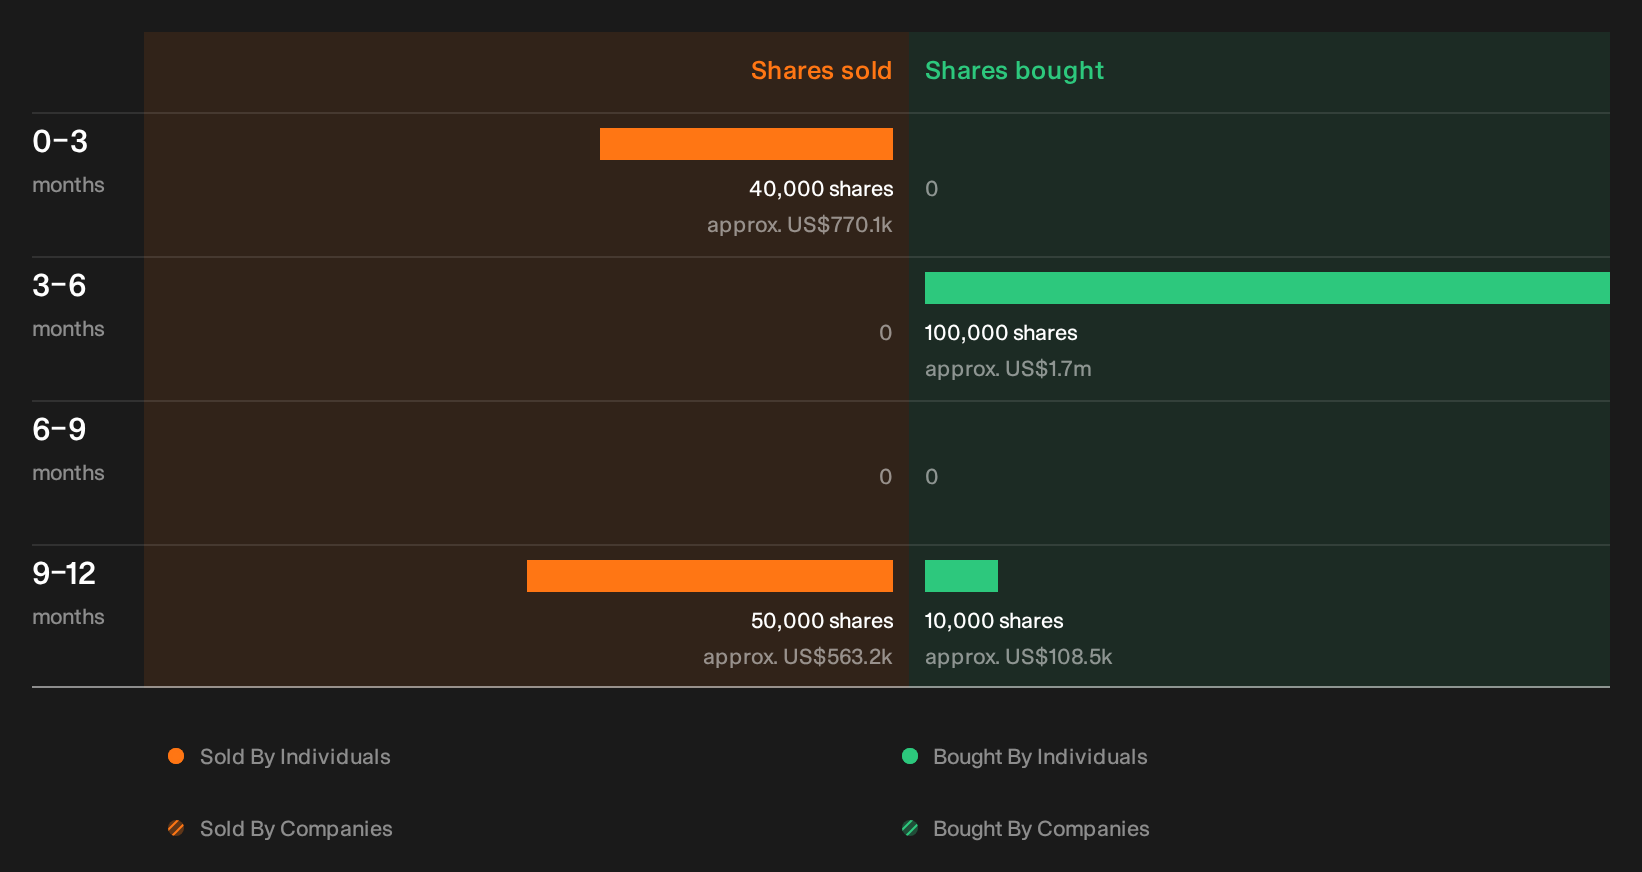
Before you put too much weight on any cash flow model for Pebblebrook Hotel Trust, it is worth seeing which insiders have been selling lately, how much stock they moved, and what that trading might signal for you. See the recent insider selling flagged for Pebblebrook Hotel Trust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com