
Planisware SAS (ENXTPA:PLNW) After SaaS Growth Narrative Leaves Investors Asking If The Stock Is Fully Valued
Planisware SAS (ENXTPA:PLNW) has attracted fresh attention after its recent share price move, with the stock last closing at €24.30. Investors are weighing this valuation against the firm’s latest reported revenue and earnings profile.
Recent trading has been choppy, with the share price slipping about 0.8% over the last day and 1.0% over the week. However, Planisware SAS still carries a 30-day share price return of 4.7%, a 90-day share price gain of 18.3%, and a 1-year total shareholder return of 19.2%. This suggests that while momentum has cooled in the very short term, it remains constructive over a longer stretch.
Scan 619 high quality undiscovered gems that share Planisware SAS’s SaaS profile and recent price momentum before they move onto more investors’ radars.
Planisware SAS now trades only slightly below analyst targets, even though the market still prices in some caution after the latest move. Is that discount a genuine opportunity, or a fair reflection of the risks?
Most Popular Narrative: 3% Undervalued
On the most followed view of Planisware SAS, the narrative fair value of about €25.13 sits slightly above the latest close at €24.30. That narrow gap leaves the spotlight on what might shift cash generation rather than on a big valuation mismatch today.
Ongoing accelerated digital transformation across industries, reflected in strong cross-selling to existing clients in IT governance and digitalization initiatives, continues to expand Planisware's addressable market and underpins future recurring revenue growth once decision cycles normalize.
Expansion of SaaS and cloud-based offerings, now representing 82% of total revenues and growing at 17%+, is structurally improving profitability through higher gross margins and may further expand net margins as SaaS mix increases.
See why 3 investors see Planisware SAS as 3% undervalued.
Result: Fair Value of €25.13 (UNDERVALUED)
Still, the story can unravel if elongated customer decision cycles drag on, or if Planisware SAS leans too heavily on upselling existing clients for growth.
Find out about the key risks to this Planisware SAS narrative.
Another Angle On Planisware SAS: Price Tag Versus Peers
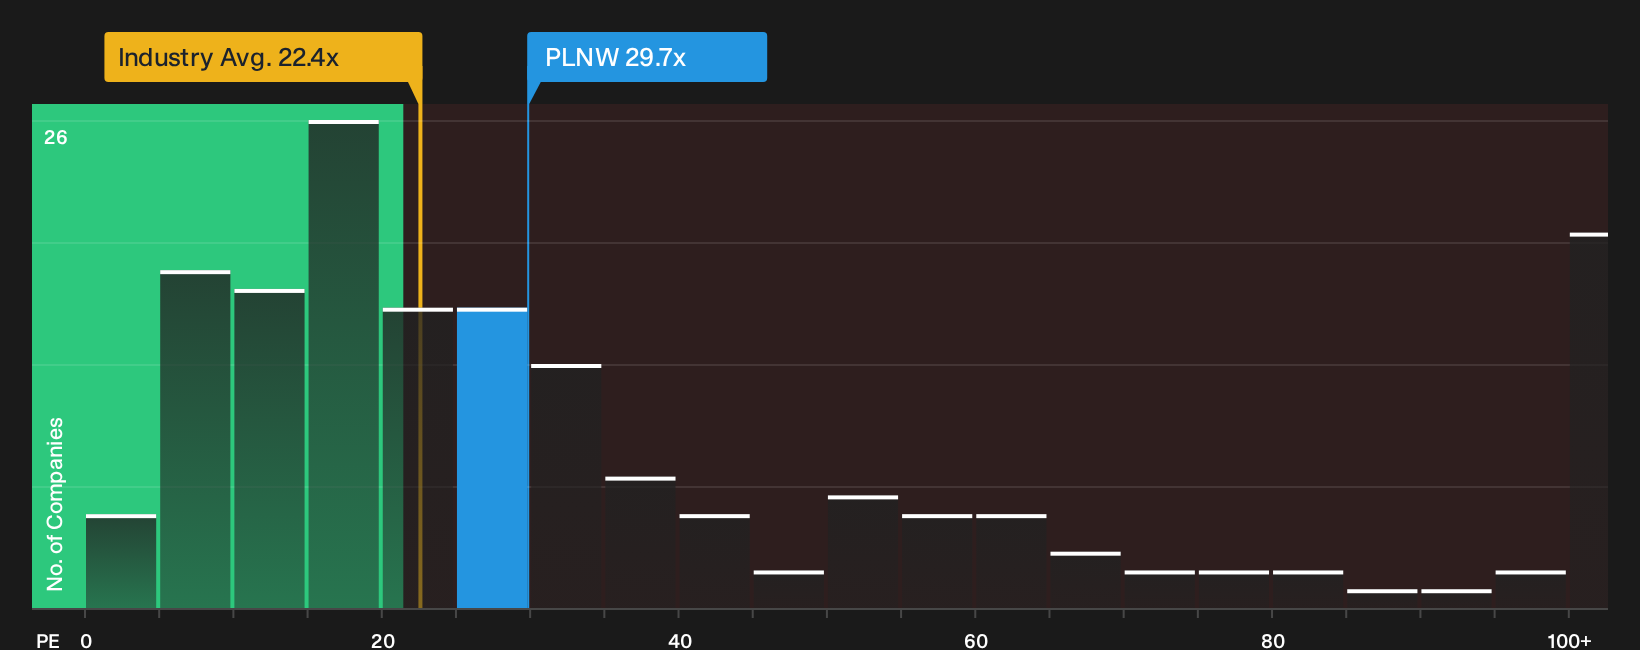
The earlier narrative argues Planisware SAS looks about 3% undervalued on analyst fair value. On plain earnings math, the picture changes. The stock trades on roughly 29.7x P/E, compared with about 22.5x for the European software group and a 23.1x peer average.
The fair ratio for Planisware SAS is estimated at 22.3x P/E. That is a clear gap. If the market ever leans closer to that multiple instead of the current premium, investors would be paying less for each euro of profit than today. The question is whether current growth and quality really justify that extra price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the cautious tone and the optimistic signals around Planisware SAS? Put the numbers in context quickly and see what stands out in the 2 key rewards.
Looking For More Ideas Beyond Planisware SAS?
If Planisware SAS has your attention, do not stop here. Broaden your watchlist with a few focused stock ideas and keep your edge sharp.
- Target potential value opportunities by scanning the 178 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Strengthen your downside protection by reviewing the 225 resilient stocks with low risk scores that aim for steadier returns with fewer financial red flags.
- Upgrade the quality of your watchlist by filtering for companies in the list of solid balance sheet and fundamentals (205 results) so you are not caught off guard by weak finances.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com