
Is Power Integrations (POWI) Undervalued Following Its Pullback Or Is Growth Already Priced In?
Recent trading in Power Integrations (POWI) has drawn attention after a sharp pullback over the past 3 months, even though the stock remains well above its level at the start of the year.
Power Integrations now trades at US$49.89, with the share price down 30.8% over the past 3 months but still showing a 33.8% year to date share price return and a 35.3% total shareholder return over 12 months. This suggests recent momentum has faded even as the longer patch has been rewarding for holders.
Spot shifting sentiment around Power Integrations, and then widen your watchlist with a curated set of resilient alternatives in our 31 resilient stocks with low risk scores.
Power Integrations now trades well below the average analyst price target, while one intrinsic value estimate points the other way. So where does a reasonable fair value range really sit after this pullback?
Most Popular Narrative: 35.6% Undervalued
Against the last close at $49.89, the most followed narrative pegs fair value for Power Integrations at $77.50, creating a wide gap that hinges on how its high voltage GaN and electrification bets play out over the next few years.
Power Integrations' proprietary high-voltage GaN technology, now extending from 750–1700 V up to 2,200 V and reaching into applications that have used silicon carbide, supports premium positioning in higher power systems and has the potential to lift average selling prices and gross margins.
Energy storage and renewable infrastructure projects that are adopting higher-voltage silicon-carbide architectures and already using SCALE-2 gate drivers from Power Integrations point to additional design wins and volume ramps that could support industrial revenue and operating margin over time.
See why 9 investors see Power Integrations as 36% undervalued.
Result: Fair Value of $77.50 (UNDERVALUED)
Still, the narrative around Power Integrations can be knocked off course if appliance demand weakens further or if the very high P/E multiple compresses following an earnings stumble.
Find out about the key risks to this Power Integrations narrative.
Another View: Power Integrations On Earnings Multiples
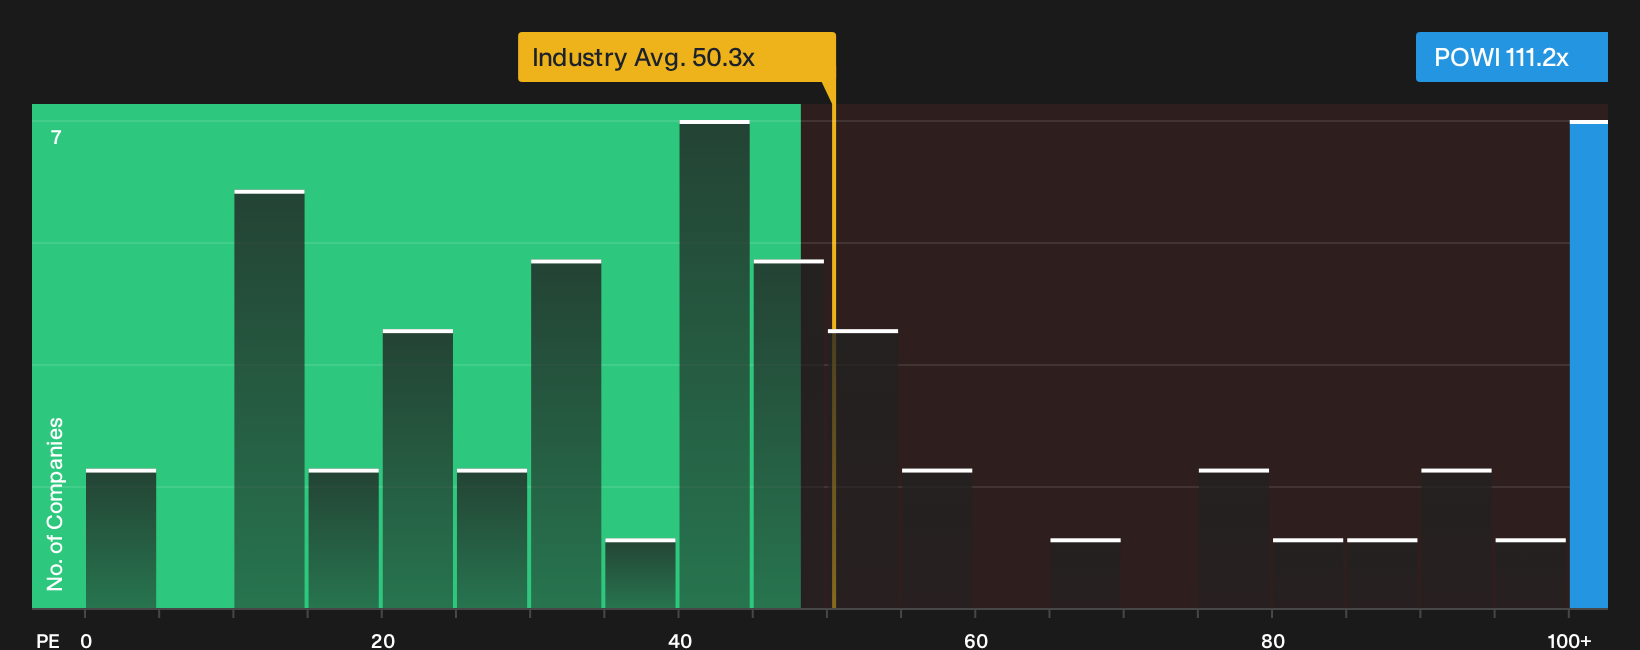
The fair value narrative around Power Integrations leans heavily on long term growth, yet the current P/E of 111.2x tells a tougher story. That multiple sits well above the US Semiconductor industry at 52.1x, the peer group at 39.6x, and an estimated fair ratio of 38.6x, which signals a lot of optimism already in the price and limited room if execution slips.
For a clearer sense of how that pricing gap could matter for your own thesis, it helps to see what the numbers say in context, then decide whether you agree with the risk and reward trade off in that higher multiple. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Power Integrations story today. If you want to move quickly and rely on your own judgment, start by weighing both sides of the ledger using our 2 key rewards and 3 important warning signs.
Looking for more Power Integrations investment ideas?
If you stop with Power Integrations alone, you risk missing opportunities that better fit your goals, risk comfort, and income needs across the market.
- Target resilient balance sheets and steady fundamentals by scanning companies in our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by reviewing the valuations in our 27 high quality undervalued stocks.
- Strengthen your income stream by checking companies offering robust yields in our 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com