
Calumet (CLMT) Draws Fresh Attention, Is The Rally Already Pricing In The Upside?
Calumet (CLMT) is back on investor screens after a sharp reset in earnings expectations, with analysts lifting current year EPS consensus and the stock strongly outperforming the broader Oil and Gas sector this year.
That surge in interest has come alongside powerful price action, with Calumet’s share price delivering a 46.31% 3 month return and a 195.40% year to date share price return, while the 1 year total shareholder return of 217.66% signals strong momentum rather than a short lived spike.
Scan for other energy refiners showing strong sentiment shifts and earnings revisions by reviewing our hand picked list of 27 high quality undervalued stocks alongside Calumet.
After a move like this, Calumet now calls for closer scrutiny. Do current valuation marks still leave enough upside to justify the operational and policy risks buyers are taking on?
Most Popular Narrative: 8% Overvalued
Calumet’s most followed narrative pegs fair value at $53.40, which sits below the last close of $57.75 and frames the recent rally as pricing in a lot of good news already.
The MaxSAF 150 project is on track to start up in the first half of 2026. This will enable Calumet to produce 120-150 million annual gallons of sustainable aviation fuel (SAF) at relatively low capital costs. The project is expected to capture premiums of $1-$2 per gallon over renewable diesel and tap into mandated and voluntary SAF demand globally. Once operational, this is expected to drive a material increase in revenues and EBITDA margin expansion.
See why 5 investors see Calumet as 8% overvalued.
Result: Fair Value of $53.40 (OVERVALUED)
Still, the Calumet story carries real tripwires, including high leverage that limits flexibility and regulatory shifts that could quickly squeeze renewable fuel economics.
Find out about the key risks to this Calumet narrative.
Another View: Calumet Looks Cheap On Cash Flows
The overvalued fair value narrative around Calumet meets a very different conclusion when using the SWS DCF model. On that framework, the stock at $57.75 is trading well below an estimated future cash flow value of $156.08, implying a wide valuation gap that investors need to interpret. Is the market discounting execution and balance sheet risk too heavily, or are the cash flow assumptions too generous?
Look into how the SWS DCF model arrives at its fair value.
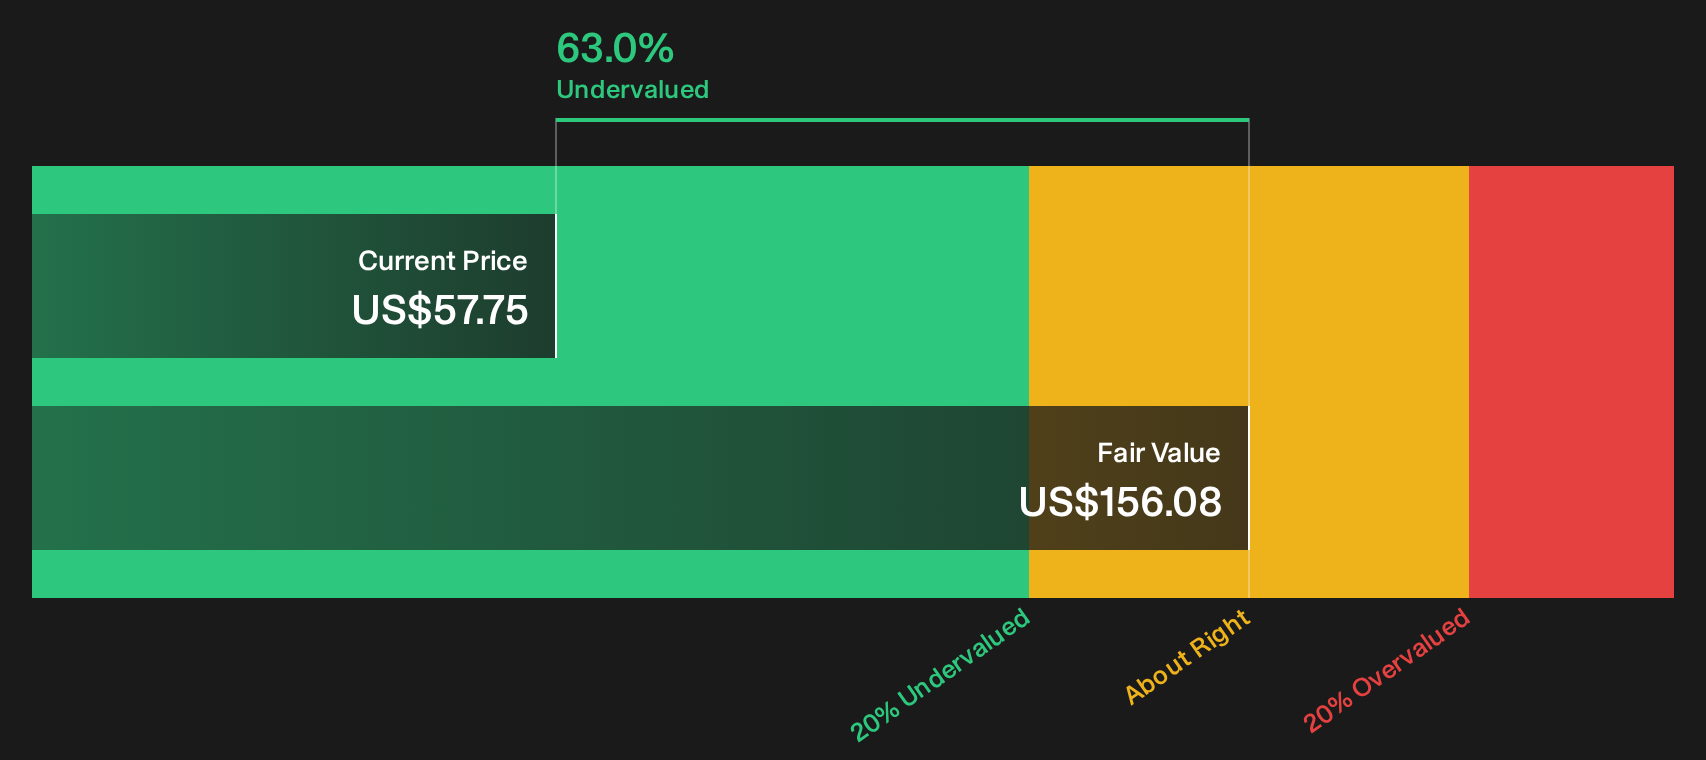
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Calumet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Calumet debate feels split between risk and reward, move quickly, review the underlying metrics, and weigh 3 key rewards and 1 important warning sign against your own judgement.
Looking for more Calumet investment ideas?
If Calumet has sharpened your focus, do not stop here. Broaden your watchlist today with other opportunities filtered by clear, data driven rules.
- Target potential bargains that pair quality fundamentals with a discount to intrinsic value through our curated set of 27 high quality undervalued stocks.
- Strengthen your income stream by focusing on resilient businesses with higher yields using our hand picked group of 8 dividend fortresses.
- Prioritise resilience by zeroing in on companies screened for robust finances and durable balance sheets in our focused list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com