
What REA Group Bears Saw Before The Fall
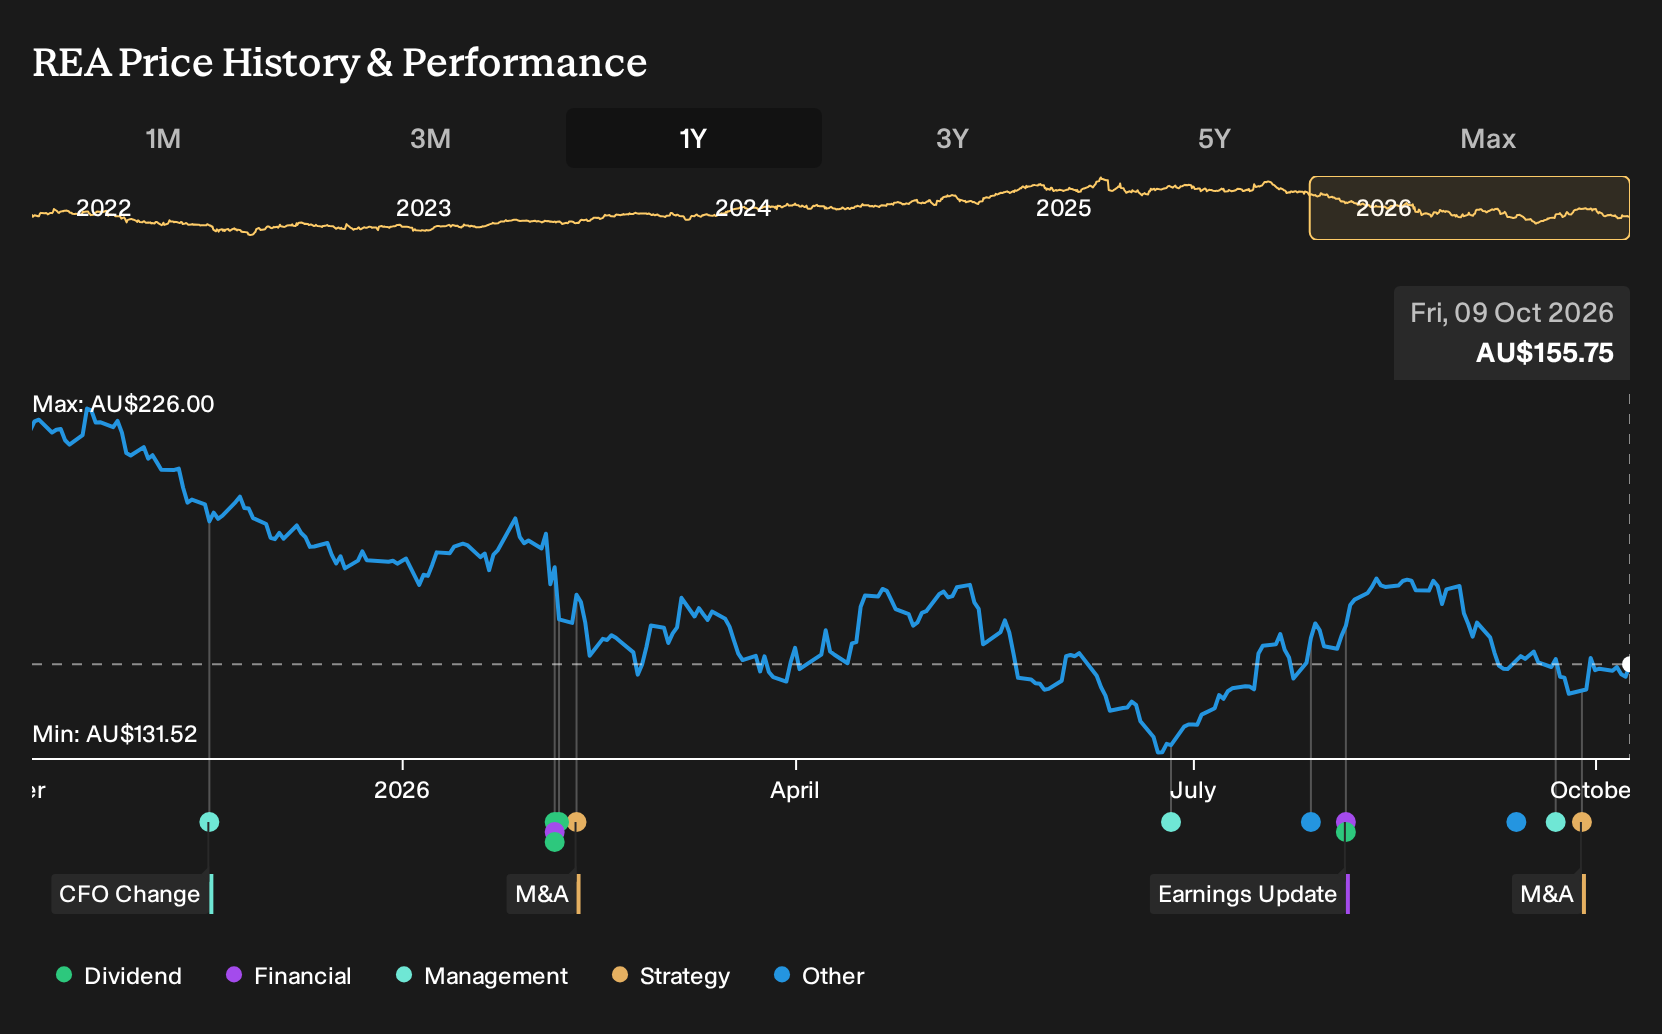
REA Group grabbed headlines with its A$409 million move into Ireland, expanding into Distilled’s Daft.ie and PropertyPal just as questions around its Australian property cycle and ACCC scrutiny grew louder. Holding REA Group over the past year would have meant a 28.9% loss, including dividends. If you had been weighing a purchase back on 9 October 2025, how should that mix of growth bets and regulatory pressure have shaped your expectations?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind REA Group. Zero in on 4 high quality undervalued stocks for companies trading below our estimates.
The Two REA Group Stories Investors Had To Weigh
The shares cost A$222 at the start of the period, so any thesis on REA Group needed to stack up against that entry point.
The bullish narrative saw Fair Value at A$256, or 15% above the start price. This view hinged on assumptions like 7.1% annual revenue growth and profit margins rising to 38.8% within three years.
The bearish view put Fair Value at A$132, or 41% below the start price. This perspective focused on risks such as long term demographic pressure on Australian housing transactions and tighter data privacy rules squeezing advertising products and AI returns.
What The Results Put To The Test For REA Group
REA Group’s A$409 million move for a 35% stake in Distilled backed the growth story that assumed new markets could support premium classifieds and vendor paid ads. The numbers told a tougher story. Revenue rose from A$1,767.3m to A$1,976.9m, while net income slipped from A$708.4m to A$673.0m and net margin declined from 40.1% to 34.0%. The evidence cut both ways.
The lesson is simple. When a thesis leans on rising profitability, check whether net margin is actually moving up alongside new deals, not just whether sales are growing.
What The Fall In REA Group’s Share Price Now Asks You To Consider
REA Group trades at A$156 today, below where holders started one year ago. The selected Narrative’s Fair Value sits above the current price, based on a view that premium listing products, AI tools and newer financial services can carry more of the earnings load over time.
The key question is whether you think that playbook holds. A buyer today would need to believe REA can turn product depth, data and finance into meaningfully higher long term profitability despite competition and regulation.
"Key Takeaways: Expansion into premium products and financial services, alongside AI integration, is expected to support revenue growth and higher profit margins. A strong market position may enable REA to become a more comprehensive property platform, potentially unlocking additional revenue streams and enhancing long-term customer value."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 28% below our estimate - supplies critical replacement parts and diagnostic support that keep heavy vehicles operating efficiently.
- Company 2 - 35% below our estimate - uses a dense store network and installation services to capture comprehensive home-upgrade projects.
- Company 3 - 32% below our estimate - designs integrated audio visual and electrical systems that replace multiple specialist contractors with one provider.
That is three of the list. See every one of the 12 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com