
Will Planned Retirement Change Hamilton Lane (HLNE) Narrative
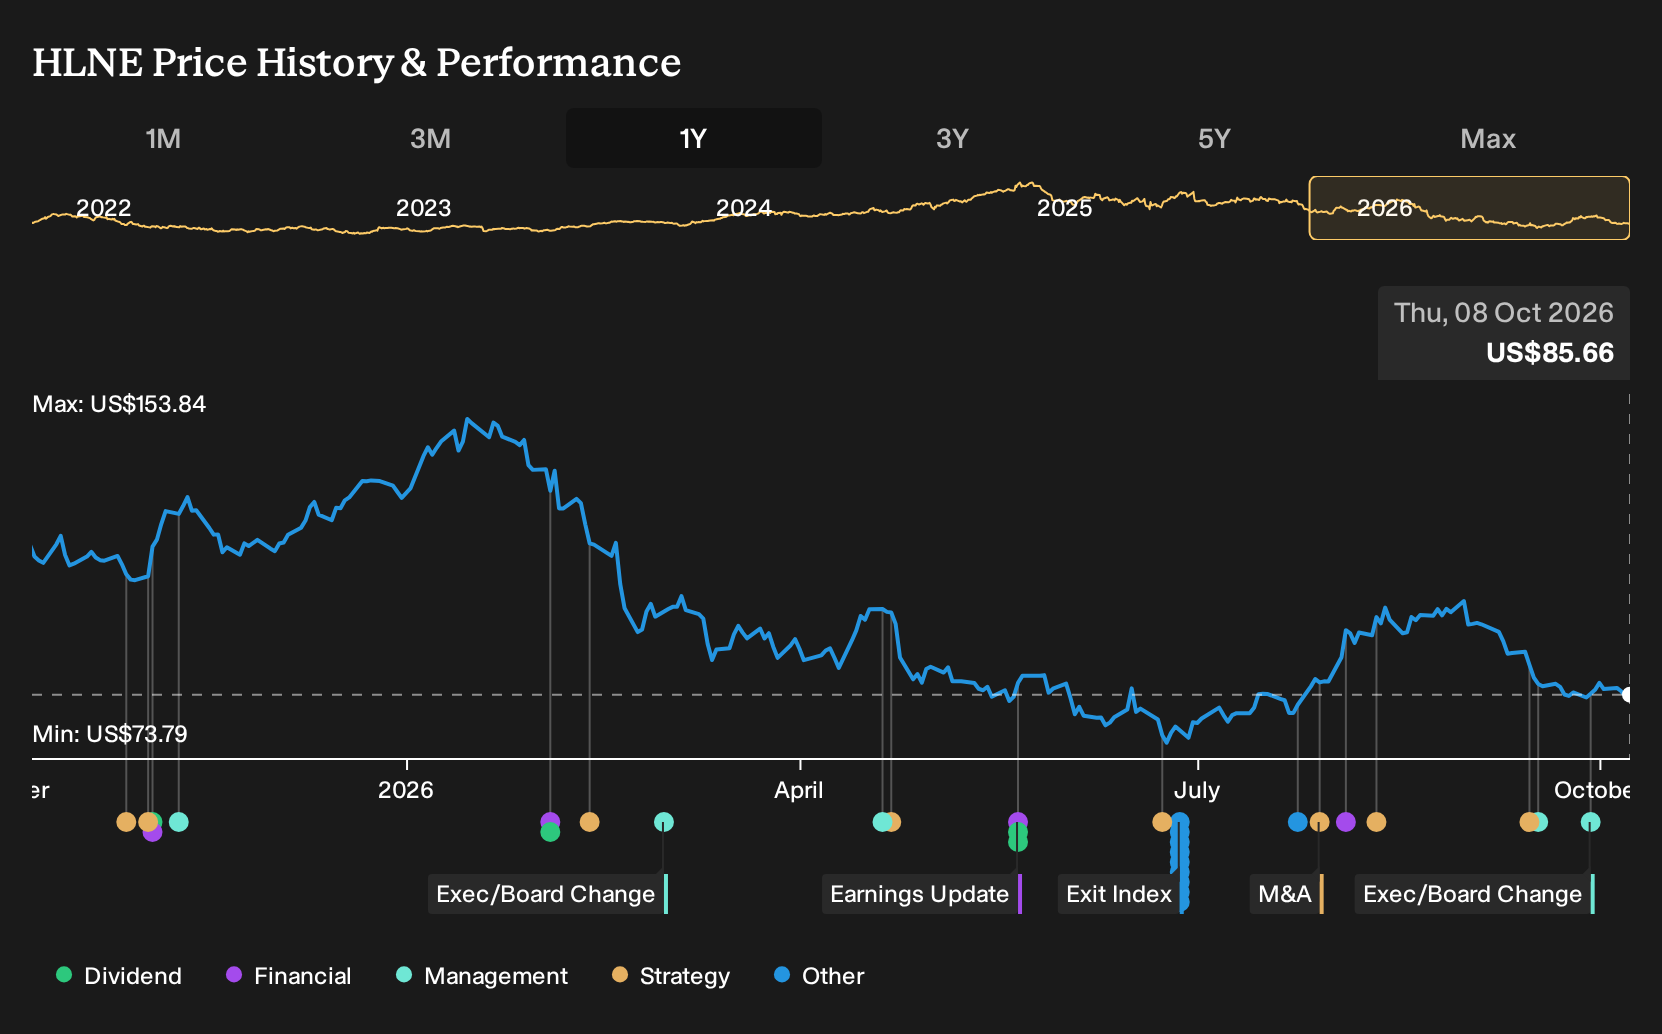
- Hamilton Lane reported that Executive Co Chairman Mario Giannini, a key figure since 1993 and former long serving CEO, plans to retire on 31 March 2027, with Executive Co Chairman Hartley Rogers set to continue as Executive Chairman and Board Chair after that date.
- Giannini has shaped Hamilton Lane's expansion, public listing and market commentary for decades, so his planned exit highlights long term succession planning as a central operational theme for this private markets manager.
- We will now look at how Hamilton Lane's investment narrative could be influenced by Giannini's planned retirement and leadership transition.
See how Hamilton Lane compares with other private markets specialists by reviewing a curated set of 20 high quality undiscovered gems that may be flying under most investors' radar.
Hamilton Lane Investment Narrative Recap
To own Hamilton Lane, you need to believe its private markets platform, evergreen products and global distribution can keep attracting fresh client capital and fee based assets. The immediate operational focus stays on sustaining inflows into evergreen and specialized vehicles, which have been key revenue drivers. Mario Giannini’s retirement in 2027 appears well telegraphed, so the short term business catalyst around fundraising and product traction is largely unchanged.
The bigger near term watchpoint is not this leadership news, but pressure points such as fee compression, heavier regulation and rising competition in alternatives. Succession could matter if clients link Giannini closely to Hamilton Lane’s market commentary and data driven culture. For now, co CEOs Juan Delgado Moreira and Erik Hirsch already run day to day operations, so the main risk remains fundraising or margin pressure rather than abrupt management disruption.
The most relevant recent development is the earlier transition where Giannini handed the CEO role to Juan Delgado Moreira and Erik Hirsch in 2023, while remaining Executive Co Chairman. That earlier move gave the current leadership a runway to build their own track record across evergreen funds, new geographies and technology offerings before his full exit in 2027.
For investors, that staggered handover ties directly into today’s catalysts. Execution on evergreen AUM growth, separate accounts and tech enabled solutions will be judged primarily on the co CEOs’ performance, with Giannini providing continuity on market commentary through the 2027 Market Overview. The risk is that any slip in fundraising, margins or client retention now sits squarely with the new leadership team, which investors are likely to watch closely.
Hamilton Lane's current analyst narrative points to revenues of about $1.1b and earnings of $496.8 million by 2029. This implies forecast revenue growth of 13.9% per year and an earnings increase of roughly $247.6 million from $249.2 million today.
Uncover how Hamilton Lane's fair value indicates a 51% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
Some analysts put a different spotlight on Hamilton Lane. Rather than focusing on fee compression, the bullish camp leans on the Evergreen platform as a potential long term fee engine, backing forecasts of about $1.2b in revenue and $521.2 million in earnings by 2029. Those estimates were set before this retirement news, so views may shift.
Explore 8 other Hamilton Lane fair value estimates, including one that suggests as much as 211% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hamilton Lane research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hamilton Lane. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Hamilton Lane's overall financial health at a glance.
Looking for more investment ideas beyond Hamilton Lane?
If this leadership story has sharpened your view on Hamilton Lane, it can be useful to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for traits that match your own approach, rather than relying on one headline or one forecast.
- If you care most about quality at a sensible entry point, start with a focused group of 27 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- For income focused portfolios, scan a hand picked set of 8 dividend fortresses that aim to combine higher yields with more resilient payouts.
- If capital preservation sits higher on your list, narrow your search to a 31 resilient stocks with low risk scores that screens for steadier balance sheets and more measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com