
American Homes 4 Rent (AMH) Lifts FFO Guidance, Is The 18% Undervalued View Enough?
American Homes 4 Rent (AMH) drew fresh attention after its second quarter update, which lifted core FFO per share guidance to $1.95 and highlighted 96% same home occupancy with 2.3% core revenue growth.
The guidance lift has arrived after a choppy year for American Homes 4 Rent, with the share price at $30.49, a 90 day share price return that declined 8.36%, and a 1 year total shareholder return that fell 2.31% as investors reassess income potential and risk.
Spot similar income focused real estate plays by scanning our hand picked 8 dividend fortresses that might complement a position in American Homes 4 Rent.For American Homes 4 Rent, a softer share price sitting near $30 is rubbing against firmer operating metrics. Is that signaling a cheaper entry, or is cooler sentiment simply catching up to the business story?
Most Popular Narrative: 18% Undervalued
Against a last close of $30.49, the most followed narrative puts American Homes 4 Rent’s fair value at $37.11. This frames today’s softer price as a discount that hinges on the quality of its development pipeline and capital recycling.
Portfolio optimization through MLS dispositions at cap rates in the 4% area, combined with recycling proceeds into higher yielding on balance sheet and joint venture development, creates a spread between sale yields and development yields. This can support higher net operating income and funds from operations per share (net margins and earnings).
See why 7 investors see American Homes 4 Rent as 18% undervalued.
Result: Fair Value of $37.11 (UNDERVALUED)
Still, the bullish case for American Homes 4 Rent leans on some fragile pillars, including the risk that higher funding costs or stubborn supply in key markets compress returns and weaken rent economics.
Find out about the key risks to this American Homes 4 Rent narrative.
Another View On American Homes 4 Rent’s Valuation
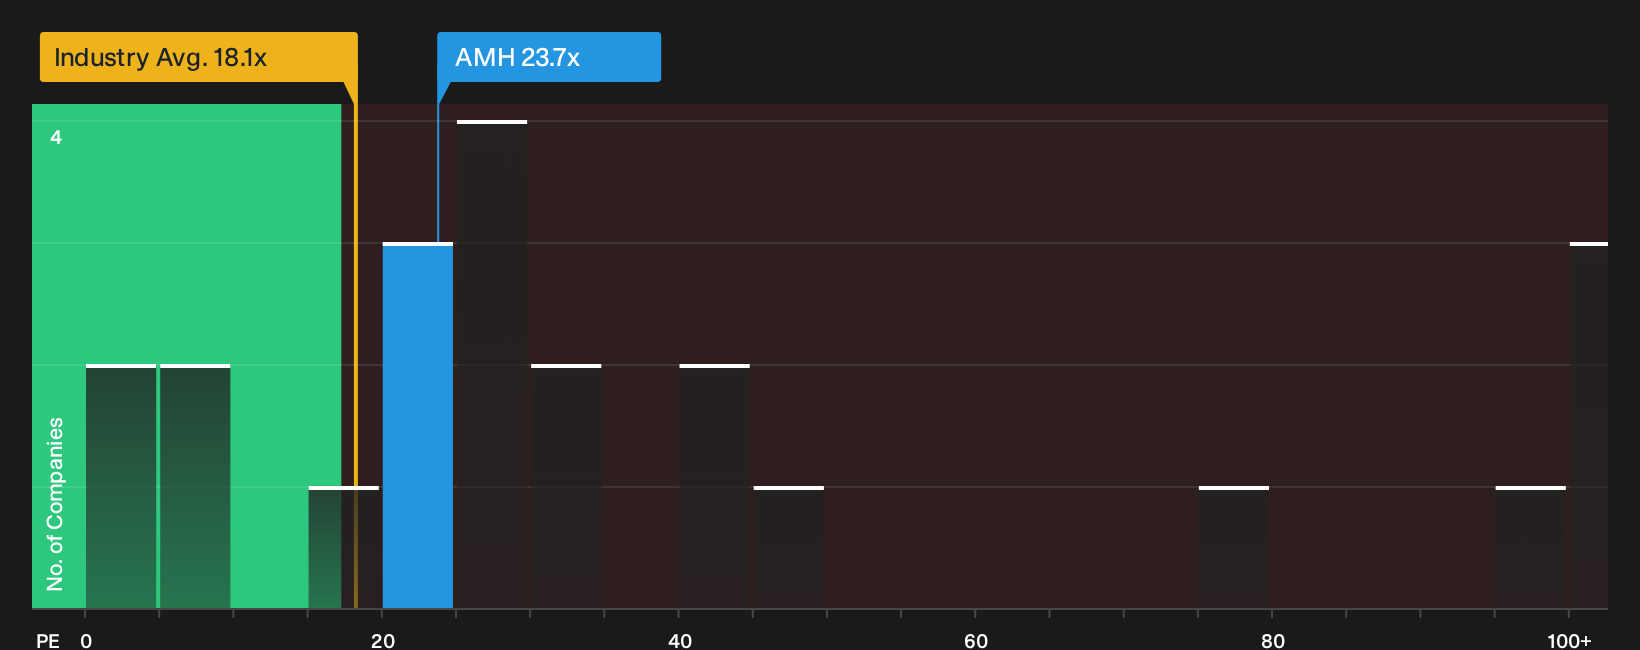
Those fair value estimates around $37 lean heavily on future cash flow assumptions. The share price tells a different story when you look at simple earnings multiples. American Homes 4 Rent trades on a P/E of 23.7x, which is higher than the global Residential REITs average of 17.9x and above its own 21.5x fair ratio. That mix of discount-to-fair-value narratives and richer-than-industry pricing raises a basic question: Is the real opportunity in the current yield and business quality, or in expecting the market to keep paying up for slower earnings growth?
To pressure test that view against the earnings multiple and fair ratio, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on American Homes 4 Rent’s value case can be confusing, so move quickly, review the data, and shape your own view with the 4 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond American Homes 4 Rent?
If American Homes 4 Rent has you rethinking income and value, do not stop here. Broaden your watchlist with fresh ideas that could reshape your portfolio.
- Target potential mispricing by reviewing companies on the 27 high quality undervalued stocks that blend stronger fundamentals with prices the market has not fully rewarded yet.
- Strengthen your downside protection by scanning the 31 resilient stocks with low risk scores where resilient balance sheets and steadier risk profiles take priority.
- Spot future contenders early by checking the 20 high quality undiscovered gems before they attract wider attention and capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com