
Will Exclusive Leasing Role Change JLL's (JLL) Narrative
- The San Francisco Recovery Fund announced that BXP has been retained to help deliver the Fifty at First office project for a 2031 opening, with Jones Lang LaSalle appointed as the exclusive office leasing agent to bring tenant and market insight to the development.
- JLL’s exclusive role on Fifty at First gives the firm a long runway to influence leasing terms, tenant mix and workplace design requirements in a key US gateway market.
- We will now examine how Jones Lang LaSalle's investment narrative could be influenced by its exclusive leasing mandate for Fifty at First.
Scan how a long-dated leasing win like Jones Lang LaSalle's Fifty at First mandate fits into a broader office recovery story by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Jones Lang LaSalle Investment Narrative Recap
To own Jones Lang LaSalle, you need to believe the shift toward outsourced real estate services, data rich advice and recurring workplace contracts keeps building, even as office exposure stays meaningful. The Fifty at First leasing mandate fits that view as a proof point for JLL’s role in complex, multi year urban office projects rather than a swing factor on its own.
The key near term swing factor still sits in transaction activity in Capital Markets and Leasing. Any renewed slowdown there would affect operating leverage faster than one San Francisco project can offset. The largest risk remains prolonged weak office demand, which could weigh on leasing, management fees and net margins.
Among the recent announcements, the most relevant here is JLL’s exclusive leasing role at Fifty at First. This gives the firm a long dated, high profile mandate in a US gateway city, which can support its advisory credentials and data insights as employers reassess what they want from downtown space.
The project aligns with existing catalysts around workplace management, project management and integrated sustainability focused advice. Execution risk still lies in filling a large office asset in a market where vacancies remain a concern. If JLL can convert design input and tenant analytics into committed occupiers on reasonable terms, that would support its broader office related fee story.
What The Fifty at First Win Sits On Top Of
Jones Lang LaSalle's role at Fifty at First connects to analyst expectations that the group can keep scaling fee income, rather than existing in a vacuum as a single headline mandate. The development lines up with a wider move toward multi year, advisory heavy work where insight into tenant demand, workplace layout and sustainability targets matter as much as filling the building.
Analysts currently model revenue rising at 7.8% a year over the next three years, with profit margins moving from 3.6% today to 4.2% by 2029. On those assumptions, earnings today of $999.1 million are expected to reach $1.4b by 2029, which implies an increase of a little over $400 million in profit that needs to be delivered through a mix of higher fees, better contract terms and operating efficiency.
That future profile underpins a forecast for revenues of $34.4b and earnings of $1.4b in 2029, along with a P/E of 16.3x compared with 14.2x now for Jones Lang LaSalle and 15.0x for the wider US real estate sector. Analyst models also work off share count shrinking by 2.51% a year for three years and use an 8.69% to 8.7% discount rate to pull those earnings and cash flows back into today's valuation debate.
The Fifty at First mandate fits inside that earnings path as one of many office related and data heavy projects that need to feed into the $34.4b revenue and $1.4b earnings estimates. If the San Francisco office lease up proves slow or incentives run rich, that would not automatically break the broader thesis, though it would remind investors that a meaningful portion of the business still leans on cyclical office demand and transaction volumes.
Jones Lang LaSalle's narrative projects $34.4b revenue and $1.4b earnings by 2029, which rests on 7.8% yearly revenue growth and an earnings increase of about $400.9 million from $999.1 million today.
Discover why Jones Lang LaSalle's fair value points to a 41% potential upside to its current price, which could narrow quickly.
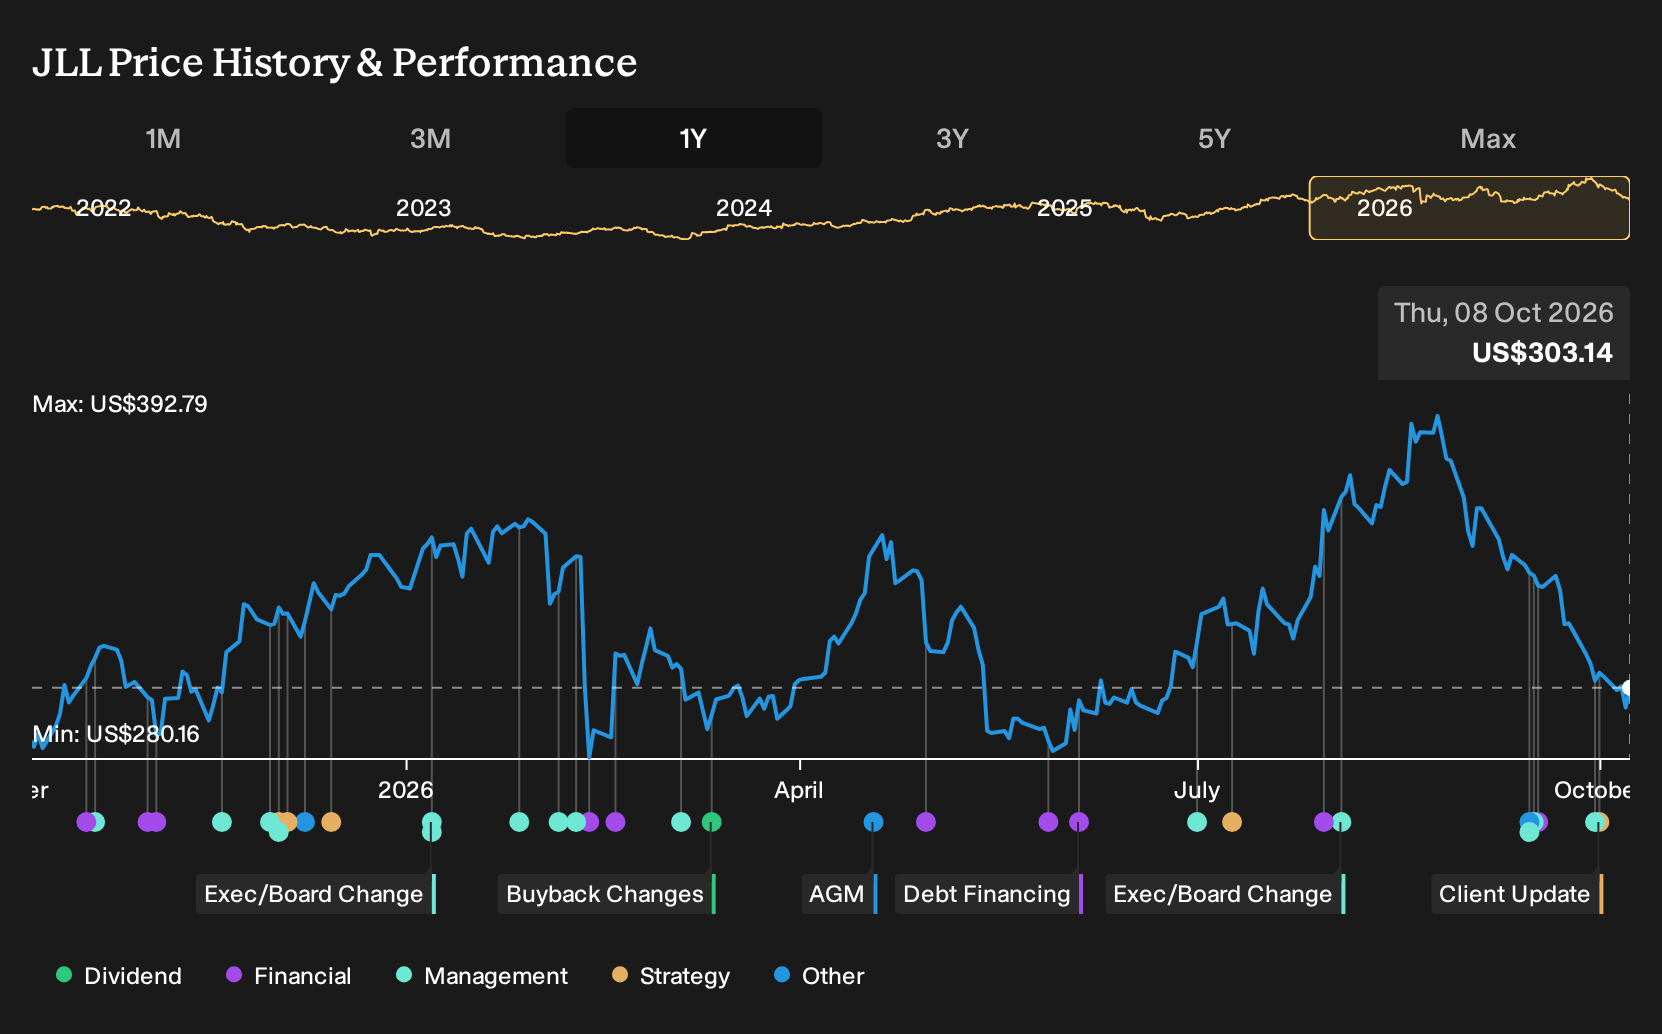
Exploring Other Perspectives
Some of the most optimistic analysts focus less on office risk and more on Jones Lang LaSalle’s AI driven productivity story. Before this San Francisco mandate, they were pencilling in revenue of about $36.0b and earnings near $1.5b by 2029. You can treat those upbeat assumptions as one end of a wide range of possible views that may shift after the news.
Explore 2 other Jones Lang LaSalle fair value estimates, including one that suggests potential upside of up to 107% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jones Lang LaSalle research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Jones Lang LaSalle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jones Lang LaSalle's overall financial health at a glance.
Looking for more investment ideas beyond Jones Lang LaSalle?
If Jones Lang LaSalle has sharpened your thinking about what you want from a real estate focused holding, the next step is to widen the search. Use the Simply Wall St Screener to quickly surface other businesses that match your risk tolerance and return goals, then compare them side by side with JLL.
- If capital protection sits near the top of your list, start with companies that pair steady fundamentals with lower risk profiles by scanning the 31 resilient stocks with low risk scores.
- For investors hunting for quality at a sensible entry point, filter for sound businesses trading below their estimated worth using the 27 high quality undervalued stocks.
- Those who care most about resilient balance sheets and solid financial footing can focus on strong cash positions and manageable debt by reviewing the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com