
Acushnet Holdings (GOLF) Draws Fresh Attention, Is The Stock Cheap Or Pricey?
Recent coverage of Acushnet Holdings (GOLF) has focused on Argus lifting its view on the stock, prompting fresh attention on how the golf equipment and apparel specialist is currently valued by the market.
Over the past few months, momentum around Acushnet Holdings has softened, with the share price down 7.75% over 30 days and 28.50% over 90 days to US$79.14, even though the 5-year total shareholder return of 75.49% highlights much stronger longer-term compounding.
Compare Acushnet Holdings with a hand picked group of golf adjacent and consumer brands that currently screen as 27 high quality undervalued stocks for their combination of quality and pricing support.
Acushnet Holdings appears to be a high quality golf franchise, yet the share price has retreated sharply in recent months. Is the current valuation treating a solid operator as a bargain or as a trap after a strong run?
Most Popular Narrative: 20.6% Undervalued
On the most followed view, Acushnet Holdings screens as undervalued, with a fair value estimate of $99.67 against the recent close at $79.14. This puts the spotlight on how much of its cash generation story is already reflected in the price.
The main thing that has to go right is that Acushnet converts its premium mix, custom fitting focus and recent capacity and technology investments into sustainably stronger profitability and cash generation despite ongoing tariff and cost pressures.
The current valuation and this narrative’s bullish stance together imply that the share price does not fully reflect the company’s recent sales and adjusted EBITDA performance, its capital returns and its progress on balance sheet strength.
See why 3 investors see Acushnet Holdings as 21% undervalued.
Result: Fair Value of $99.67 (UNDERVALUED)
Still, the bullish Acushnet Holdings story could wobble if weak free cash flow and recent insider selling begin to weigh more heavily on investor confidence.
Find out about the key risks to this Acushnet Holdings narrative.
Another View: What The P/E Ratio Says About Acushnet Holdings
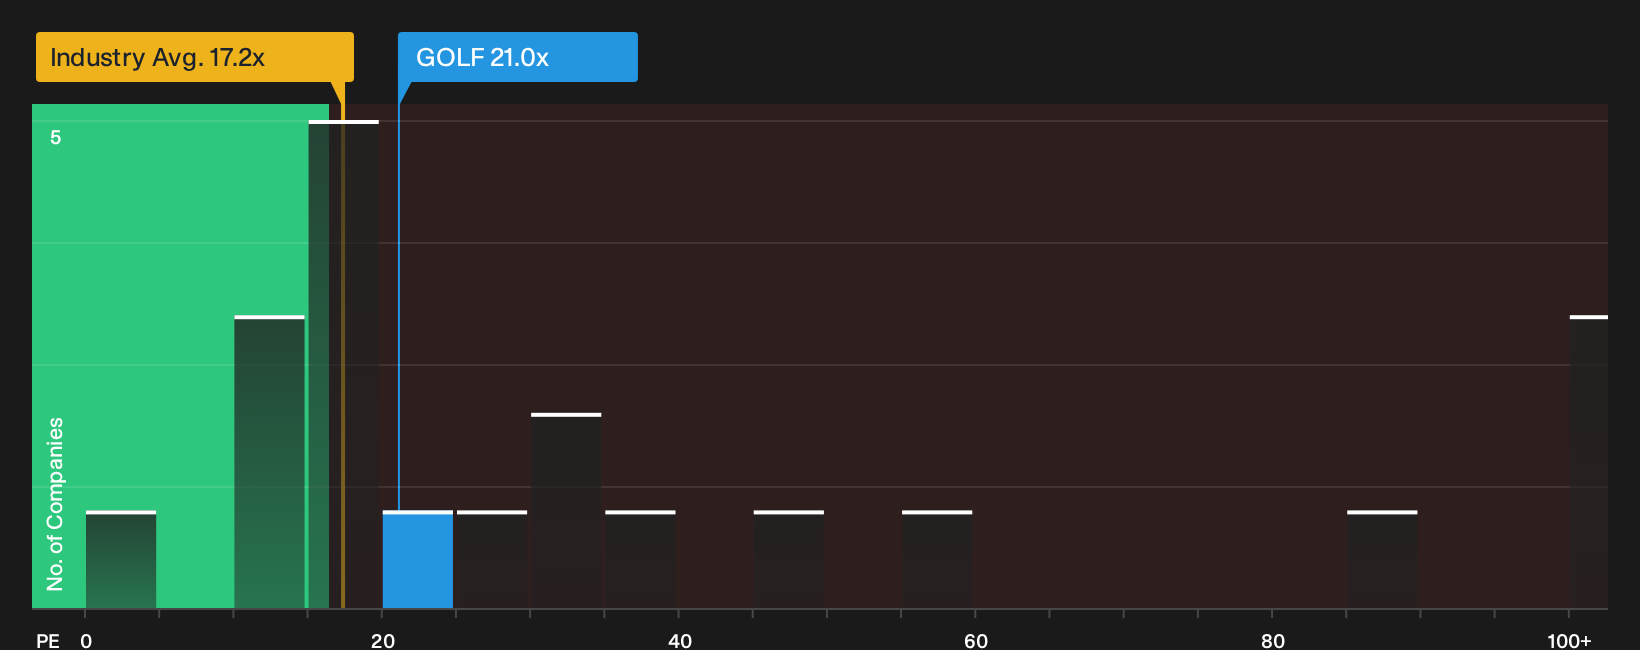
There is a very different read on Acushnet Holdings when switching from fair value models to the plain P/E multiple. The stock trades on roughly 21x earnings, compared with a fair ratio of 14.8x, the global leisure group at 17.6x and peers at 19.5x. That gap points to investors already paying a premium. Is the recent share price slide the start of a reset, or just noise before fundamentals catch up?
For a closer look at how this pricing compares with earnings power and sector norms, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment on Acushnet Holdings pulling in two directions, you can move quickly and test the narrative against the underlying data yourself. To weigh the trade off between the concerns being raised and the potential upside being highlighted by other investors, start by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Acushnet Holdings?
If the Acushnet Holdings debate has sharpened your thinking, do not stop here. Put that same discipline to work on a wider watchlist using targeted screeners.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (25 results) that can help you stress test ideas before capital goes to work.
- Hunt for mispriced quality by reviewing a curated 27 high quality undervalued stocks that filters for both financial strength and support from current pricing.
- Lock in potential income streams by sorting through a focused 8 dividend fortresses built for investors who care about yield and staying power together.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com