
Diamondback Energy (FANG) Stock Trades At A Premium On Earnings Expectations
Diamondback Energy has delivered strong long term gains for shareholders, which naturally puts the focus on whether the current share price lines up with what the business earns. With the stock now closely watched after a solid multi year run, the key issue is how much of those earnings are already reflected in the valuation.
- Over the past 5 years, Diamondback Energy has returned 117.7%, which puts real weight on the question of how much its earnings can justify today’s level.
- The business model is heavily tied to converting commodity production into consistent profits and cash generation, so expectations for future drilling returns and cost discipline can meaningfully shape how investors assess its earnings power.
- The analysts covering Diamondback Energy have run their own numbers. See what analysts think Diamondback Energy's shares could be worth.
The stock’s next move may depend on whether Diamondback Energy’s current price is reasonably explained by its earnings profile.
If you are weighing Diamondback Energy on its earnings, it can help to compare it with other companies screened for valuation and quality, starting with 27 high quality undervalued stocks.
Is Diamondback Energy Getting Expensive on Earnings?
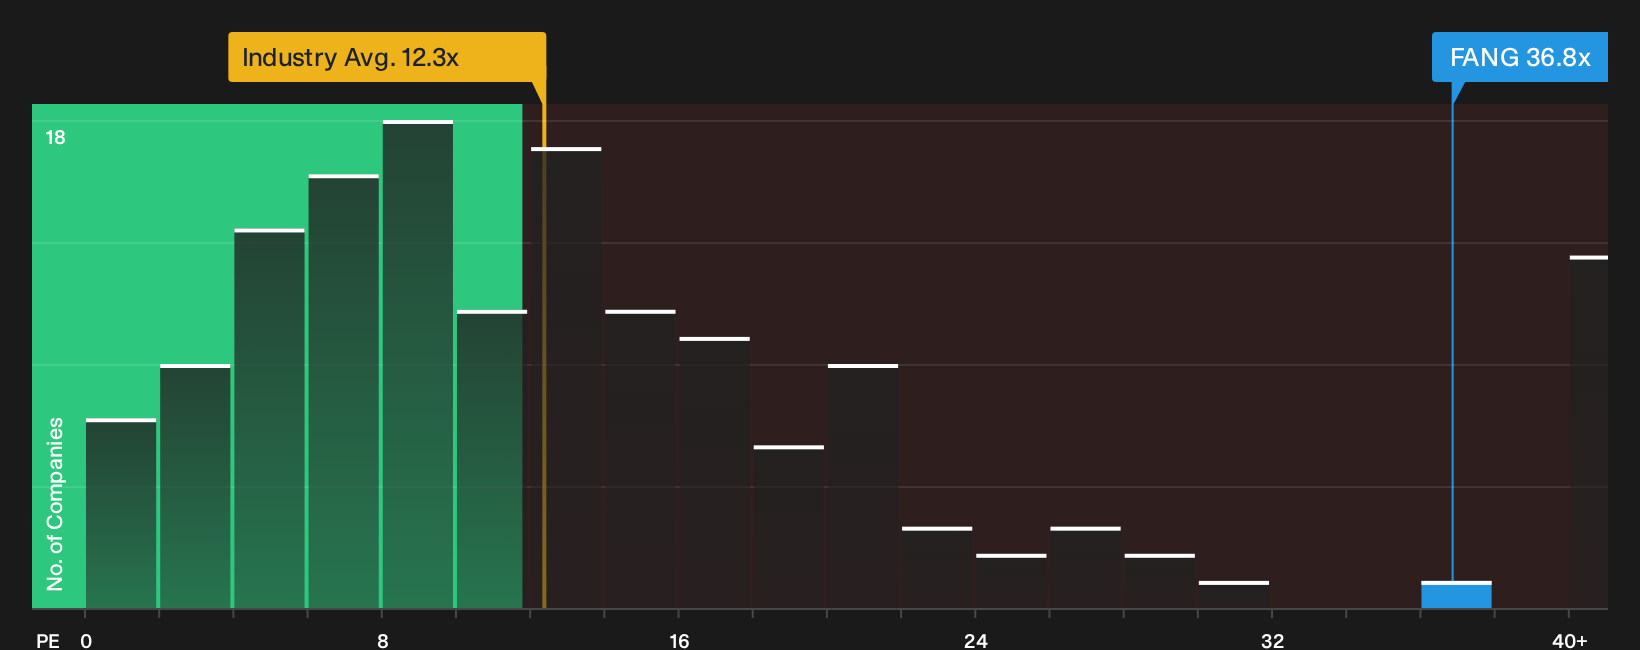
The P/E ratio fits Diamondback Energy because earnings are a central yardstick for how this kind of producer turns wells into shareholder value. On that metric, the stock trades around 36.8x earnings, which is much higher than the Oil and Gas industry average of about 12.3x and above the peer group near 12.0x. That puts a clear premium on Diamondback Energy’s profit stream compared with many similar operators that investors can choose from.
The tailored fair multiple that takes into account the company’s growth profile, margins, size and risk points to a lower P/E than where the shares change hands today, so the stock screens as overvalued on this framework rather than cheap. For a holder, the key question is whether Diamondback Energy’s earnings quality and future cash generation feel strong enough to justify paying well above both sector norms and that modelled fair range, or whether that gap signals a lot of good news already embedded in the price. Explore the numbers behind Diamondback Energy's P/E valuation.
The Diamondback Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Diamondback Energy's valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for the stock to be worth significantly more or less than it is today. Rather than stopping at a single output from a P/E or valuation model, Narratives lay out the future conditions that number relies on so you can watch how Diamondback Energy's real world progress compares.
One of the top community narratives on Diamondback Energy: 18% undervalued
"The current valuation implies that Diamondback Energy is treated more like a peer level, defensive cash generator rather than a premium growth and capital efficiency story…"
Discover why this Narrative puts Diamondback Energy at 18% undervalued.
One more Diamondback Energy check that sits beyond the share price
Price multiples tell only part of the story, because the people deciding how Diamondback Energy spends its cash and how they are rewarded can heavily shape long term outcomes for shareholders. See who runs Diamondback Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com