
Arrow Electronics (ARW) Nears Fair Value, Is The Earnings Story Enough?
Arrow Electronics (ARW) has been drawing fresh attention after its share price recently reached new all time highs, with the stock nearly doubling over the past year and outperforming its broader tech peers.
Recent trading has cooled slightly, with a 1-day share price return that declined 2.26% and a 7-day share price return that fell 2.11%. However, Arrow Electronics still carries a 30-day share price gain of 4.30% and a year-to-date share price return of 100.59%. This advance aligns with a 1-year total shareholder return of 92.47% and a 3-year total shareholder return of 96.25%, which indicates that momentum has been strong, even as short-term moves point to some reassessment of growth potential and risk.
Scan beyond Arrow Electronics and see how other tech distributors and hardware plays stack up on profitability, growth, and balance sheet strength using our hand picked list of solid balance sheet and fundamentals (25 results).
Arrow Electronics appears to be a heavyweight operator, with broad scale across components and enterprise computing and a long operating history. After a near doubling in the share price, the key question for investors is what they are now paying for that strength.
Most Popular Narrative: 4% Undervalued
Arrow Electronics is framed as slightly undervalued in the prevailing narrative, with a fair value of $235 against a last close of $226.75, which puts the recent share price surge in context rather than treating it as detached from fundamentals.
Productivity and cost saving initiatives, together with multi year restructuring that has brought operating expenses down to roughly 63% to 64% of gross profit and allowed non GAAP operating margins to reach about 4% of sales in the first half of 2026, provide operating leverage that can translate future revenue into earnings.
See why 2 investors see Arrow Electronics as 4% undervalued.
Result: Fair Value of $235 (UNDERVALUED)
Still, the bullish Arrow Electronics story can be shaken if ECS restructuring charges continue to bite, or if Supply Chain Services profitability stays below early 2026 levels.
Find out about the key risks to this Arrow Electronics narrative.
Another View: Arrow Electronics Through A Cash Flow Lens
The earlier fair value of $235 for Arrow Electronics leans on earnings based assumptions and market multiples. A different picture emerges when using the SWS DCF model, which points to a future cash flow value of $167.03 against the current $226.75 share price. That gap suggests investors need to ask what they trust more: the cash flows or the earnings story.
For readers who want to see how this cash flow view is built line by line, and how sensitive it is to small changes in growth or discount rates, Look into how the SWS DCF model arrives at its fair value.
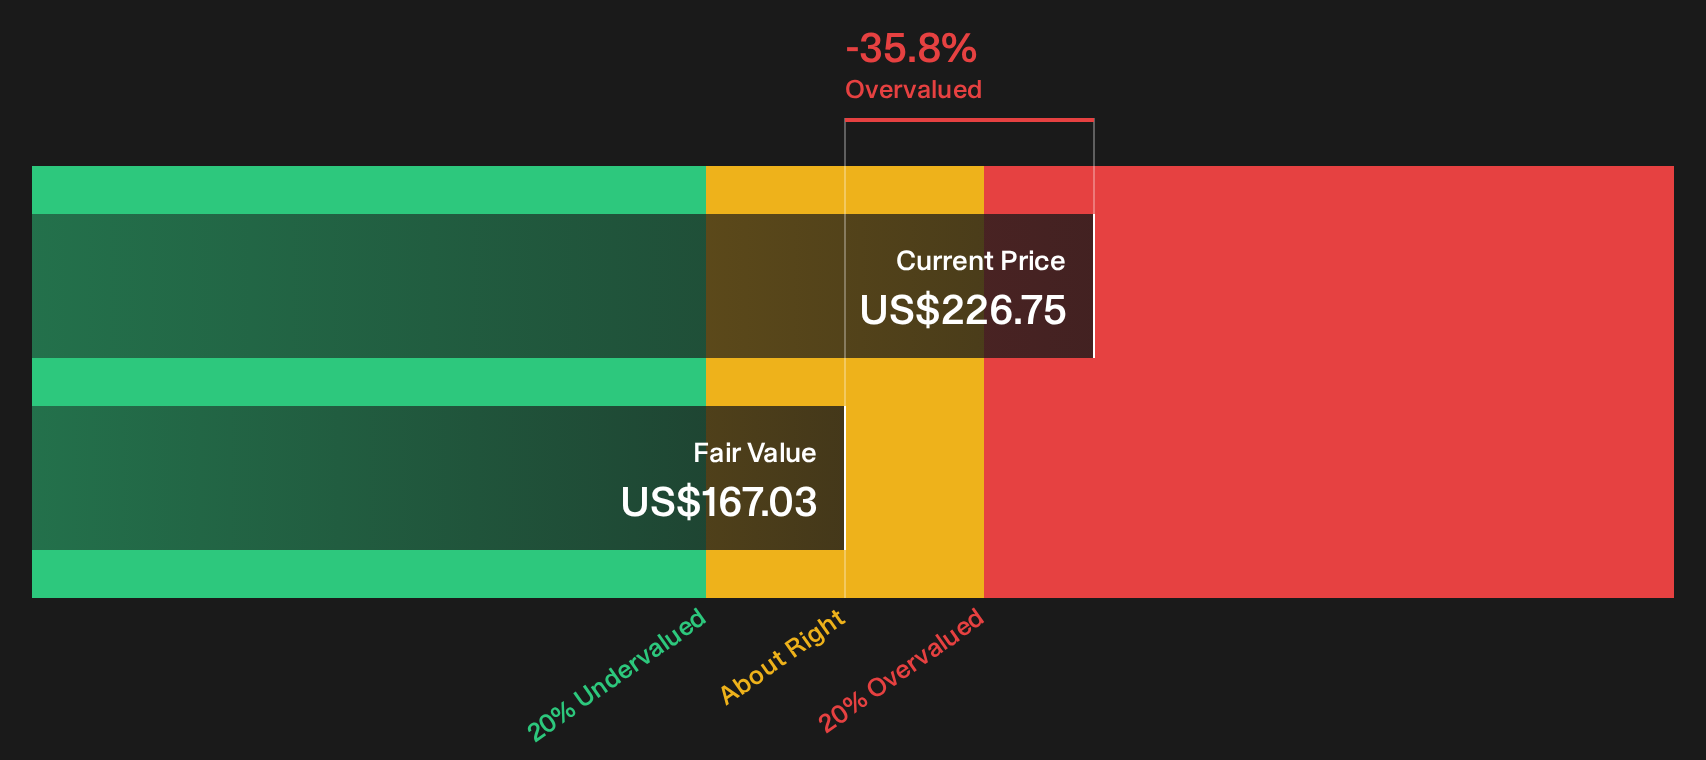
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Arrow Electronics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of optimism and caution around Arrow Electronics still feels unresolved, put the numbers under your own spotlight and move quickly while sentiment is focused. To see what optimistic investors are watching most closely, start with the 4 key rewards.
Looking for more investment ideas beyond Arrow Electronics?
Arrow Electronics might be front of mind today, but your next strong idea could be sitting in another corner of the market. Use focused screeners now, while momentum and liquidity keep opportunities moving so you are not chasing late.
- Target potential upside with companies that pair quality fundamentals with attractive pricing using the 27 high quality undervalued stocks.
- Build a sturdier core to your portfolio by zeroing in on businesses with resilient finances through the 31 resilient stocks with low risk scores.
- Hunt for under followed opportunities that still show solid fundamentals by scanning the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com