
Qualys (QLYS) Could Be 8% Overvalued On Q2 Revenue Beat
Qualys (QLYS) is back in focus after reporting Q2 revenue growth of 11% year on year, topping analyst expectations and reinforcing investor interest in its cloud-based cybersecurity and compliance platform.
The Q2 beat landed on a stock that has already been in an upswing, with a 30-day share price return of 13.82% and a year-to-date share price gain of 47.97% as investors reassess Qualys in light of stronger cloud security demand. That momentum sits alongside a 1-year total shareholder return of 49.38% and a 5-year total shareholder return of 68.60%. Together, these figures point to sentiment that has been building rather than fading.
Scan how Qualys fits alongside other cyber and cloud security plays by reviewing our hand picked list of 92 AI infrastructure stocks in one place.
After a near 50% total return over the past year and a Q2 beat that reset expectations, the puzzle now is simple: Does Qualys still offer an appealing risk reward at this price, or has most of the upside been used already?
Most Popular Narrative: 8% Overvalued
On the most followed narrative, Qualys screens as about 8% above its fair value of $179.36, compared with a last close of $193.86. This view puts more weight on product momentum than on the recent share price run.
Adoption of Qualys' new cloud-native risk operations center (ROC) and Agentic AI platform positions the company as a leading pre-breach risk management provider, offering unified orchestration, automation, and remediation across both Qualys and non-Qualys data; this opens incremental greenfield opportunities and should support higher ARPU and expanded TAM, leading to durable revenue and earnings growth.
See why 48 investors see Qualys as 8% overvalued.
Result: Fair Value of $179.36 (OVERVALUED)
Still, the story can change quickly if AI security shifts faster than Qualys can keep up, or if customers use the new Flex pricing to trim spending rather than expand it.
Find out about the key risks to this Qualys narrative.
Another View: Cash Flows Tell A Different Story
Analysts looking at Qualys through future earnings multiples see the stock as about 8% above the fair value of $179.36. The SWS DCF model paints a different picture. On that framework, QLYS at $193.86 screens as trading below an estimated future cash flow value of $232.07, suggesting investors are paying less for each projected dollar of cash than the first method implies. Which lens do you trust more when both rely on assumptions that can shift with one tough quarter or one strong product cycle?
For a closer look at how this cash flow view is constructed, and how sensitive it is to those underlying assumptions, Look into how the SWS DCF model arrives at its fair value.
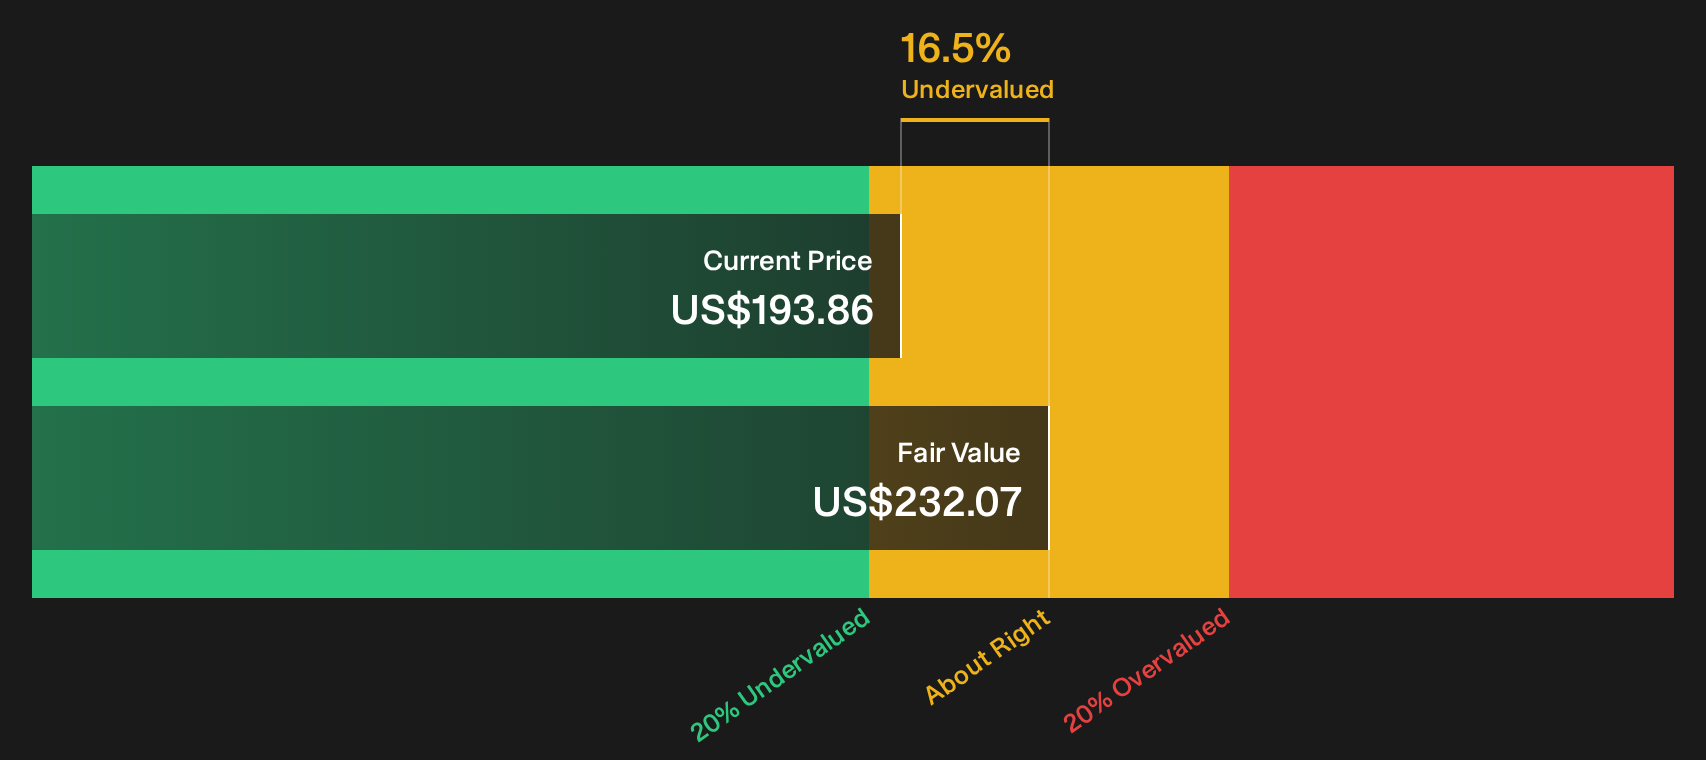
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Qualys for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment around Qualys feels split, do not wait for consensus to harden. Review the numbers for yourself and stress test the upside case that current optimists see in its profile of 3 key rewards
Looking for more Qualys sized investment ideas?
Do not stop with Qualys. Use the Simply Wall Street Screener to spot other opportunities that match your goals before they move without you.
- Target stronger value by scanning companies that combine quality fundamentals with appealing pricing using the 27 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can better handle tougher conditions and financial shocks.
- Hunt for underfollowed potential by checking a 20 high quality undiscovered gems that may not yet be crowded with other investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com