
Is Cosmo (SWX:CMHC) A Bargain Following Its Fireside Event Update?
Cosmo (SWX:CMHC) is back on investor calendars as management prepares to speak at the Jefferies C-Suite Back to School Healthcare Fireside on 5 October 2026, putting its gastro and dermatology pipeline in focus.
Cosmo’s CHF50.2 share price currently sits well below its level at the start of the year, following a series of setbacks that left the 1-year total shareholder return down 24.75%. However, the 3-year total shareholder return of 43.23% points to a stronger earlier period.
Compare Cosmo’s setup with other healthcare and AI-focused opportunities by scanning our hand picked 124 healthcare AI stocks, which are also using real time data and algorithms in patient care.
After a share price that has more than halved year to date, some investors see Cosmo as a value reset, while others worry the best of its 3-year rebound is already in the rearview. How does the current valuation stack up?
Most Popular Narrative: 50% Undervalued
Cosmo’s most followed valuation story points to a fair value of roughly CHF100 per share, almost double the last close at CHF50.2. This comparison puts a spotlight on how much of the gastro, dermatology and AI pipeline investors are currently pricing in.
The report published by the company on March 6 has caused the share price to fall by 20%, due to the forecast of a decrease in revenues by December 2025 in the absence of a commercial agreement for its new products. This makes me cautious and lower the 3-year growth forecast in the absence of more information.
See why 84 investors see Cosmo as 50% undervalued.
According to kapirey, this valuation view leans on a blend of commercial products like GI Genius and Winlevi, a broader late stage pipeline, and a discount rate of 4.19% applied to future cash flows. Taken together, that framework results in a fair value estimate of CHF100 that sits well above both the current share price and the CHF122.62 analyst price target gap implied by the 144.27% discount figure.
Result: Fair Value of CHF100 (UNDERVALUED)
Still, this Cosmo story can break if new licensing deals stall longer than expected or if key late stage trials in hair loss or GI conditions disappoint.
Find out about the key risks to this Cosmo narrative.
Another View: Cosmo Through The P/S Lens
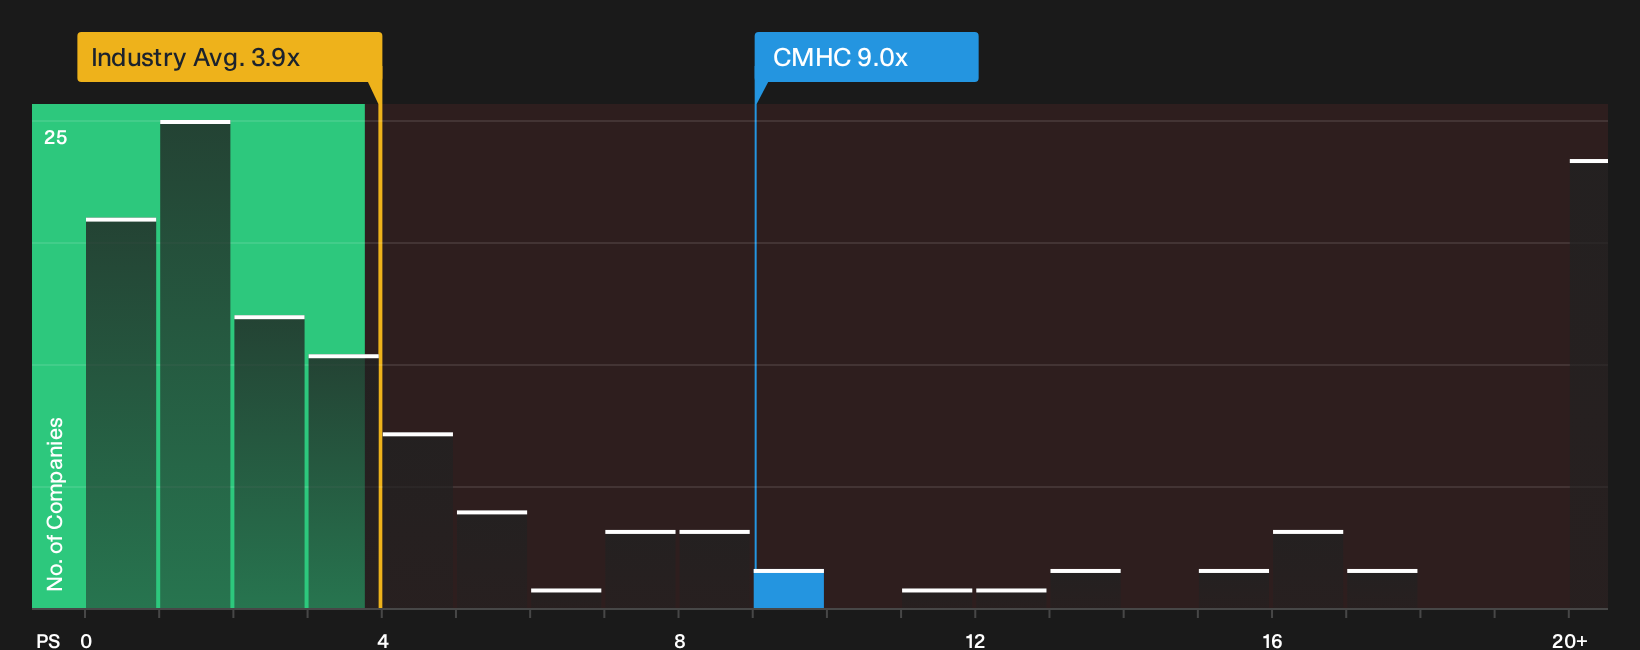
The popular CHF100 fair value story leans on future cash flows, yet the current P/S of about 9x paints a different picture. That multiple is higher than the European pharma average of 4x and also above Cosmo’s own fair ratio of 6.6x. This suggests there is less margin for error if the pipeline underdelivers. Does that premium feel justified to you at this stage?
To see how this price gap looks when broken down against peers and the fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Cosmo’s risk and reward profile make this a stock where you need to check the numbers yourself and be prepared to move quickly if the story changes. To weigh the concerns against the upside potential in one snapshot, review the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Cosmo?
If Cosmo has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist today and give yourself more options tomorrow.
- Target stronger balance sheets by checking the list of solid balance sheet and fundamentals (205 results) that filters for companies with sturdier fundamentals backing their stories.
- Hunt for mispriced opportunities through the 179 high quality undervalued stocks that highlights stocks where quality and price may be out of sync.
- Prioritise resilience and positions that may support better peace of mind with the 225 resilient stocks with low risk scores that focuses on businesses screened for lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com