
Will Applied Partnership Expansion Change Besi Stock Narrative
- Applied Materials and BE Semiconductor Industries expanded their partnership in 2026, adding Besi as an Innovation Partner at Applied’s new EPIC Center to co-develop advanced packaging and interconnect solutions for AI-focused chips across wafer and panel-level workflows.
- The move embeds BE Semiconductor Industries’ assembly expertise directly into Applied’s high budget R&D engine, which could influence product timelines, customer qualification cycles, and the way capital spending on hybrid bonding and related packaging tools is allocated across the supply chain.
- We will now look at how this expanded hybrid bonding collaboration with Applied Materials could influence BE Semiconductor Industries’ investment narrative.
Scan 92 AI infrastructure stocks that, like BE Semiconductor Industries and Applied Materials, are tied directly to the AI build out in advanced packaging and chip interconnects.
BE Semiconductor Industries Investment Narrative Recap
To own BE Semiconductor Industries, you need to believe that its advanced packaging and hybrid bonding business can offset weak mainstream assembly demand and sharp swings in customer orders. The near term swing factor remains how quickly AI centric capacity projects and next generation memory and logic programs translate into firm orders and shipments.
The biggest operational risk is still order volatility from a concentrated set of large U.S. and Asian customers, combined with pressure in mobile and automotive segments that have fallen back toward 2019 levels. The new Applied partnership helps product positioning but does not, by itself, resolve that cyclicality or currency and mix related margin headwinds.
The Applied Materials EPIC Center partnership is the most relevant recent development for that story. It embeds BE Semiconductor Industries engineers into a large, long lived R&D program focused on hybrid bonding, thermo compression bonding and panel level integration, which sit at the center of AI oriented packaging flows for high bandwidth memory and advanced logic.
For shareholders, the operational implications include clearer line of sight to future tool platforms, earlier customer qualification alongside Applied process equipment and a tighter link between R&D spend and real manufacturing recipes. The trade off is higher ongoing development expense and execution risk if pilot programs in 3D IC and photonics interconnects move more slowly than equipment capacity and cost structures are built for.
BE Semiconductor Industries’ current analyst script points to revenues of €1.8b and earnings of €743.0 million by 2029, based on forecast revenue expansion of 35.3% per year and an earnings increase of about €534.3 million from current earnings of €208.7 million.
Uncover why BE Semiconductor Industries' fair value indicates a 61% potential upside to its current price that could narrow quickly.
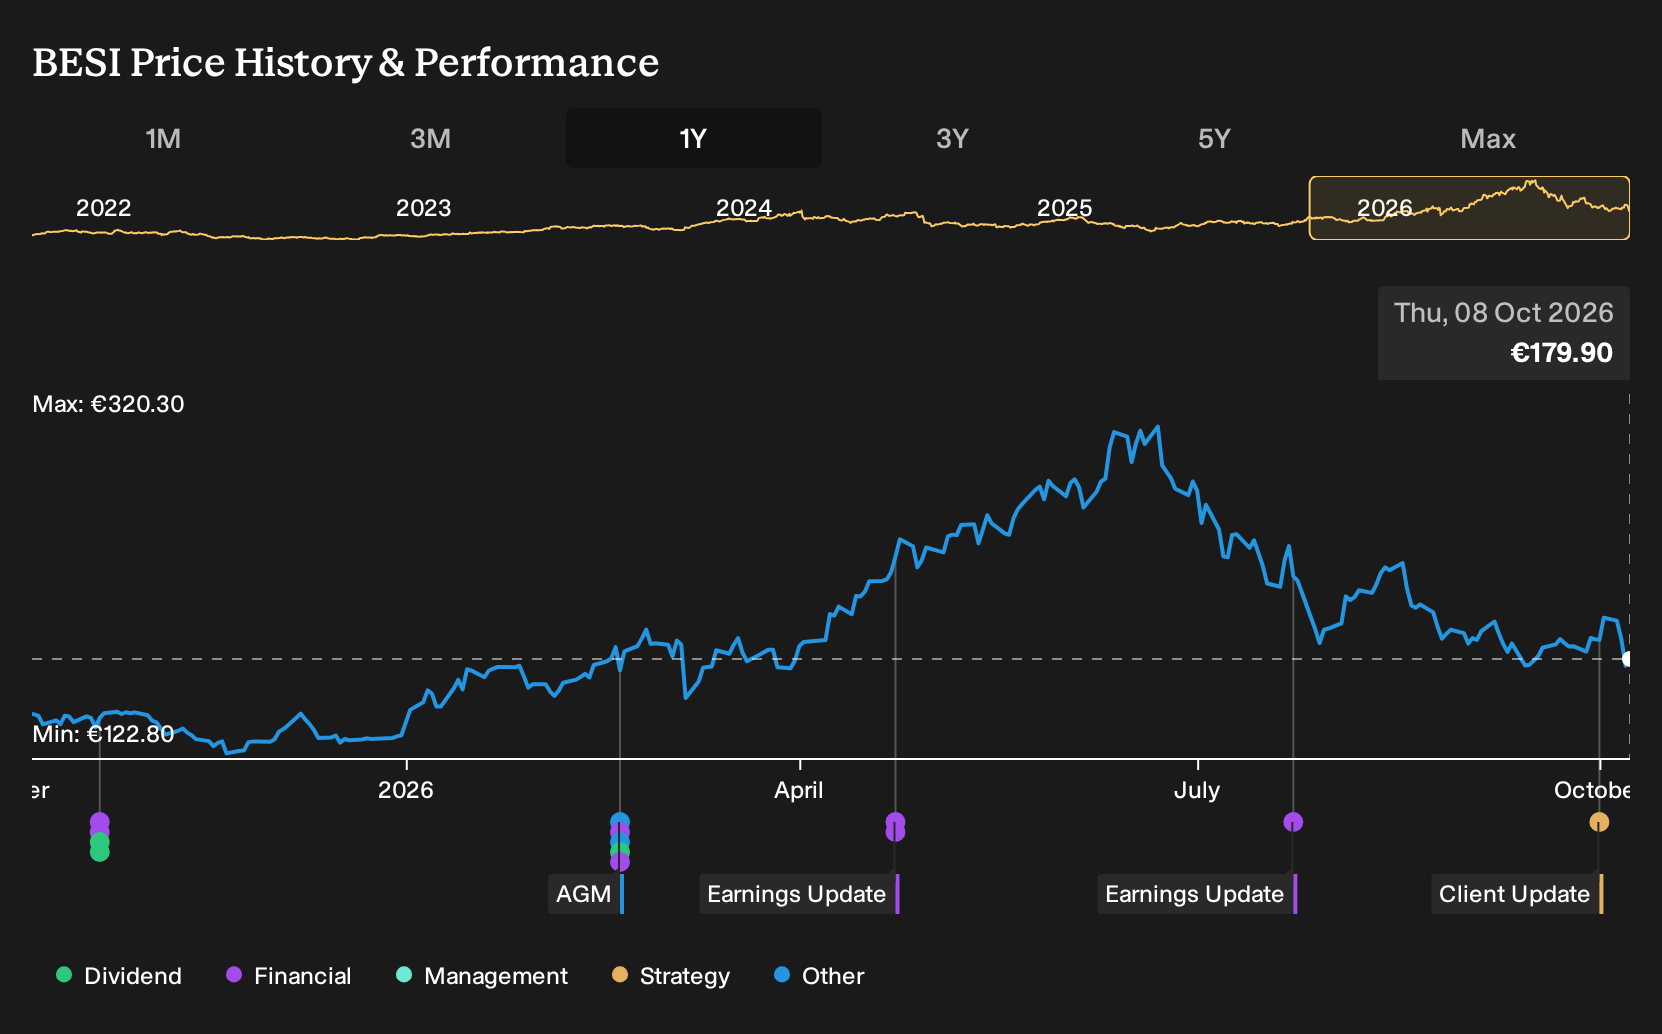
Exploring Other Perspectives
One alternate view focuses squarely on customer concentration risk for BE Semiconductor Industries. The most cautious analysts, who were only looking for about €1.7b of revenue and €682.8 million of earnings by 2029, saw heavy dependence on a few U.S. and Asian clients as a major weak spot. These forecasts came before the EPIC Center partnership news, so you should expect opinions on both risk and opportunity to evolve.
Explore 4 other BE Semiconductor Industries fair value estimates, including one that suggests up to 6% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your BE Semiconductor Industries research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BE Semiconductor Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate BE Semiconductor Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond BE Semiconductor Industries?
If the BE Semiconductor Industries story has you thinking about portfolio balance, it can help to line it up against other companies with very different profiles. The Simply Wall St Screener lets you move from a single stock view to a broader watchlist in a few minutes, so you can compare quality, value and risk side by side.
- For investors who want potential upside without ignoring balance sheet strength, start with a 179 high quality undervalued stocks that combine healthy fundamentals with pricing that may still be catching up.
- If capital preservation and stability matter most to you, filter for steady operators using a 225 resilient stocks with low risk scores that aim to keep volatility in check while still staying in the market.
- When you are hunting for fresher ideas that are not widely discussed yet, scan a 619 high quality undiscovered gems that pair solid business quality with limited existing coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com