
Is Xometry (XMTR) Expensive As Sheet Metal Market Growth Lifts Its Outlook?
The new forecast for the sheet metal fabrication services market, which is expected to expand from $87.3b in 2025 to $136.5b by 2035, puts Xometry (XMTR) in sharper focus for investors today.
Xometry’s recent momentum has been strong, with a 30-day share price return of 15.18% and a year to date share price gain of 69.66%. Total shareholder return over the past year is 105.68%, indicating investors have been steadily repricing the stock as growth expectations and perceived execution improve.
Scan other automation and digital manufacturing players that could also benefit from this sheet metal upswing by reviewing the hand picked 91 robotics and automation stocks alongside Xometry.
After a 69.66% year to date climb and a last close of US$106.48 against an analyst target near US$112, Xometry now trades close to one set of fair value guesses yet above another. Where does that really leave you on valuation?
Most Popular Narrative: 2% Undervalued
On the most followed narrative, Xometry screens as slightly undervalued, with a fair value of about $109.13 versus the last close at $106.48. This leaves the story hinging on how far its marketplace model can scale into higher margins.
The rapid deployment of AI and machine learning across pricing, supplier selection, and workflow automation is substantially improving efficiency, optimizing gross margin, and providing significant operating leverage, positioning the company for margin expansion and improving EBITDA.
See why 10 investors see Xometry as 2% undervalued.
Result: Fair Value of $109.13 (UNDERVALUED)
Still, the Xometry story can break if international expansion drags on profitability or if rising competition in digital manufacturing compresses marketplace take rates.
Find out about the key risks to this Xometry narrative.
Another View: Xometry Looks Expensive On Sales
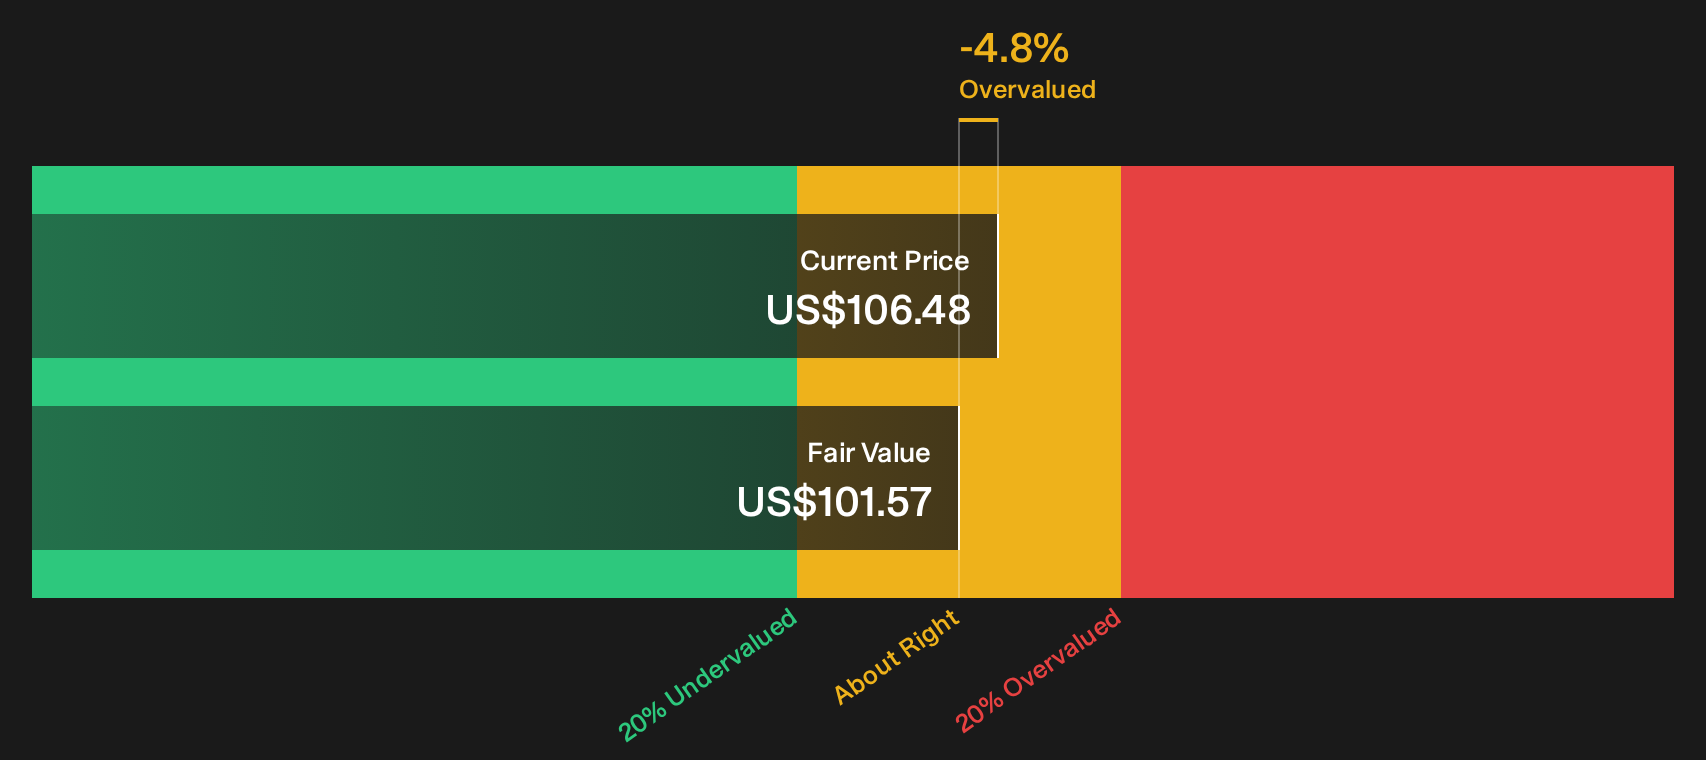
The SWS DCF model points to fair value of about $101.57 per share, which is below Xometry's last close of $106.48. That leaves the stock looking modestly overvalued on future cash flows, even while the popular narrative leans on a small undervaluation. Which story do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Xometry’s value and risk profile make this a moment for your own homework rather than headlines. Act while the data is fresh and weigh both sides of the story with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Xometry?
If Xometry has your attention, do not stop with a single ticker. Broader idea hunting often separates a lucky trade from a durable portfolio.
- Target potential mispricings by scanning companies that pass strict quality and value filters using the 27 high quality undervalued stocks.
- Prioritise resilience by reviewing the list of solid balance sheet and fundamentals (25 results) so your capital leans toward sturdier financial foundations.
- Hunt for under-the-radar opportunities by checking the 20 high quality undiscovered gems before more attention moves the pricing away from you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com