
How Investors May Respond To Sarepta Therapeutics (SRPT) Wider ELEVIDYS Benefit Data
- Sarepta Therapeutics reported new two year ELEVIDYS data in older ambulatory Duchenne muscular dystrophy patients, showing clinically meaningful functional benefits versus well matched external controls, alongside a safety profile in line with prior experience.
- The expanded evidence across 2 to 12 year old ambulant patients strengthens ELEVIDYS as a potential long term pillar of Sarepta Therapeutics Duchenne portfolio. Management uses this to support broader gene therapy and siRNA development.
- This article examines how Sarepta Therapeutics investment narrative is affected by the broader age range ELEVIDYS data in older Duchenne patients.
Scan beyond Sarepta Therapeutics and identify other gene therapy and biotech plays that could experience sharp sentiment swings with trial readouts using our hand picked 20 high quality undiscovered gems.
Sarepta Therapeutics Investment Narrative Recap
To own Sarepta Therapeutics, you need to believe ELEVIDYS can mature into a durable treatment option across a broader Duchenne population while the exon skipping and siRNA franchises keep funding that effort. The fresh two year data in 8 to 12 year old ambulant patients help the story clinically but do not remove the boxed liver warning or the operational friction in getting infusions done.
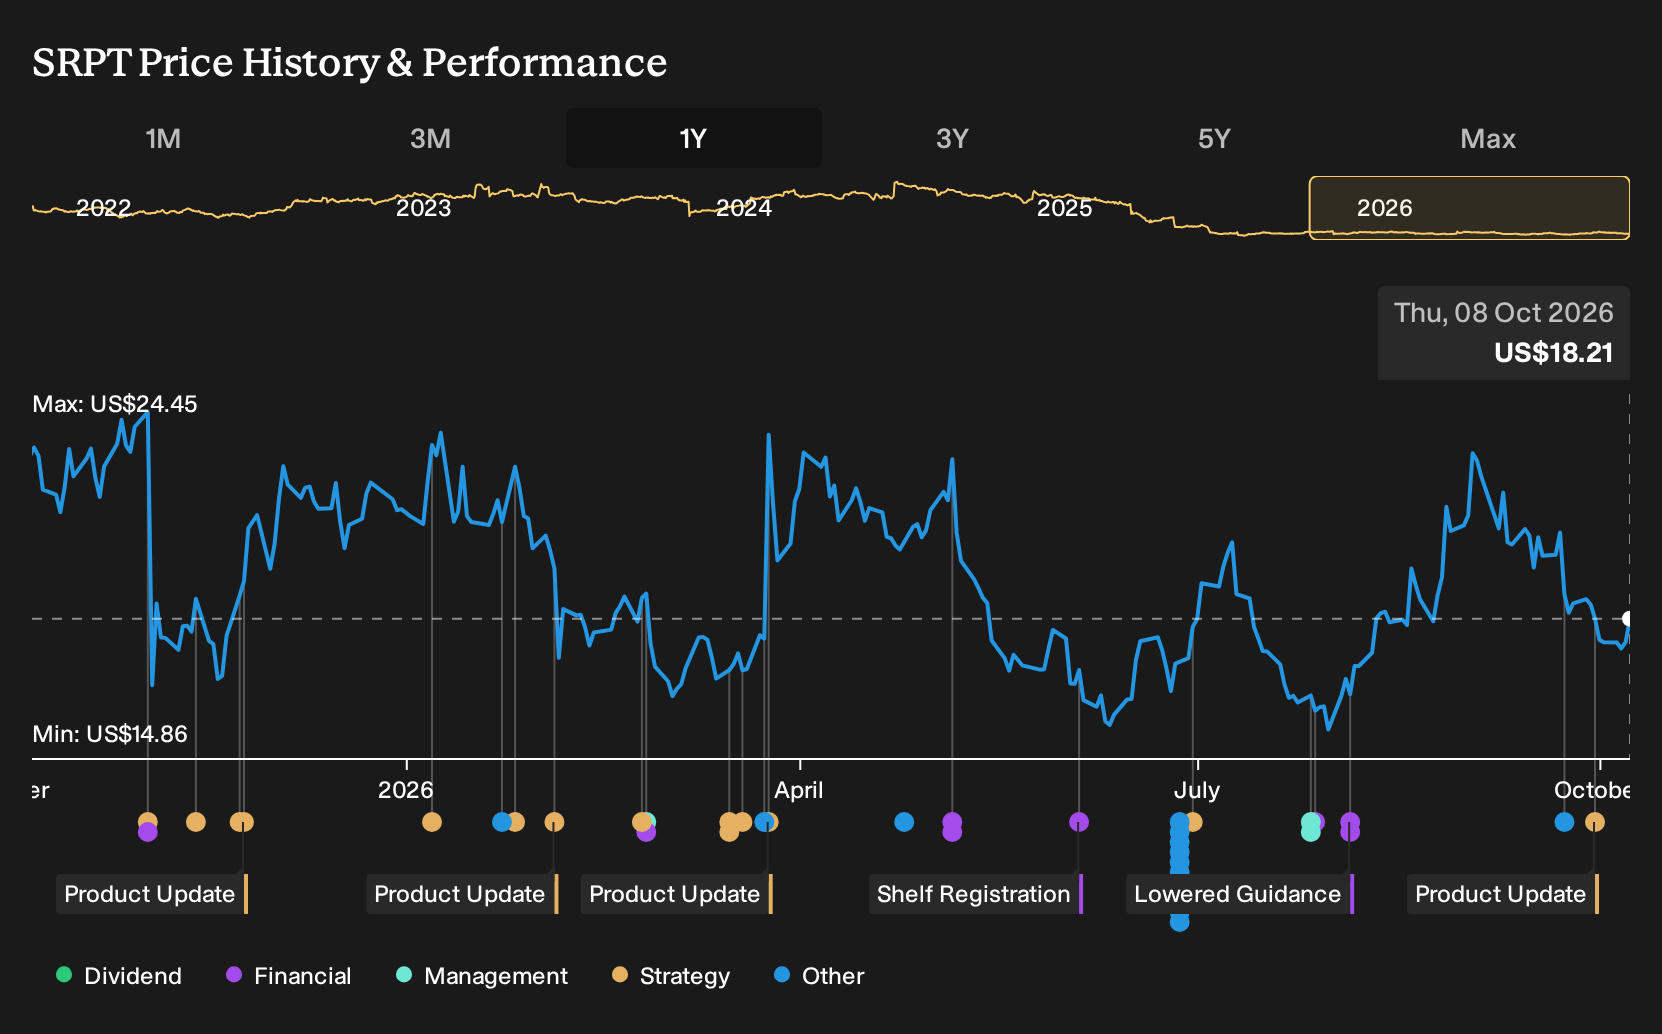
In the near term, the key swing factor remains how effectively Sarepta Therapeutics can convert diagnosed, eligible patients into treated ELEVIDYS cases despite complex administration, site capacity limits, and an expected soft patch in second half 2026 ELEVIDYS revenue. The biggest risk is another serious safety event, which could invite tighter oversight, slower uptake, and pressure on a business already seeing revenue decline and ongoing losses.
The most relevant backdrop for this new ELEVIDYS dataset is management’s ongoing risk management work around the therapy, including sirolimus based prophylaxis in programs such as Endeavor Cohort 8 and the ENDURE study. That effort is aimed at better characterizing liver risk after a prior fatal case and at giving prescribers clearer guardrails.
For you as a shareholder or prospective investor, the combination of expanded functional data in older Duchenne patients and a still cautious safety profile keeps the focus squarely on execution rather than narrative. Progress on safety, smoother site operations, and steady Duchenne cash generation to fund SRP 1001 and SRP 1003 are the operational levers that matter most for Sarepta Therapeutics over the next few years.
Sarepta Therapeutics' outlook projects US$1.3b in revenue and US$36.4 million in earnings by 2029. This scenario assumes a 13.0% annual decline in revenue and an improvement in earnings of about US$173 million from a current loss of US$136.7 million.
Uncover how Sarepta Therapeutics' fair value indicates a 19% potential upside to its current price that could narrow quickly as sentiment shifts.
Exploring Other Perspectives
For Sarepta Therapeutics, the biggest swing factor in the more optimistic narrative is earnings power rather than safety. Before this new ELEVIDYS data, the most bullish analysts were modeling about US$1.4b of revenue and US$159.6 million of earnings by 2029. That contrasts sharply with the broader consensus at US$1.3b and US$36.4 million. As you weigh this fresh clinical update, treat those gaps as a reminder that smart people can disagree widely on where this business heads next, and use them as a prompt to explore several competing viewpoints, not just the headline reaction to the latest trial readout.
Explore 3 other Sarepta Therapeutics fair value estimates, including one that suggests potential upside of up to 911% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sarepta Therapeutics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sarepta Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sarepta Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sarepta Therapeutics?
Once you have a view on Sarepta Therapeutics, it can help to put that opinion in context by scanning a wider set of opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for specific traits so you can build a shortlist that matches your own goals rather than relying on a single story.
- If you want potential upside with strict quality filters, you can focus on financially robust companies by reviewing our 27 high quality undervalued stocks.
- If capital protection matters more to you than chasing every rally, you may consider businesses that screen well on stability and risk controls through our 31 resilient stocks with low risk scores.
- If balance sheet strength is non negotiable for your portfolio, you can start with companies that pair solid finances with consistent fundamentals using this list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com