
Progressive (PGR) Shares Moved, So What Is Driving Attention Now?
Progressive (PGR) is back in focus as investors weigh its push into embedded insurance partnerships, alongside rising attention on the insurer’s upcoming earnings release and what fresh analyst revisions might signal for expectations.
Recent trading has tilted in Progressive’s favor, with a 1-day share price return of 2.15% and a 7-day gain of 3.68% pushing the stock to US$218.73, even though the 90-day share price return declined 5.2% and the 1-year total shareholder return slipped 3.8%.
Scan how Progressive’s embedded insurance push compares with peers taking similar routes in distribution and customer acquisition by reviewing the hand-picked 20 high quality undiscovered gems in the sector.
Bulls point to Progressive’s embedded push and long run of total returns. Bears focus on the recent share price slip and softer net income. Which side does the current valuation lean toward next?
Most Popular Narrative: 5% Undervalued
On the most followed narrative, Progressive screens as modestly undervalued, with a fair value of $231.38 against the latest close at $218.73, which puts more weight on long term earnings power than on the recent share price softness.
The main thing that has to go right is that Progressive continues to translate its long-running investments in analytics, telematics, and AI into underwriting and expense efficiency that offset severity pressure in claims and tighter industry pricing.
The current valuation for a stock this narrative holds to be fairly valued and bearish implies that the market already prices in Progressive’s data and distribution advantages and its capital return record, while assigning meaningful risk to slower policy growth, higher combined ratios, and a more competitive auto market.
See why 73 investors see Progressive as 5% undervalued.
Result: Fair Value of $231.38 (UNDERVALUED)
Still, a more competitive auto pricing backdrop and the 31% drop in June 2026 net income to US$779 million could pressure the Progressive narrative that investors are leaning on.
Find out about the key risks to this Progressive narrative.
Another View: Progressive Through The P/E Lens
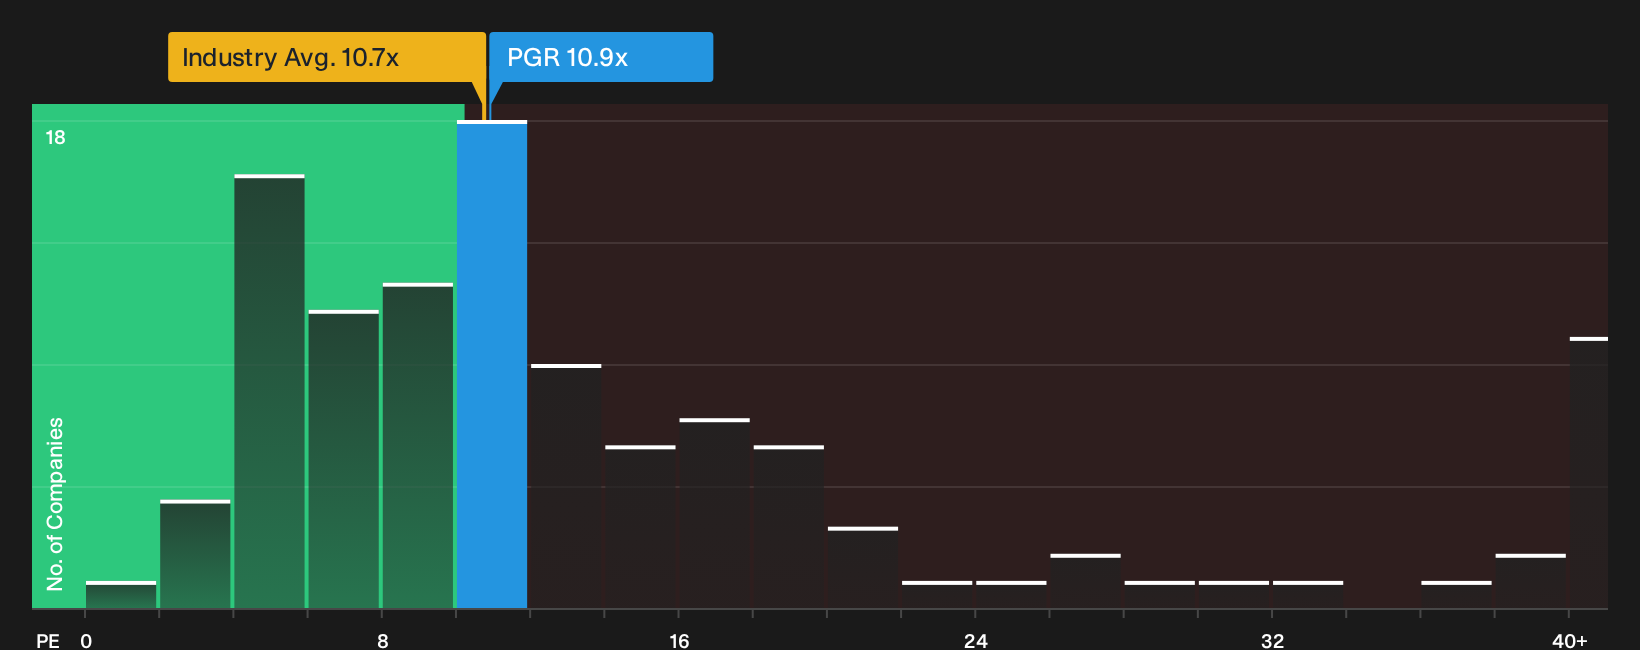
The story looks different once price is compared with earnings. Progressive trades on a P/E of 10.9x, slightly above both the US Insurance industry at 10.7x and the peer group at 8.2x, and a touch higher than its own fair ratio of 10.7x. That premium hints at less margin for error if earnings forecasts soften again.
To see how this earnings based view stacks up against other ways of looking at the stock, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
The Progressive story so far presents mixed messages. Consider the information while it is current and evaluate it for yourself by reviewing the 2 key rewards and 3 important warning signs.
Ready for more ideas beyond Progressive?
If Progressive has sharpened your thinking, do not stop here. Broaden your watchlist and pressure test your thesis using data driven stock ideas built from the ground up.
- Target potential upside with companies that combine quality fundamentals and attractive valuations by scanning the 27 high quality undervalued stocks.
- Prioritize income by reviewing resilient businesses offering higher yields and payout strength through the 8 dividend fortresses.
- Dial down portfolio risk by assessing companies with sturdier finances using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com