
The Growth in Micron Stock Is Being Driven by the ‘Largest Companies in the Land’: Why Wall Street Can’t Get Enough of MU
The associated trade with artificial intelligence (AI), or the “picks and shovels” trade, has created enormous wealth for investors. Not restricted to just one space, the stock rally has spread across numerous domains. The hottest one right now, though, is memory. And Boise, ID-based Micron (MU) is at the front and center of it.
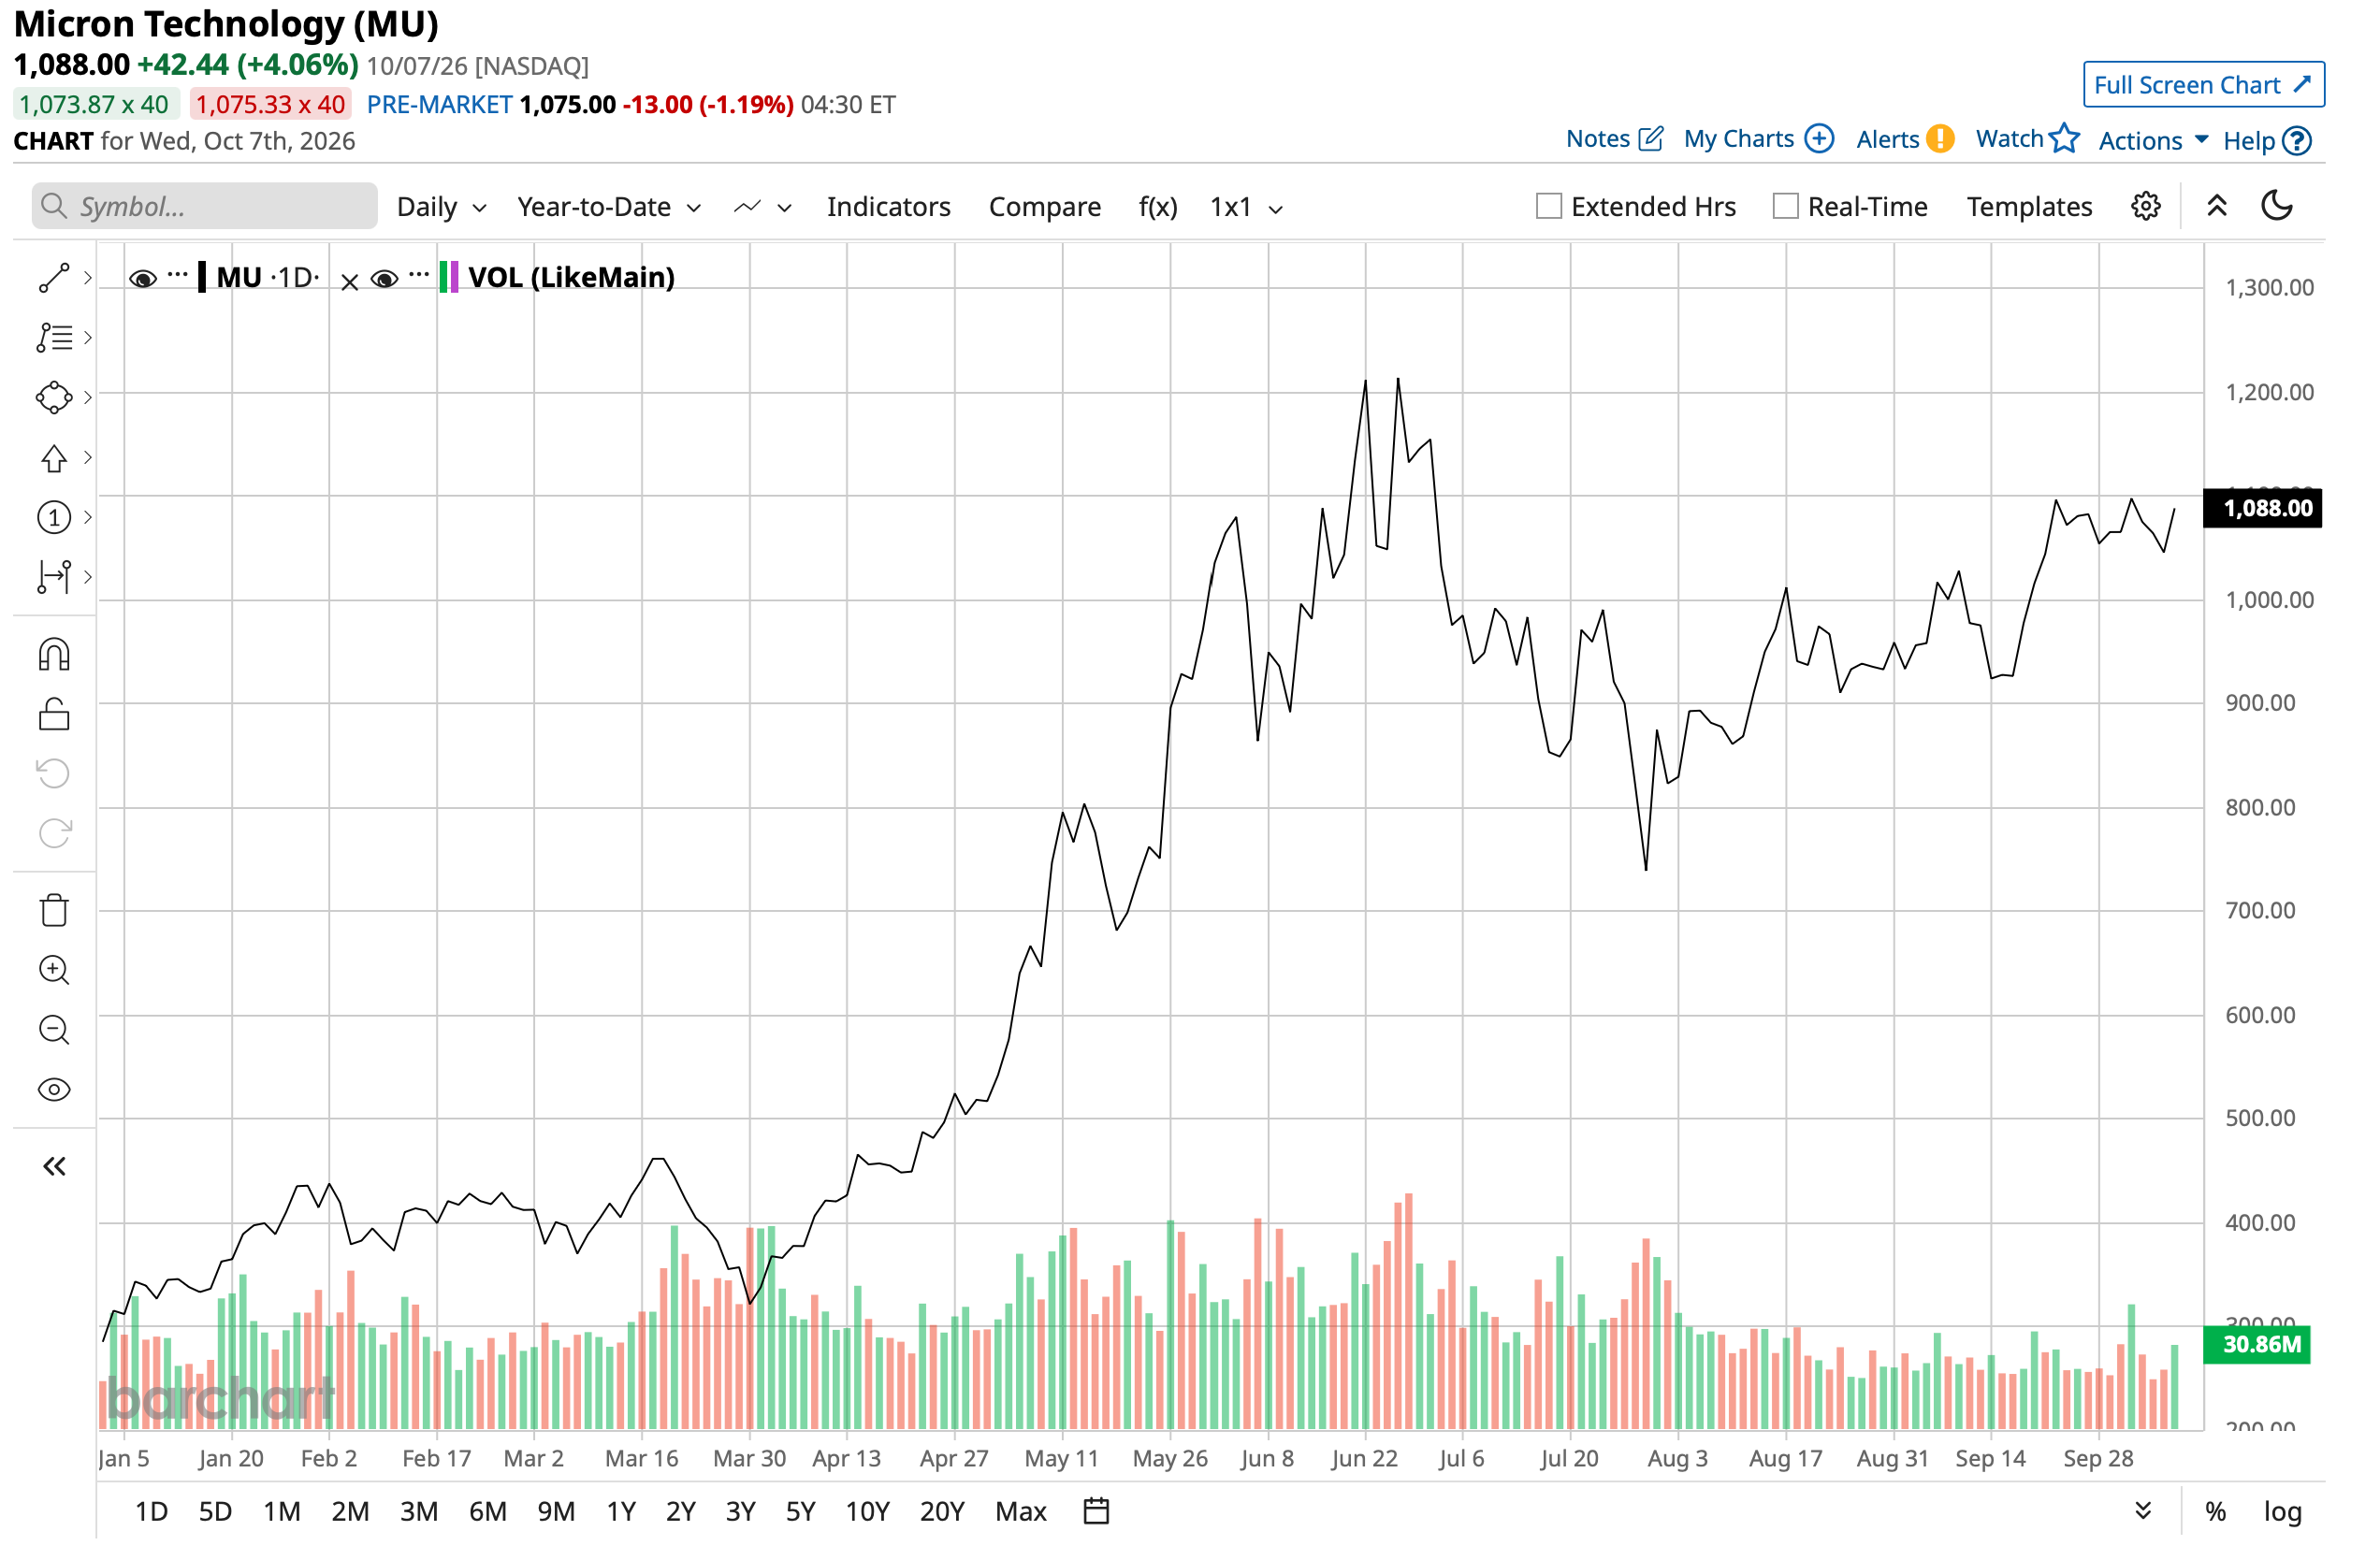
Up a scarcely believable 453.6% over the past year, analysts at D.A. Davidson believe there is more upside left. That prompted the firm to raise its price target on the stock to $3,000 from $2,100, and reiterate its “Buy” rating on it.
Analyst Gill Luria of the firm substantiated their assertions by saying, “Micron is on a growth trajectory for the next 3-5 years, which is what the market has not yet acknowledged. We would also point out that unlike previous cycles, demand is coming from the largest companies in the land like Amazon (AMZN), Microsoft (MSFT), Google (GOOGL), Nvidia (NVDA), and Apple (AAPL), not companies that tend to breach contracts.”
About Micron
Founded in 1978, Micron is fundamentally a memory and storage semiconductor company. Its principal technologies are DRAM, HBM, NAND, NOR, SSDs, and memory modules. It has grown into a global operation with about 15 manufacturing sites, 21 design centers, and 13 customer labs. Notably, it holds 60,000 patents and is the only U.S.-based company developing and manufacturing leading-edge memory.
Micron currently commands a market cap of $1.2 trillion, with its shares up a considerable 281.2% on a YTD basis.
So, as optimism around Micron abounds, amid the latest hike in the target price by a leading broker in the form of D.A. Davidson, what is driving it? Let's have a look.
A Blockbuster Q4
A key factor for the renewed thrust in optimism for Micron stock has been its solid showing in Q4. The company handily beat revenue and earnings expectations, while almost doubling gross margins.
In Q4 2026, Micron reported revenues of $54.3 billion, implying growth of 379.3% from the previous year. The data center unit of the company became the biggest contributor, replacing cloud memory. While the data center business grew by more than 11 times over the course of a year to $18 billion in Q4 2026, the cloud segment revenues jumped by 3.6 times in the same period to come in at $16.3 billion.
Growing revenues were accompanied by sensational margins. The cloud segment had gross margins of 83% (vs 59% in the year-ago period), and the data center unit reported gross margins of 90% (vs 41% in the year-ago period). Overall, company-wide gross margins were at 84.9%, compared to 45.7% in the prior year.
This strength trickled down to the bottom line as the company clocked earnings of $33.42 per share in the quarter. The same was $3.03 per share last year. Notably, the EPS also exceeded the Street expectations of $31.77 per share, marking the 10th consecutive quarter of earnings beats from the company.
For Q1 2027, Micron expects revenues to hover between $60 billion and $63 billion, with earnings forecasted in the range of $37.15-$39.15 per share. Both are above the consensus estimates of $57.02 billion and $35.40 per share for revenue and earnings, respectively.
Capital expenditures may have jumped from $1.38 billion to $27.4 billion, but operating cash flows more than made up for it. For fiscal 2026 ended Sept. 3, Micron's net cash from operating activities was $89.7 billion, up from $17.5 billion in FY 2025. Consequently, free cash flows also soared in the year to $62.3 billion from $3.7 billion in the year-ago period. Overall, the company ended the fiscal year with a cash balance of $38.4 billion, with short-term debt of just $491 million on its books.
Remarkably, even after such an acute rally, Micron continues to trade at undervalued levels. Its forward P/E and P/CF of 5.94 and 5.91, respectively, are below the sector medians of 23.74 and 21.38, respectively. Moreover, at 4.29, the forward P/S of 4.29 is not at a significant premium to the sector median of 3.55.
What's Next?
Micron began high-volume shipments of its 36GB 12-high HBM4 in Q1 calendar 2026. And HBM4E is also underway. Its main announced feature is a custom version being developed with Nvidia for future GPUs and NVLink Fusion platforms. Micron has not published that product’s capacity, bandwidth, or shipment date. Then, there is an enhanced version of the HBM4 called 48GB HBM4 16H. The 16 refers to its stack of 16 memory dies. Micron sent customer samples in 2026, offering 33% more capacity per stack than its 36GB HBM4 with 12 dies. That could let an accelerator keep more model data close to the processor, although Micron has not provided a separate bandwidth figure for the 48GB version.
Rivals Samsung and SK Hynix (SKHY) are making their own moves in the space as well. While SK Hynix has already showcased a 48GB HBM4 stack with 16 layers, Samsung is already shipping samples of a 48GB HBM4E stack with a stated maximum bandwidth of 3.6 TB/s.
New manufacturing nodes are also on the path to progress. Micron says its current 1 gamma DRAM and G9 NAND are its largest production nodes, with successors due to enter volume production in the second half of 2027. Micron credits 1 gamma with over 30% more bits per wafer than its previous DRAM node. However, competition is moving too, as Samsung has sampled HBM4E using its newer 1c DRAM process and has demonstrated NAND with more than 400 layers.
Finally, there is SOCAMM2, Micron's new type of CPU-attached server memory module optimized for AI servers, which uses low-power LPDDR5X rather than conventional DDR5 server memory. The company's 256GB version is sampling and can provide 2TB across eight modules. Also, its 192GB version is already in volume production.
Analyst Opinion On MU Stock
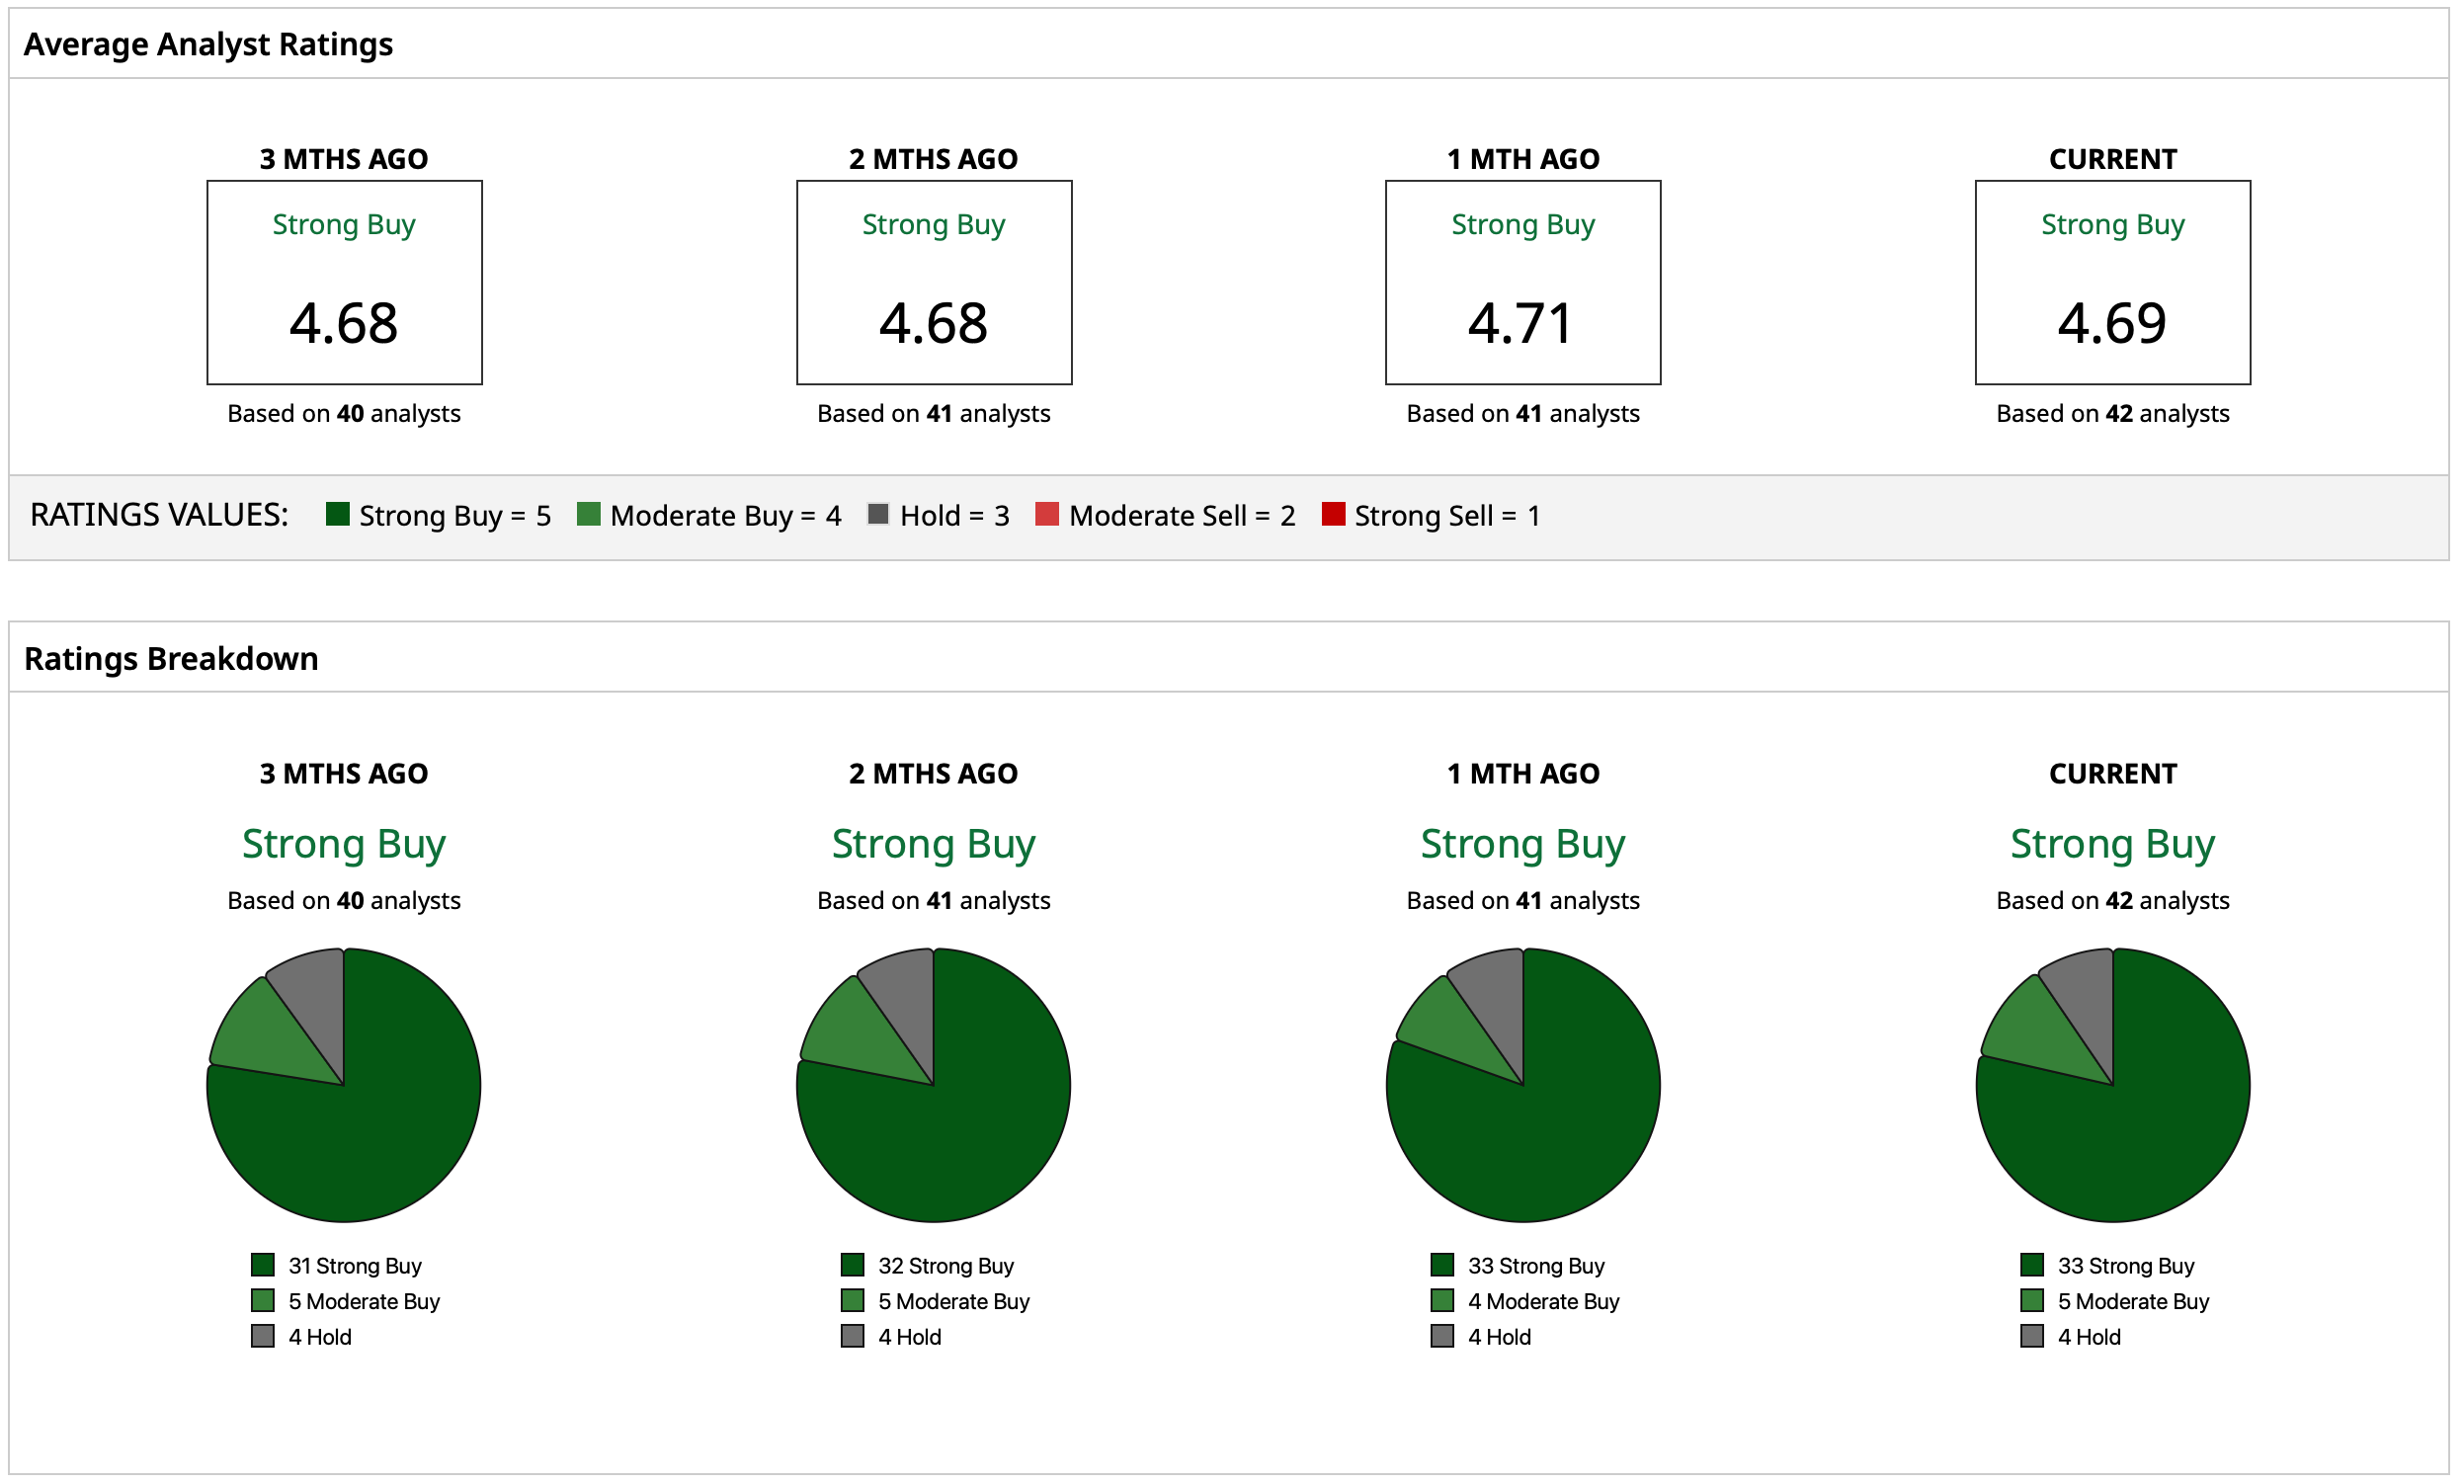
Taking all of this into account, analysts have deemed MU stock to be a “Strong Buy”, with a mean target price of $1,537.51. This implies a potential upside of 41.3% from current levels. Out of 42 analysts covering the stock, 33 have a “Strong Buy” rating, five have a “Moderate Buy” rating, and four have a “Hold” rating.
On the date of publication, Pathikrit Bose did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.