
Analysts Expect Breakeven For Capricor Therapeutics, Inc. (NASDAQ:CAPR) Before Long
We feel now is a pretty good time to analyse Capricor Therapeutics, Inc.'s (NASDAQ:CAPR) business as it appears the company may be on the cusp of a considerable accomplishment. Capricor Therapeutics, Inc., a clinical-stage biotechnology company, engages in the development of transformative cell and exosome-based therapeutics for treating duchenne muscular dystrophy (DMD) and other diseases with unmet medical needs in the United States. The company’s loss has recently broadened since it announced a US$105m loss in the full financial year, compared to the latest trailing-twelve-month loss of US$129m, moving it further away from breakeven. Many investors are wondering about the rate at which Capricor Therapeutics will turn a profit, with the big question being “when will the company breakeven?” We've put together a brief outline of industry analyst expectations for the company, its year of breakeven and its implied growth rate.
According to the 10 industry analysts covering Capricor Therapeutics, the consensus is that breakeven is near. They anticipate the company to incur a final loss in 2027, before generating positive profits of US$7.7m in 2028. The company is therefore projected to breakeven around 2 years from now. How fast will the company have to grow each year in order to reach the breakeven point by 2028? Working backwards from analyst estimates, it turns out that they expect the company to grow 67% year-on-year, on average, which signals high confidence from analysts. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
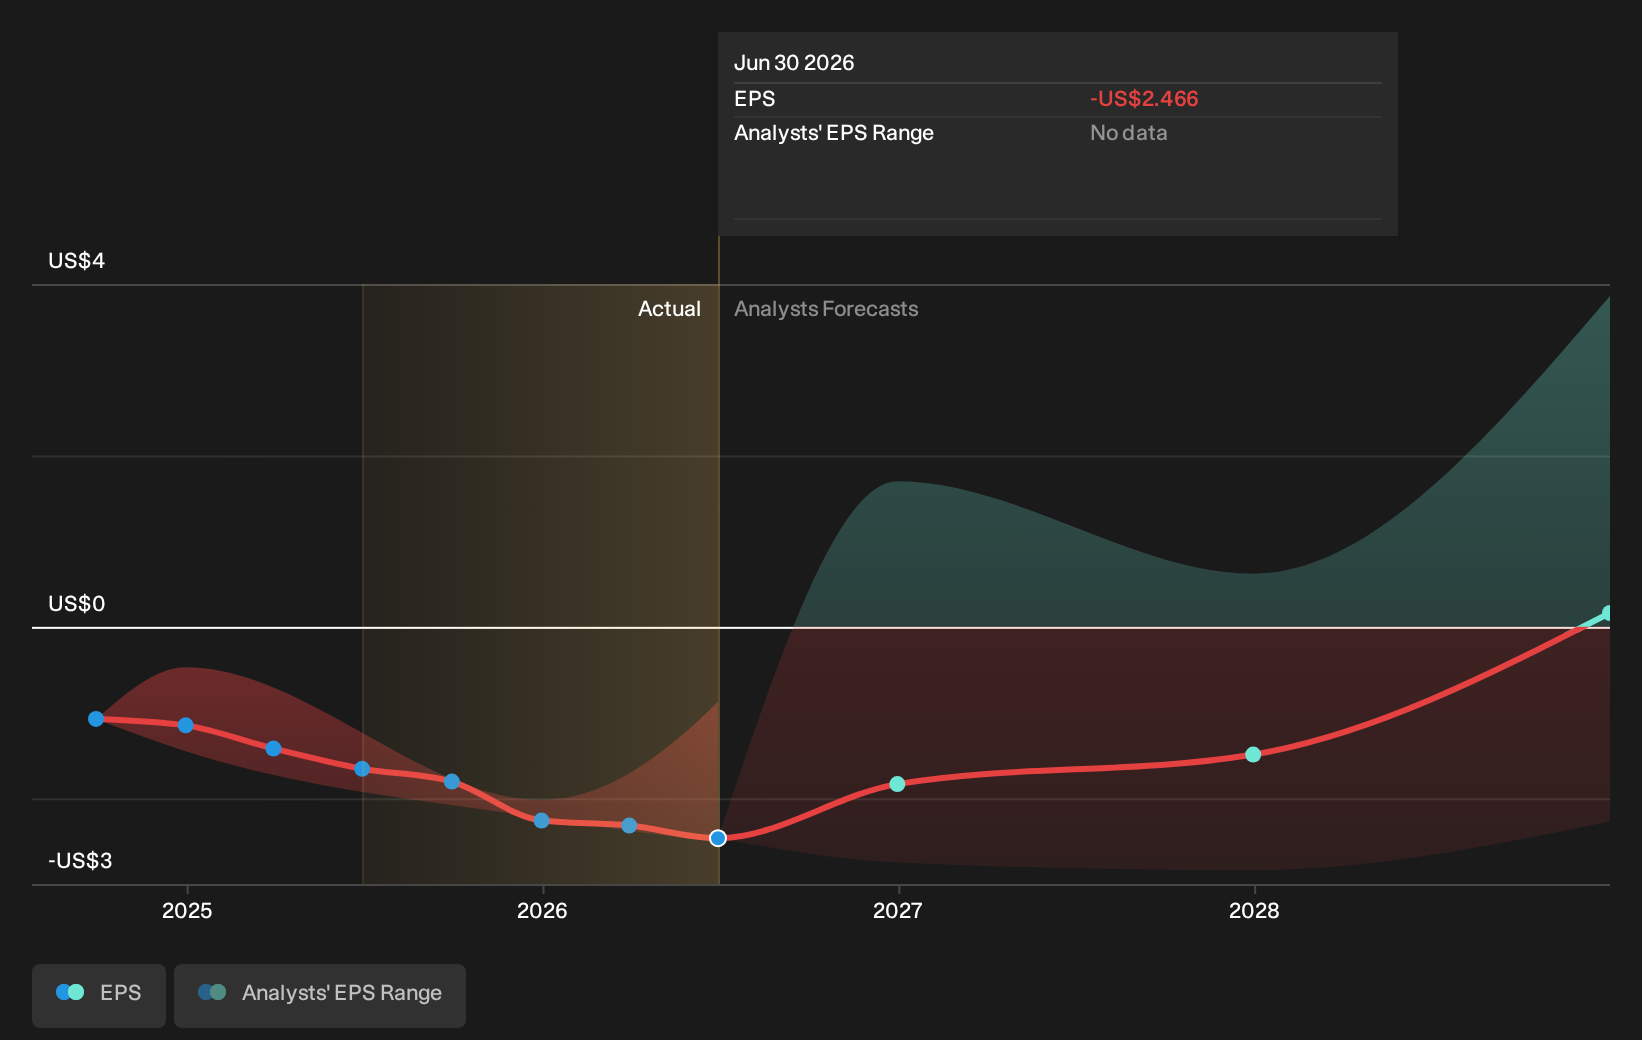
We're not going to go through company-specific developments for Capricor Therapeutics given that this is a high-level summary, though, bear in mind that by and large a biotech has lumpy cash flows which are contingent on the product type and stage of development the company is in. So, a high growth rate is not out of the ordinary, particularly when a company is in a period of investment.
See our latest analysis for Capricor Therapeutics
Before we wrap up, there’s one aspect worth mentioning. Capricor Therapeutics currently has no debt on its balance sheet, which is quite unusual for a cash-burning biotech, which typically has high debt relative to its equity. The company currently operates purely off its shareholder funding and has no debt obligation, reducing concerns around repayments and making it a less risky investment.
Next Steps:
This article is not intended to be a comprehensive analysis on Capricor Therapeutics, so if you are interested in understanding the company at a deeper level, take a look at Capricor Therapeutics' company page on Simply Wall St. We've also compiled a list of pertinent aspects you should further examine:
- Valuation: What is Capricor Therapeutics worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether Capricor Therapeutics is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Capricor Therapeutics’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.