
Karat Packaging (KRT) Beat Expectations, Is The Stock Already Fully Valued?
Karat Packaging (KRT) drew fresh investor attention after reporting quarterly revenue of $136.3 million, an increase of 9.9% year on year, with earnings and EBITDA both ahead of Wall Street forecasts.
Investors have responded quickly to the strong report, with Karat Packaging’s share price up 11.29% over the past month and 57.40% over 90 days. The 1-year total shareholder return of 139.96% indicates strong recent share performance rather than a short-lived earnings reaction.
Scan beyond Karat Packaging’s breakout quarter and line up other potential movers with the hand picked 27 high quality undervalued stocks that combine solid cash generation with balance sheet strength.
The question now is simple. After Karat Packaging’s rapid rerating on strong results, do you lean into the momentum today, or wait and hope the valuation offers a cleaner entry soon?
Most Popular Narrative: 16% Overvalued
Karat Packaging last closed at $53.80 compared with a widely followed narrative fair value of $46.50, so the story centers on whether expectations have run ahead of the fundamentals that analysts are modelling with an 8.31% discount rate.
The current valuation implies that Karat Packaging’s share price already reflects expectations of sustained double digit online growth, continued eco-friendly mix gains and effective use of tariff refunds and capital returns. This makes the stock appear fully valued on this narrative’s view.
See why 12 investors see Karat Packaging as 16% overvalued.
Result: Fair Value of $46.50 (OVERVALUED)
Still, if Karat Packaging’s eco-friendly mix continues to gain traction and online revenue moves toward the US$100 million mark, that could challenge this overvaluation story.
Find out about the key risks to this Karat Packaging narrative.
Another View: Karat Packaging Through A Cash Flow Lens
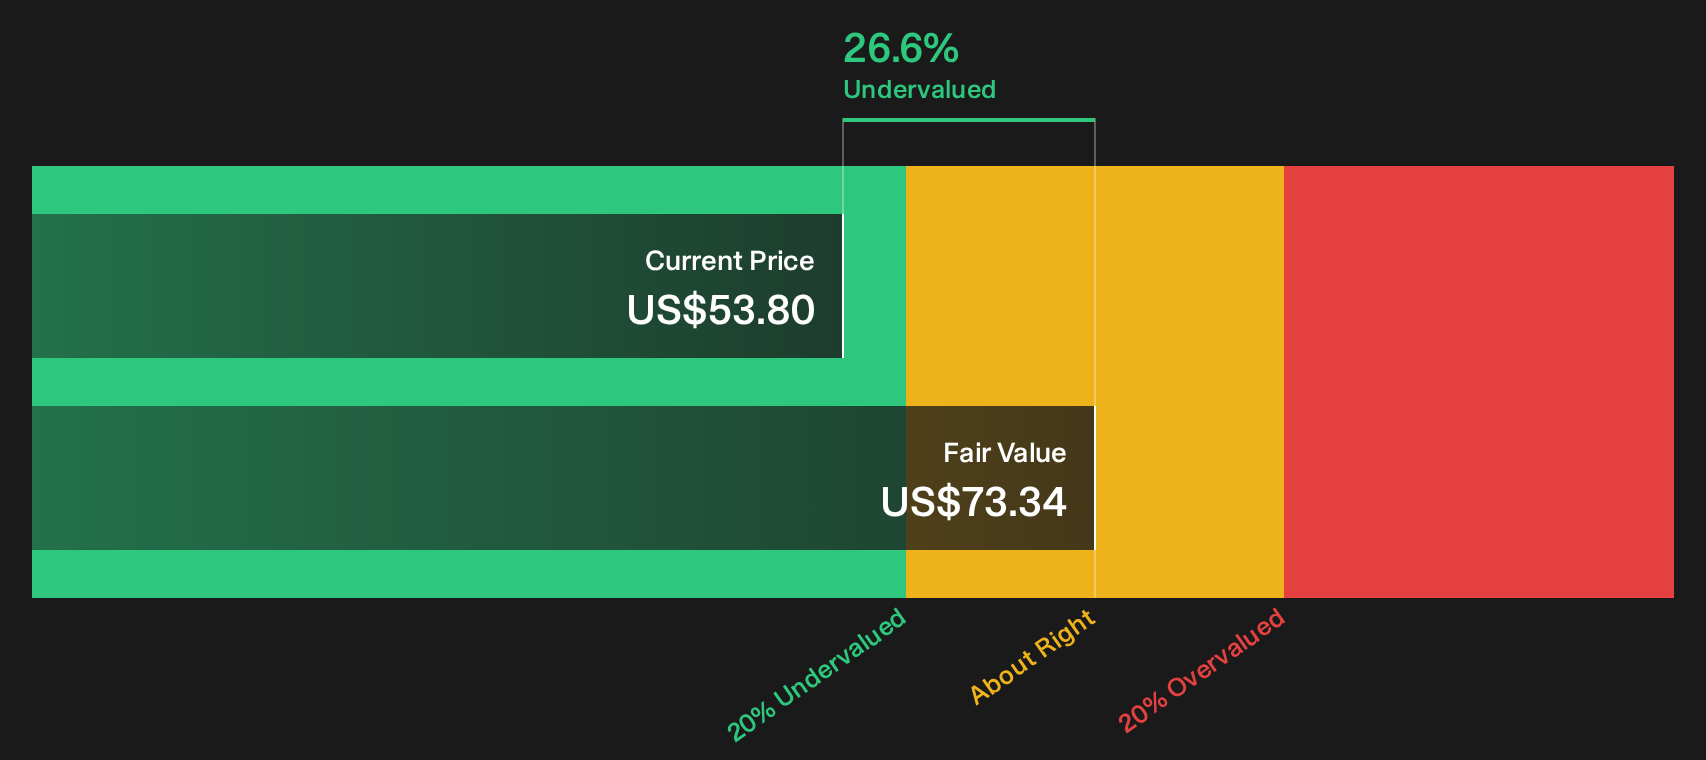
The first story around Karat Packaging focuses on analyst price targets and earnings-based fair value. A different lens using the SWS DCF model values the stock at $73.34 per share, compared with the current $53.80 price, which points to it being undervalued on projected cash flows.
That wide gap between the current quotation and the DCF output raises a simple question for any investor following KRT. Do you give more weight to near term earnings expectations and multiples, or to the longer term cash generation profile that our DCF model is capturing here, and how do you test which one fits your own view of the business.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Karat Packaging for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Karat Packaging feels familiar, move quickly to conduct your own research and evaluate the story using the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Karat Packaging?
Do not stop with Karat Packaging. Use this earnings move as your cue to widen the opportunity set and evaluate where your next dollar should really go.
- Target income resilience by scanning for companies with consistent payouts and yields that clear a meaningful hurdle using the 8 dividend fortresses.
- Hunt for sturdier balance sheets and cleaner financial foundations with the list of solid balance sheet and fundamentals (25 results) before market stress exposes weak capital structures.
- Spot potential future leaders early by filtering for 20 high quality undiscovered gems that pair solid fundamentals with limited current attention from the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com