
Ultragenyx (RARE) Stock Looks About Right After Voucher Sale
Ultragenyx Pharmaceutical has had a rough stretch for long term shareholders, yet a fresh cash injection from a rare disease voucher sale has refocused attention on what you are really paying for today: its sales. With the share price trying to find a footing, the live question is how that market value lines up against the revenue the business is generating right now.
- Over the past 5 years, Ultragenyx Pharmaceutical shares have fallen 81.1%, which puts extra weight on whether the current valuation still matches what the company is producing in sales.
- The US$210 million sale of a Rare Pediatric Disease Priority Review Voucher brings in non dilutive capital that can support funding for rare disease therapies and may influence how investors think about future revenue and the timing of potential profitability.
- There is a second opinion on Ultragenyx Pharmaceutical worth weighing. See what analysts think Ultragenyx Pharmaceutical's shares could be worth.
The issue now is whether the current price of Ultragenyx Pharmaceutical stock is justified by the level and trajectory of its sales.
If you want more context around Ultragenyx Pharmaceutical's focus on revenue and capital efficiency, it can help to compare it with other businesses in our 27 high quality undervalued stocks
Is Ultragenyx Pharmaceutical Fairly Priced on Sales?
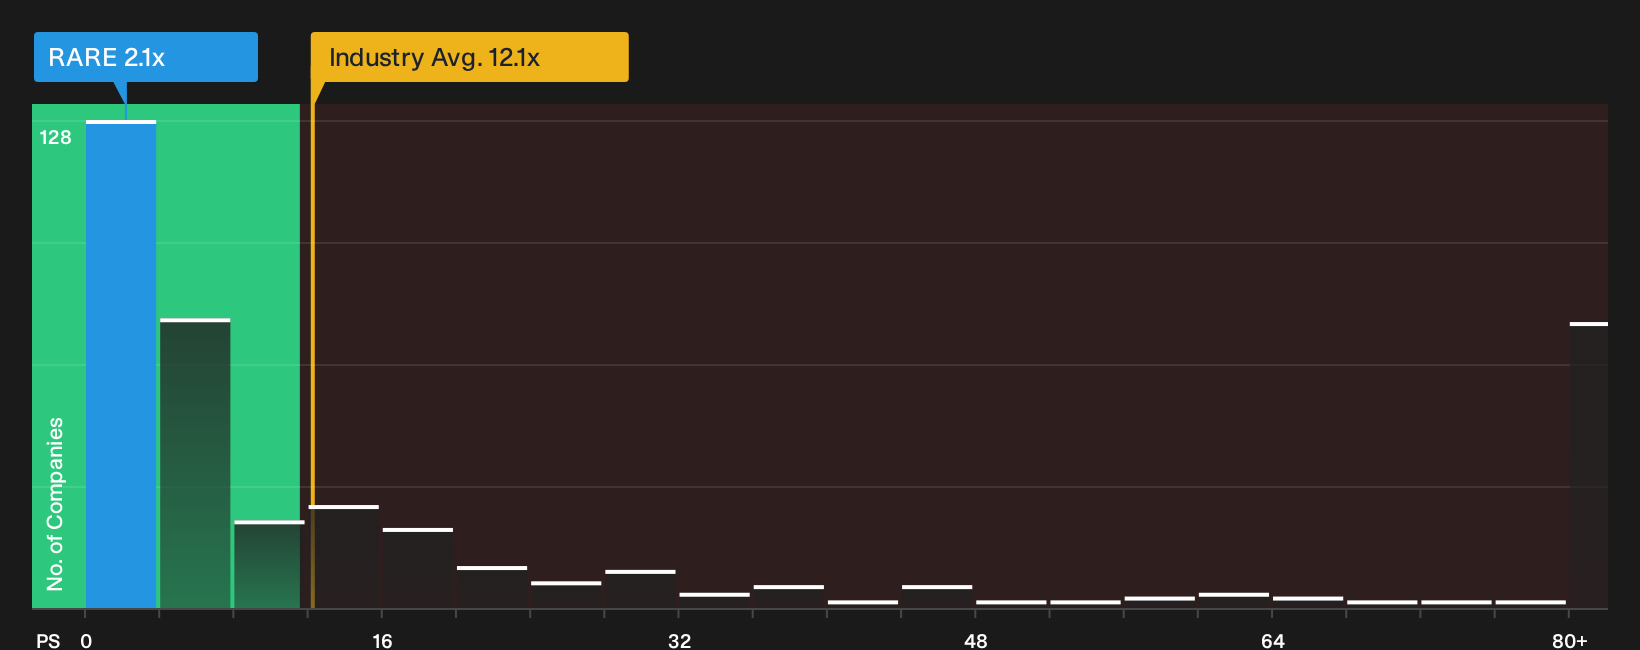
P/S suits Ultragenyx Pharmaceutical because the business is still loss making and investors are effectively paying for revenue rather than current earnings. On this lens, the stock trades on a P/S of 2.1x, compared with about 12.1x for the wider Biotechs industry and roughly 9.2x for closer peers, so the revenue multiple screens far lower than many similar developers.
That gap looks less extreme once you compare it with a tailored fair P/S level that blends the company’s growth profile, margins, scale and risk, where Ultragenyx Pharmaceutical now sits close to that implied mark. Because the recent US$210 million voucher sale brings in cash without adding to share count, the current P/S of 2.1x still leaves the market assigning a relatively undemanding value to existing sales while waiting for the rare disease pipeline to convert more meaningfully into revenue. Explore the numbers behind Ultragenyx Pharmaceutical's P/S valuation.
The Ultragenyx Pharmaceutical Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Ultragenyx Pharmaceutical's valuation puzzle leaves off and explain which combinations of future growth, margins and earnings would need to occur for the current share price to appear either stretched or conservative. Each scenario links its figures to a clear view on how Ultragenyx Pharmaceutical's revenue mix, profitability path and risk profile could change, providing reference points you can revisit as new information emerges.
One of the top community narratives on Ultragenyx Pharmaceutical: 41% undervalued
"The SG&A required to hunt for rare disease patients is cannibalizing top-line gains..."
Discover why this Narrative puts Ultragenyx Pharmaceutical at 41% undervalued.
Ultragenyx Pharmaceutical’s next question is who is steering the ship
Sales multiples only tell part of the story, because the people choosing how to spend each new dollar and how they are rewarded for those choices can tilt outcomes in very different directions. See who runs Ultragenyx Pharmaceutical and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com