
Cintas (CTAS) Lifts Guidance On Record Margins As Valuation Questions Grow
Cintas (CTAS) drew fresh attention after management raised fiscal 2027 earnings guidance on the back of record operating margins, reinforcing investor interest in how its workplace services model and technology investments support that outlook.
Recent action has been upbeat. Cintas shares have a 90 day share price return of 11.96% and a year to date share price gain of 8.78%, alongside a 5 year total shareholder return of 102.42%. This suggests momentum has been building as investors react to stronger guidance and ongoing efficiency gains.
Scan for other Cintas style compounders turning pricing power and efficiency into steady momentum by reviewing our curated list of 20 high quality undiscovered gems in similar service driven niches.
Cintas looks like a high quality compounding machine after its guidance bump and margin strength. The harder question is whether that story is already fully reflected in the current share price.
Most Popular Narrative: 9.8% Overvalued
Cintas closed at $201.12 against a widely followed fair value estimate of $183.22, so the current price sits meaningfully above that narrative anchor. For anyone tracking the raised guidance, the key question is how much of that operating momentum is already baked into this valuation gap.
The caveat that once belonged to margins now covers growth.
The earlier call applied “running a business isn’t linear” to gross margin: “We don’t expect that it’s going to just continuously rise.” The current call applies it to the top line, after organic growth of 8.9%. Rental is “comfortable with that moving a little bit in our stated range of mid to high single digits,” and company growth “does not just continue to go up in perpetuity.” Rozakis recites four quarters of last year’s rental growth, 7.3%, 7.8%, 7.3%, 7.9%, to define the band, and all four sit below the current 8%. Variability is being announced in advance, and the examples chosen for it point one way. (Moderate)
See why 2 investors see Cintas as 10% overvalued.
Result: Fair Value of $183.22 (OVERVALUED)
Still, the Cintas narrative leans on management credibility and workday adjustments, so any guidance walk back or UniFirst delay could quickly challenge that 9.8% overvaluation story.
Find out about the key risks to this Cintas narrative.
Another View: Cintas Through A Cash Flow Lens
The fair value story shifts once the SWS DCF model enters the frame. On that measure, Cintas at $201.12 is below an estimated future cash flow value of $212.14, which points to the stock trading at a discount instead of the 9.8% premium implied by the narrative anchor. That kind of split leaves investors deciding which lens feels more convincing.
For readers who want to see how that cash flow outcome is built line by line, and what has to hold true for it to remain valid, Look into how the SWS DCF model arrives at its fair value..
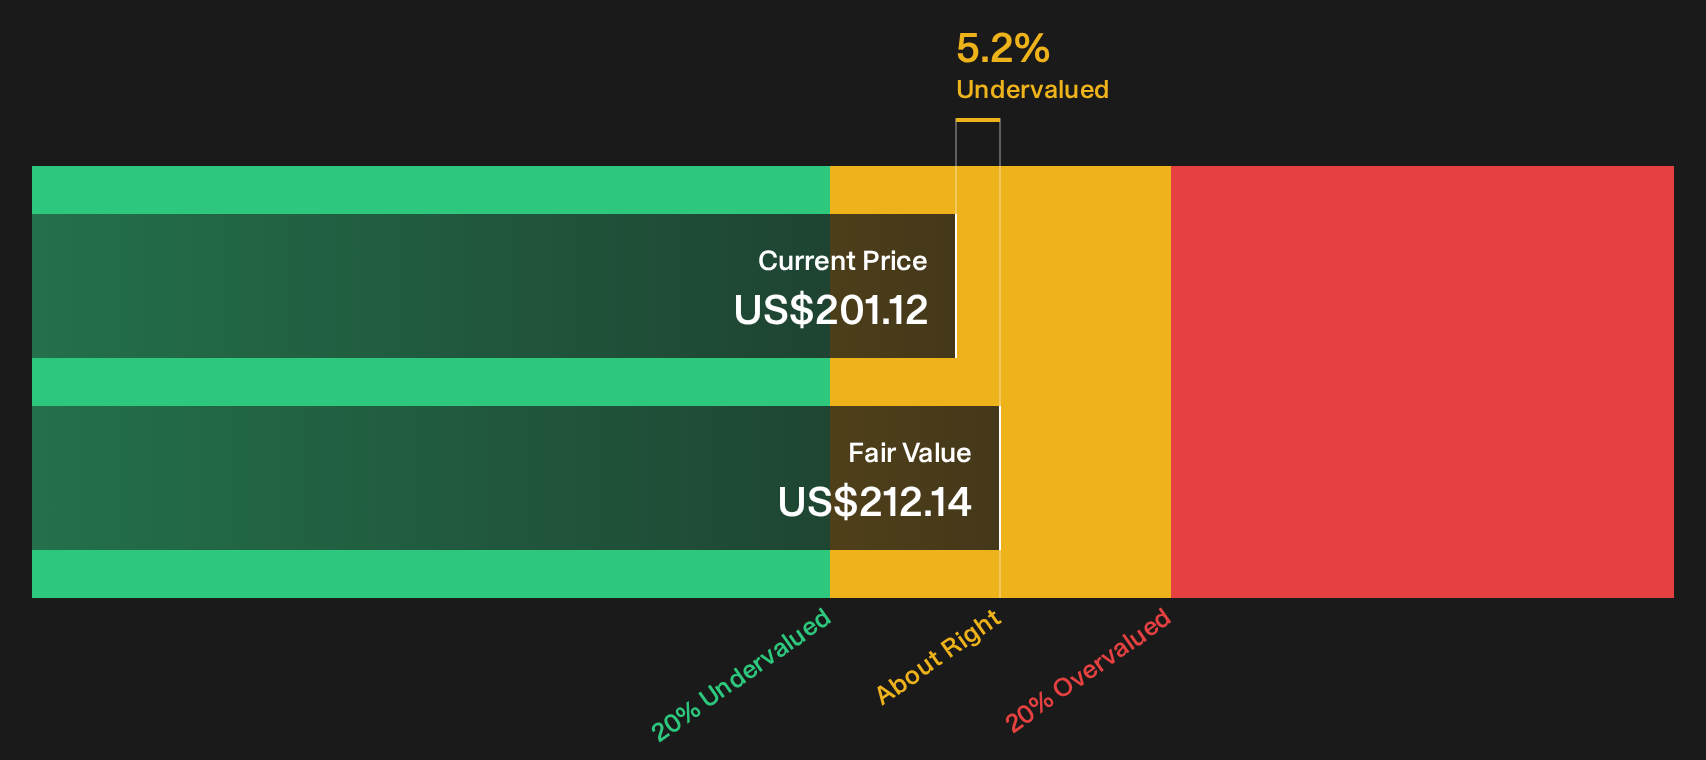
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cintas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Cintas in this piece skews cautious, so treat it as a prompt to stress test the numbers yourself and move fast while the data is fresh. To see what optimistic investors are focusing on, start with the 3 key rewards.
Looking for more investment ideas beyond Cintas?
If Cintas has sharpened your focus on quality and pricing power, you can use that same lens to look for other businesses that might play a role in reshaping your portfolio’s next leg higher.
- Target dependable compounding potential by scanning a curated set of high quality value opportunities through the 27 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can handle surprises and help keep optionality intact.
- Look for potential standouts early by combing through our 20 high quality undiscovered gems before they appear on every investor’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com