
Will Earnings Beats Change Affiliated Managers Group (AMG) Stock Narrative
- Affiliated Managers Group recently reported a series of earnings results that surpassed market estimates, with positive Earnings ESP indicators aligning with an existing favorable analyst rating.
- The company’s earnings strength is accompanied by a 4.5% upward move in full year earnings estimates over three months, as well as relative outperformance versus both the broader Finance sector and its Investment Management peers.
- We will now look at how Affiliated Managers Group's recurring earnings beats might reshape the existing affiliate focused investment narrative.
Scan other Affiliated Managers Group style outperformers in finance by reviewing our hand picked list of 20 high quality undiscovered gems, which have been quietly outpacing their sectors.
Affiliated Managers Group Investment Narrative Recap
To own Affiliated Managers Group, you have to believe the affiliate model in alternatives and quantitative strategies can keep offsetting pressure in traditional active equity. The near term story is about execution inside existing affiliates and about how consistently they can translate fee based assets into cash generation without relying on one off items.
The recent pattern of earnings beats and estimate revisions mainly sharpens attention on flows and fee stability. It supports the idea that current operations are holding up, but it does not remove key risks such as concentrated earnings in Pantheon and AQR or the reliance on new affiliate deals and buybacks to support economic EPS per share metrics.
The most relevant piece of recent information is the streak of earnings surprises, including the 5.61% and 1.60% beats, paired with a positive Earnings ESP ahead of the next report. That run puts a spotlight on how effectively Affiliated Managers Group is managing costs and mix toward alternatives where fee rates tend to be higher.
For you as an investor, the question is whether that earnings outperformance is mainly cyclical or reflects a more durable shift in affiliate contribution and capital deployment. It also ties directly into the main risk. If large affiliates such as Pantheon or AQR see weaker flows or performance, the sensitivity of those earnings beats to a few franchises could become clear very quickly.
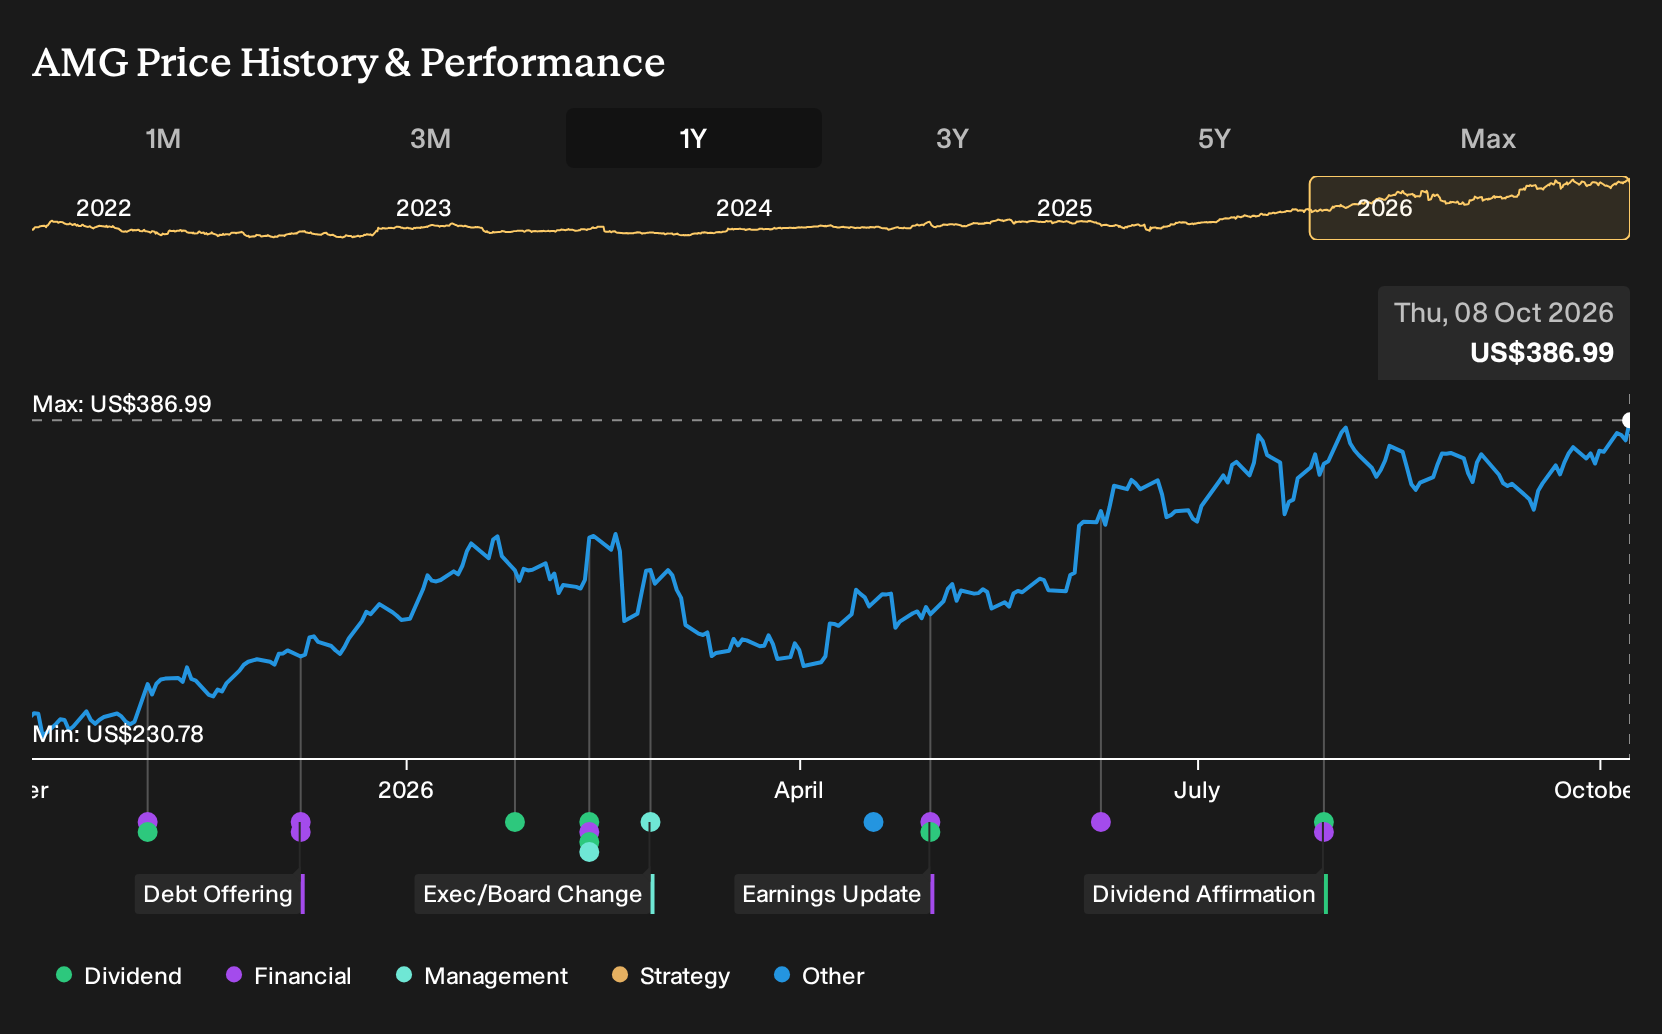
Affiliated Managers Group's current analyst storyline points to US$2.7b in revenue and US$966.7m in earnings by 2029, based on a projected 5.8% yearly top line expansion and an earnings increase of about US$110m from US$856.3m today.
Discover why Affiliated Managers Group's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view fixates on fee pressure instead of affiliate growth. The most cautious analysts were penciling in only US$2.6b of revenue and about US$856.0m of earnings by 2029, which implies flat profits for Affiliated Managers Group. Those pre news expectations paint a much more pessimistic story that may shift as fresh data lands.
Explore another Affiliated Managers Group fair value estimate, including one that suggests as much as 7% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Affiliated Managers Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Affiliated Managers Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Affiliated Managers Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Affiliated Managers Group?
Once you have formed a view on Affiliated Managers Group, it can help to line it up against other potential opportunities that suit different risk levels and income goals. The Simply Wall St Screener makes it easy to filter for stocks that match the type of portfolio you want to build, instead of working through tickers one by one.
- If you care most about quality at a reasonable entry point, start by scanning a 27 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect them.
- Income focused investors can look for steadier cash payouts by reviewing a 8 dividend fortresses that emphasise higher yields with backing from underlying financials.
- For those who put capital preservation first, reduce potential portfolio shocks by filtering for a 31 resilient stocks with low risk scores that have more resilient balance sheets and risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com