
Why Carpenter Technology (CRS) Is Back In The Spotlight
Carpenter Technology (CRS) moved into focus after its latest quarterly update, where earnings per share reached 3.23 and the business reported a profit margin close to 19%, drawing fresh attention to its long term return profile.
Carpenter Technology shares now trade at US$387.10, after the price fell about 16% over the past month and dropped roughly 33% over the past quarter, even though the year to date share price return is still positive and the 1 year total shareholder return is 54.7%. Investors are weighing that pullback against a very large 3 year total shareholder return and an even larger 5 year total shareholder return. This suggests long term holders have already seen a substantial payoff while newer buyers are reassessing how much of the recent earnings strength is already reflected in the valuation.
Scan how Carpenter Technology compares to other industrials showing strong profitability and recent price pressure by reviewing the curated 27 high quality undervalued stocks, which may also warrant a closer look.
After that sharp slide, Carpenter Technology now sits well below both its analyst target and one estimate of intrinsic value. Is the current quote a discount to fair value or already generous?
Most Popular Narrative: 37% Undervalued
Against Carpenter Technology's last close at $387.10, the most followed narrative anchors fair value at $612.13, implying a sizeable valuation gap that analysts tie directly to long term earnings power rather than short term sentiment.
The brownfield expansion project is set to add high-purity melt capacity, allowing Carpenter to further leverage the industry supply-demand imbalance over the medium to long term. This will support higher volumes and sustained pricing power, translating into increased revenue and operating income beginning FY28.
See why 25 investors see Carpenter Technology as 37% undervalued.
Result: Fair Value of $612.13 (UNDERVALUED)
Still, the story can break if the US$400m expansion fails to earn its keep, or if aerospace demand softens and squeezes Carpenter Technology's rich margins.
Find out about the key risks to this Carpenter Technology narrative.
Another View: Carpenter Technology Through The Earnings Multiple Lens
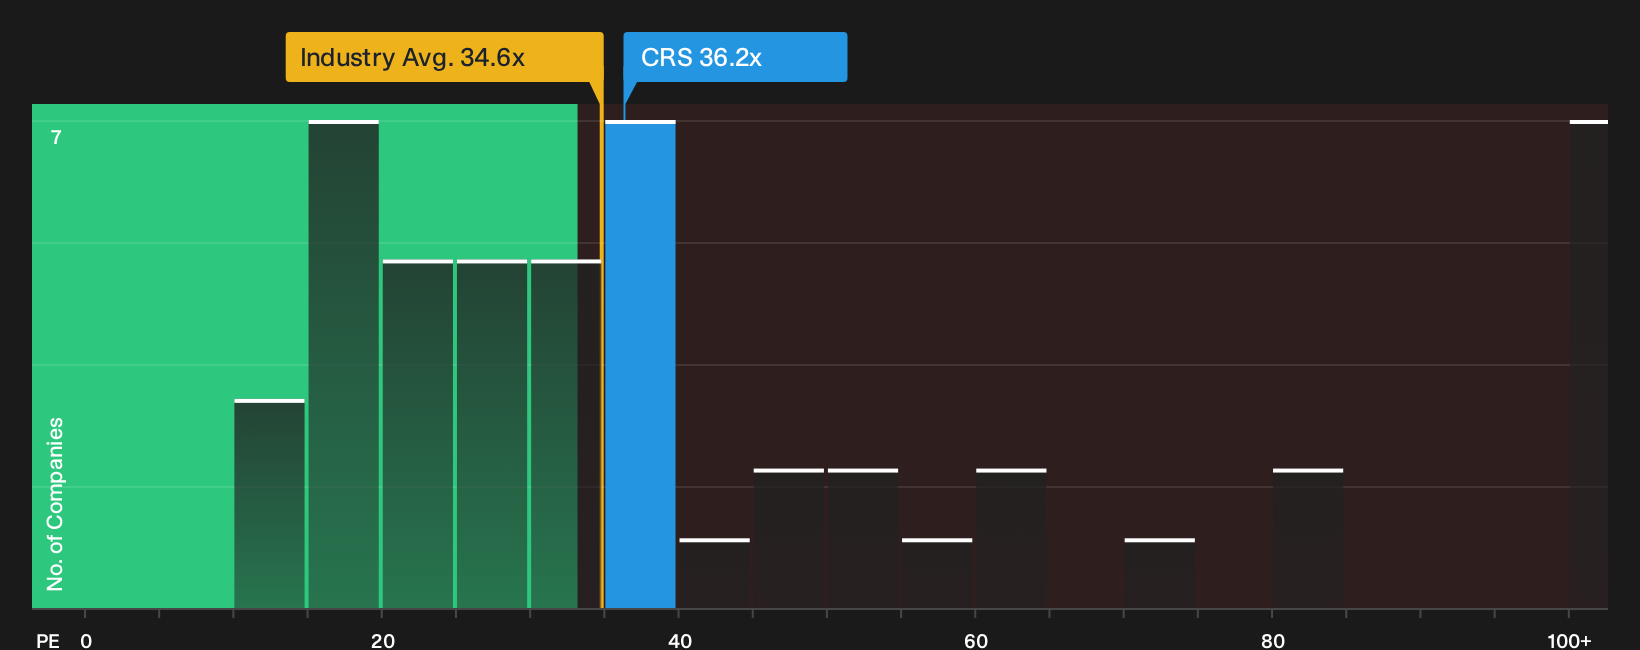
The story looks different once Carpenter Technology is measured against earnings based yardsticks instead of fair value models. At a P/E of 36.2x, the stock trades above the US Aerospace & Defense sector on 34.6x and well ahead of a fair ratio of 29.2x that the market could move toward over time. That gap points to valuation risk if sentiment cools or if investors start demanding a lower multiple for the same earnings stream.
To see what the numbers say about this price in more depth, review the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Carpenter Technology's value case and risk profile can be hard to reconcile, so review the data yourself and form a clear opinion using the breakdown of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Carpenter Technology?
Carpenter Technology may be front of mind today, but you will often get better results by lining it up against other clear, data driven ideas.
- Target stability first and filter for resilient businesses using our 31 resilient stocks with low risk scores, so you are not only chasing excitement.
- Hunt for quality at a discount and scan the 20 high quality undiscovered gems before the crowd prices in their fundamentals.
- Prioritise financial strength and compare Carpenter Technology against a list of solid balance sheet and fundamentals (25 results) to avoid surprises buried in weak balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com