
Pfizer (PFE) Stock Looks Expensive Following Its 18% One Year Gain
Pfizer shares have climbed 18.0% over the past year, so the immediate question for anyone looking at the stock today is whether that move is matched by what the business is earning.
- An 18.0% gain over 12 months puts real weight on the question of whether Pfizer’s current earnings profile can carry the higher share price.
- Fresh oncology approvals such as the expanded use of TUKYSA, along with new cancer and immunology programs, can influence how investors think about future profit streams and the durability of Pfizer’s earnings base.
- The analysts covering Pfizer have run their own numbers. See what analysts think Pfizer's shares could be worth.
The issue now is whether the price near US$27.82 is well supported by Pfizer’s earnings when judged against a Fair Ratio yardstick.
If you are weighing Pfizer after its 18.0% one year gain, it can help to compare its earnings story with other companies screened for 27 high quality undervalued stocks.
Has Pfizer Run Too Far on Earnings?
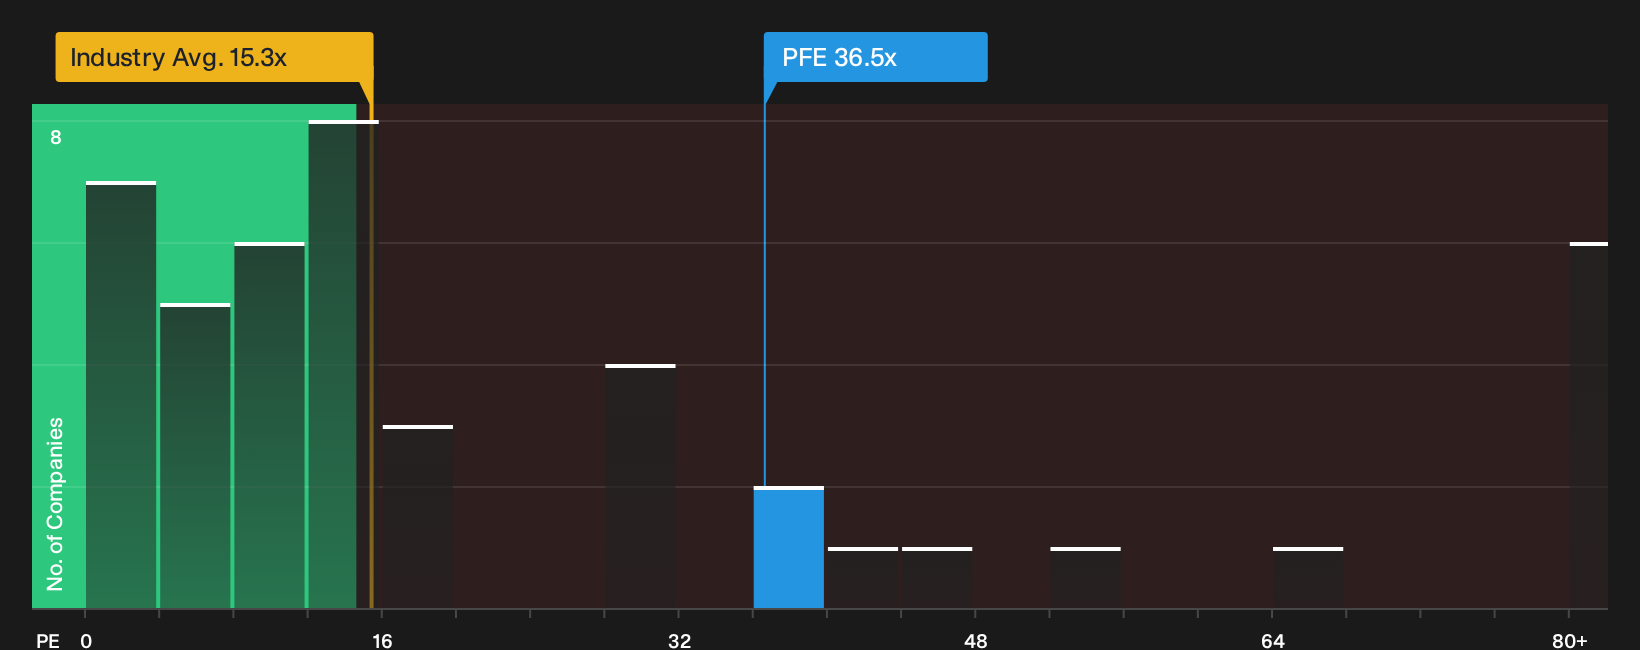
The P/E ratio is a decent fit for Pfizer because earnings still drive much of how investors think about the stock. On this measure, Pfizer trades on about 36.5x earnings, which is more than double the Pharmaceuticals sector average of roughly 15.3x and still below the peer group average near 54.5x. That places the shares in a higher priced bracket than the typical industry listing, even though they do not reach the most expensive end of the large cap peer set.
Using a Fair Ratio framework, which adjusts the P/E you might expect for Pfizer’s size, margins, industry profile and risk, the current multiple screens as overvalued. Despite fresh oncology headlines around TUKYSA and a wider cancer pipeline, the valuation already assumes a lot of earnings power relative to this tailored benchmark, so you would want to be confident in the durability of those profits before relying on the P/E alone as a green light. Explore the numbers behind Pfizer's P/E valuation.
The Pfizer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Pfizer's valuation puzzle leaves off, by spelling out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or less than today, and they sit on the company’s Community page. Instead of a single output from a ratio or model, Narratives lay out the future that figure assumes so you can watch over time whether reality tracks that script.
Bulls see Pfizer as roughly in line with its earnings power while bears think the current price already leans on a tougher execution story.
Bull case: roughly fairly valued
"Expansion of launched and acquired products, which management now describes as running at around a US$13b annualized revenue rate and growing in the 20% range, continues to support the view that Pfizer can further shift its mix toward non COVID therapies..."
Discover why this Narrative puts Pfizer at roughly fairly valued.
Bear case: 11% overvalued
"The current numbers imply Pfizer's share price already reflects successful execution on cost savings and pipeline delivery, leaving limited room for error if any of these pillars underperform..."
Explore why this Narrative puts Pfizer at 11% overvalued.
Pfizer's value also depends on who is at the wheel
Price multiples tell only part of the Pfizer story, because the people choosing where to invest cash and how they are rewarded can tilt long-term outcomes in ways the ratios alone cannot capture. See who runs Pfizer and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com