
Cognex (CGNX) Could Be 24% Undervalued After Macro Driven Selloff
Why Cognex is back on investors’ radar
Cognex (CGNX) has moved into focus after a 7.5% share price drop tied to rising Treasury yields and higher oil prices ahead of the Federal Reserve's September meeting minutes.
The pullback comes just days after Cognex participated in a European non deal roadshow on October 5. The event put management's latest read on demand, costs, and automation spending in front of institutional investors.
The selloff ties into a wider reset in Cognex’s momentum, with the share price down 8.8% over the past 90 days, while still showing a 64.9% year to date share price return and a 31.6% 1 year total shareholder return, as investors reassess growth prospects and risk after a strong run.
Scan how Cognex stacks up against other automation and robotics plays by running the hand picked 91 robotics and automation stocks that screens for similar themes and financial profiles.
Cognex looks like a solid automation business on the surface, with machine vision products spread across multiple industries and regions. After a sharp pullback and a strong year to date run, is that quality being priced fairly today?
Most Popular Narrative: 23.5% Undervalued
Cognex's most followed narrative estimates fair value at $79.58, compared with the last close at $60.91. This view places significant emphasis on execution in AI vision and margin discipline.
The main factor that has to go right is that Cognex successfully executes its diversification and operating model transformation. This includes integrating RealSense, scaling newer verticals such as packaging and data centers, and maintaining high incremental margins and strong free cash flow conversion.
See why 31 investors see Cognex as 23% undervalued.
Result: Fair Value of $79.58 (UNDERVALUED)
Still, Cognex’s story depends on hardware avoiding heavy price pressure, and the RealSense deal not diluting margins if scaling takes longer than expected.
Find out about the key risks to this Cognex narrative.
Another View: Cognex on richer earnings multiples
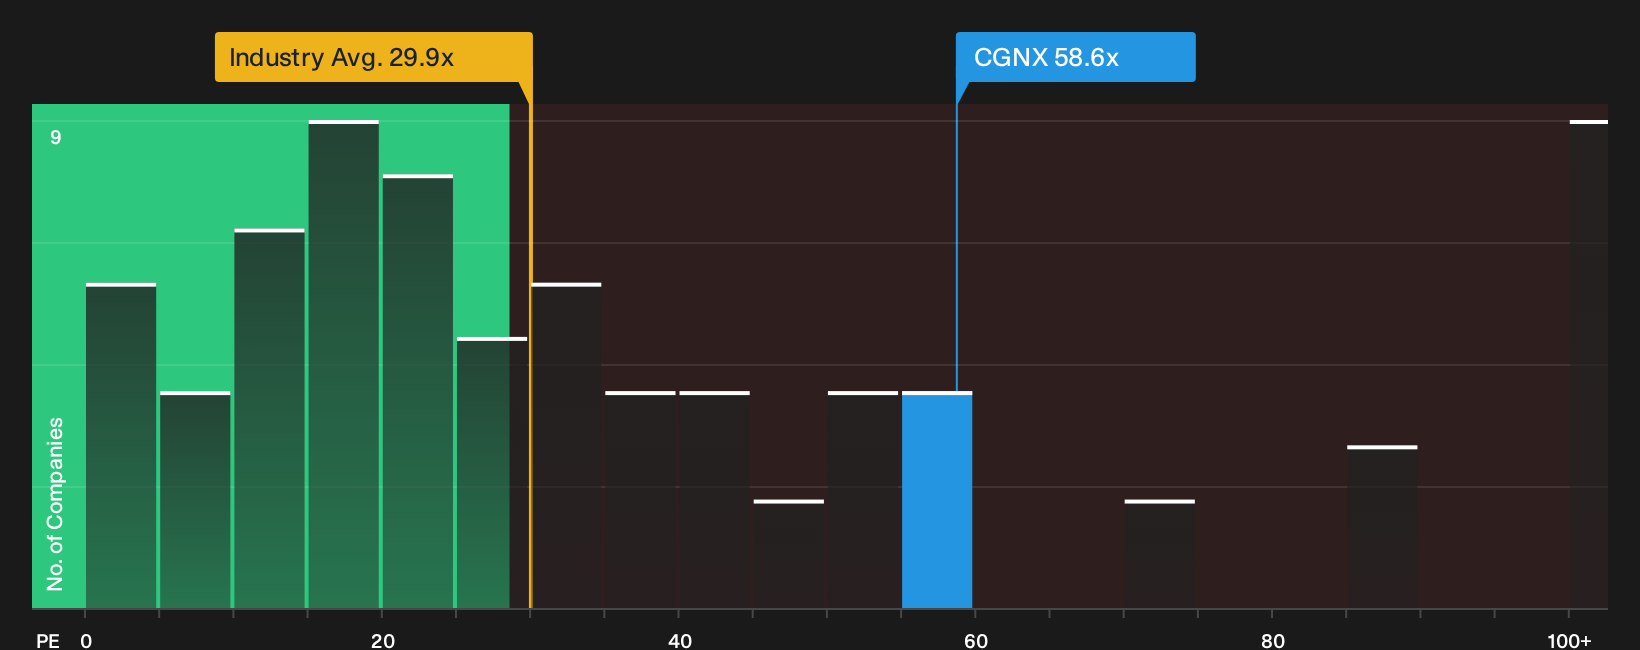
The narrative around Cognex leans on a fair value of $79.58, yet the current P/E of 58.6x sits far above a fair ratio of 33.1x, the US Electronic industry average of 29.9x and a peer mark of 49.3x. That kind of premium raises a simple question: How much optimism are you really paying for?
To pressure test that premium using earnings based metrics, and see what the numbers imply for future re rating risk or support, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer visual of how Cognex compares against its sector on this metric, review the latest relative P/E snapshot in
Next Steps
If sentiment around Cognex feels split, use that as a prompt to move quickly and stress test the data for yourself before the next narrative forms. To see what has investors optimistic right now and weigh those factors against the risks, spend a moment with the 3 key rewards.
Looking for more Cognex sized investment ideas?
If Cognex has you thinking harder about valuation, do not stop here. Broaden your watchlist now so you are not chasing opportunities after the move.
- Target quality at a discount by scanning the 27 high quality undervalued stocks that filters for stronger fundamentals at prices that may still leave room for upside.
- Prioritise resilience by checking the 31 resilient stocks with low risk scores that focuses on companies with sturdier balance sheets and lower risk scores.
- Spot potential early movers by reviewing the 20 high quality undiscovered gems that highlights under followed businesses with solid financial profiles before they appear on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com