
Rheinmetall (XTRA:RHM) Faces A Post 2030 Growth Test, Is The Pullback Pricing In Too Much Risk?
Berenberg’s downgrade of Rheinmetall (XTRA:RHM) to Hold put a spotlight on a different issue for you as an investor: how durable the group’s growth story looks after 2030.
Rheinmetall’s share price has eased in recent months, with a 30 day share price return of down 11.11% and a year to date share price return of down 41.64%. However, the 3 year total shareholder return of 257.23% and 5 year total shareholder return of more than 10x still point to a powerful long haul story, where recent weakness hints at investors reassessing how much future growth and contract risk they are willing to pay for today.
Compare Rheinmetall’s long-haul defence story with other contractors by scanning our curated list of 226 resilient stocks with low risk scores that still show resilience when growth visibility starts to thin out.
Rheinmetall now trades at a steep discount to both analyst targets and some fair value estimates after the pullback. Is that pricing in long term contract risk sensibly, or overshooting on caution as growth visibility fades after 2030?
Most Popular Narrative: 84% Undervalued
At a last close of €934.90, Rheinmetall trades far below the most followed narrative fair value of €5,865. This frames the recent pullback as a valuation reset rather than a broken story.
By 2029, the market may begin to view Rheinmetall less as an early-stage high-growth company and more as a large, highly profitable defense manufacturer.
This could result in P/E multiple compression even if earnings continue to rise.
See why 17 investors see Rheinmetall as 84% undervalued.
Result: Fair Value of €5,865 (UNDERVALUED)
Still, the Rheinmetall story can be knocked off course if large defense contracts face delivery setbacks or if European budgets pivot toward competing suppliers.
Find out about the key risks to this Rheinmetall narrative.
Another View: Rheinmetall Through The P/E Lens
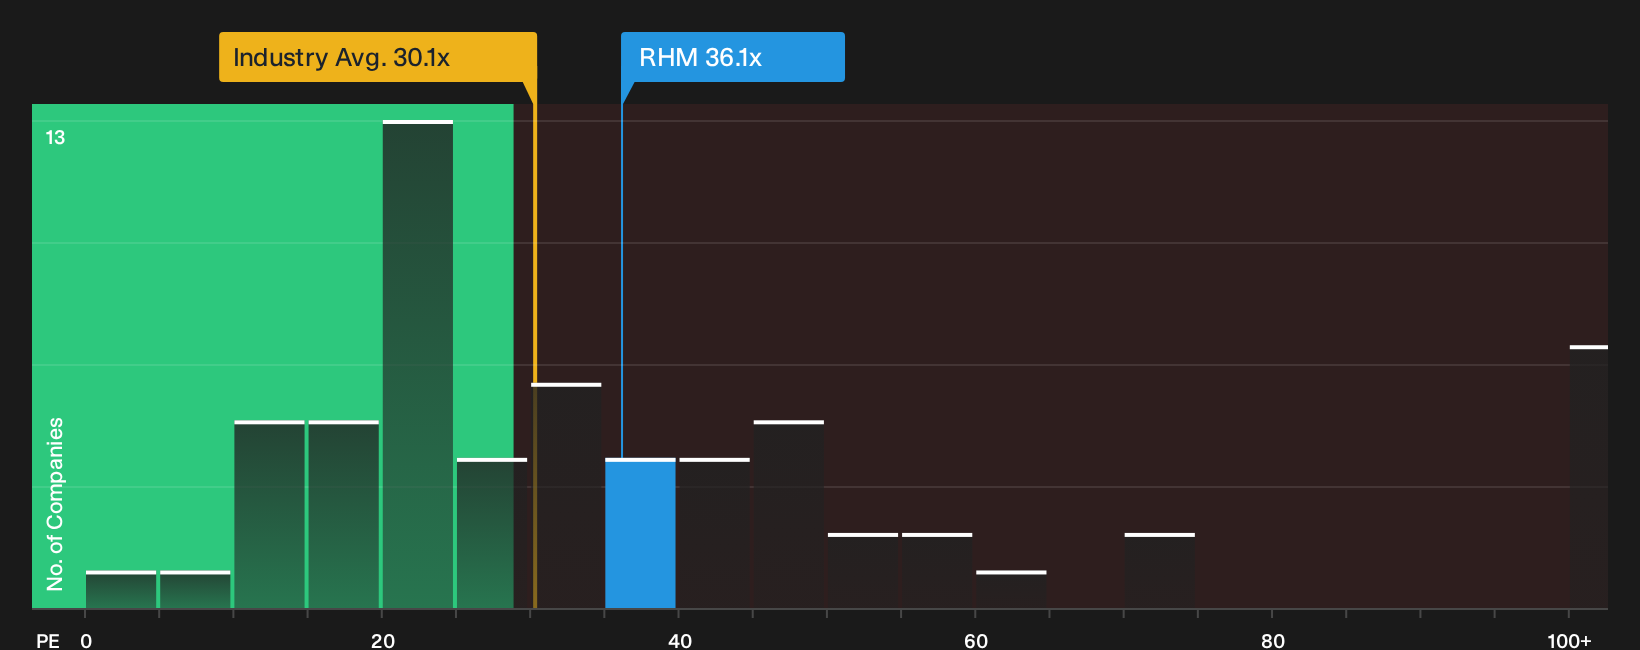
There is a very different picture when Rheinmetall is viewed through its P/E. The stock trades at 36.1x earnings, above the European Aerospace & Defense average of 30.1x, yet below the peer group on 56.3x and below a fair ratio of 44.5x.
In plain terms, the share looks expensive against the wider sector, cheaper than closer peers, and still below where the fair ratio suggests the market could drift over time. For an investor, that mix points to valuation risk if sentiment cools and potential upside if earnings keep tracking current forecasts. Which side of that trade-off feels more realistic to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Rheinmetall’s valuation and risk profile can feel messy, so move quickly, review the full data set, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Rheinmetall?
If Rheinmetall’s valuation tug of war has you thinking about diversification, widen the lens and use data driven stock ideas to strengthen your watchlist.
- Target resilient income by scanning companies that appear in our 225 dividend fortresses and see which payouts look more dependable.
- Hunt for mispriced opportunities through the 619 high quality undiscovered gems and spot businesses the broader market might be overlooking.
- Protect your downside by focusing on sturdier balance sheets with the list of solid balance sheet and fundamentals (206 results). This can help you stress test your portfolio against potential future shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com