
3 European Stocks Trading At An Estimated Discount Of Up To 40.4%
European markets have recently experienced volatility, with the STOXX Europe 600 Index declining amid rising oil prices and elevated sovereign bond yields. As investors navigate these challenging conditions, identifying stocks that are potentially undervalued can offer opportunities for growth, especially when inflationary pressures suggest that monetary policy may remain tight.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| PORR (WBAG:POS) | €31.25 | €60.51 | 48.4% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.90 | 49.4% |
| MBB (XTRA:MBB) | €168.20 | €311.07 | 45.9% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.67 | €22.73 | 48.7% |
| ING Groep (ENXTAM:INGA) | €29.425 | €58.51 | 49.7% |
| Infotel (ENXTPA:INF) | €37.20 | €68.20 | 45.5% |
| Huuuge (WSE:HUG) | PLN23.40 | PLN45.71 | 48.8% |
| Grupa Pracuj (WSE:GPP) | PLN55.50 | PLN108.64 | 48.9% |
| DWS Group GmbH KGaA (XTRA:DWS) | €66.00 | €127.68 | 48.3% |
| Apator (WSE:APT) | PLN25.60 | PLN49.19 | 48% |
Here's a peek at a few of the choices from the screener.
L.D.C (ENXTPA:LOUP)
Overview: L.D.C. S.A. is a company that produces and sells poultry and convenience products both in France and internationally, with a market cap of €3.52 billion.
Operations: The company's revenue is derived from its operations abroad (€1.42 billion), poultry sales (€4.81 billion), and processing activities (€1.17 billion).
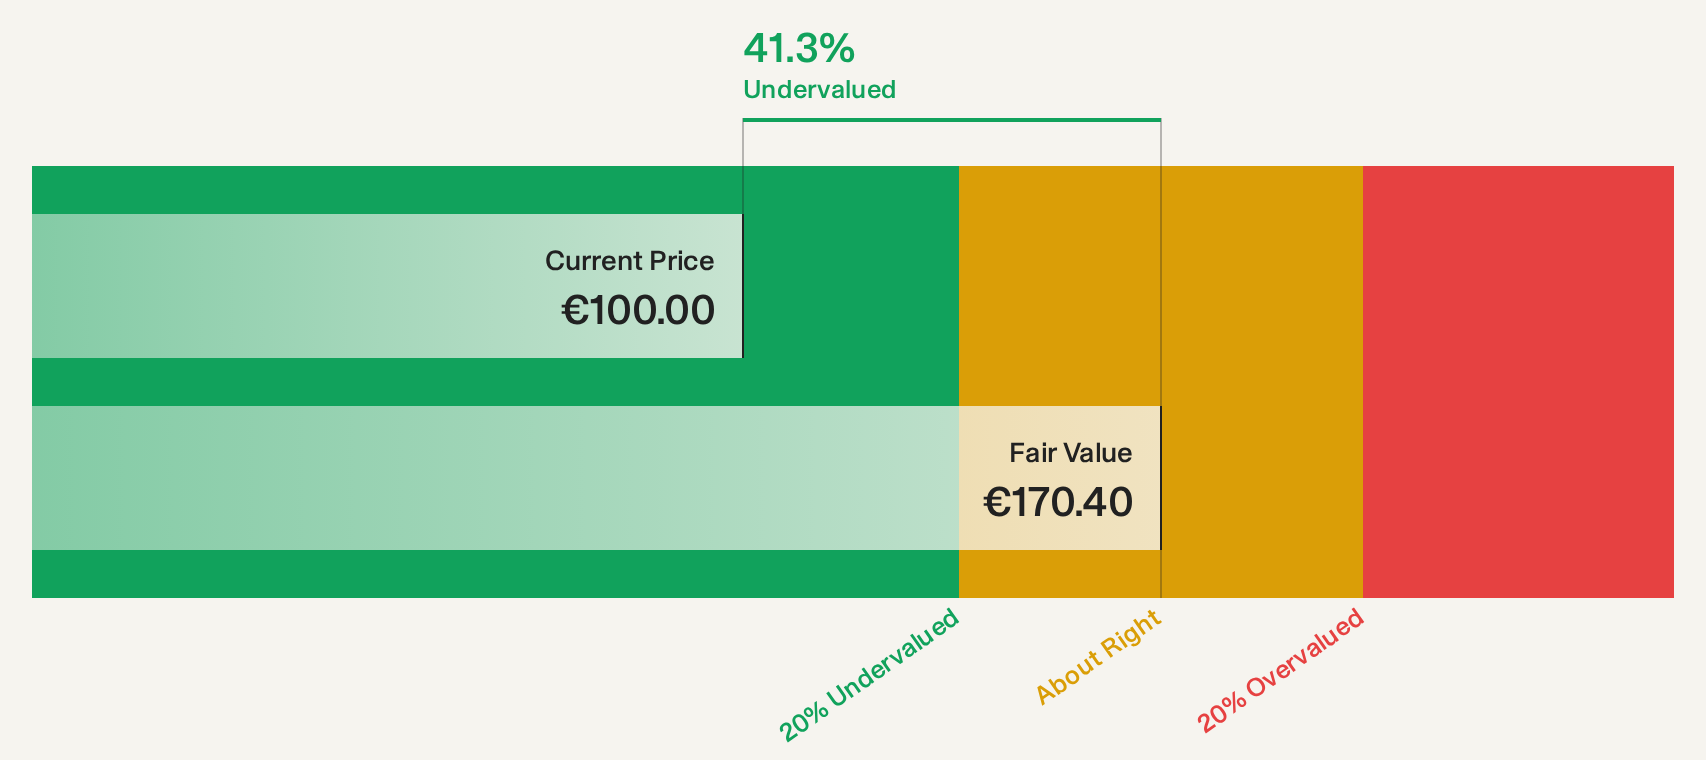
Estimated Discount To Fair Value: 40.4%
L.D.C. is trading at €101.6, significantly below its estimated future cash flow value of €170.4, indicating it may be undervalued based on cash flows. Despite a recent dividend decrease to €0.59 per share, earnings grew by 32% over the past year and are expected to continue growing annually by 4.23%. However, growth forecasts remain below both French market averages and analyst expectations for significant earnings increases or return on equity improvements in the near term.
- Our comprehensive growth report raises the possibility that L.D.C is poised for substantial financial growth.
- Dive into the specifics of L.D.C here with our thorough financial health report.
Logitech International (SWX:LOGN)
Overview: Logitech International S.A. designs, manufactures, and markets software-enabled hardware solutions for work, creativity, and gaming globally, with a market cap of CHF12.05 billion.
Operations: The company generates revenue of $4.92 billion from its peripherals segment, which includes software-enabled hardware solutions for various applications such as work, creativity, and gaming.
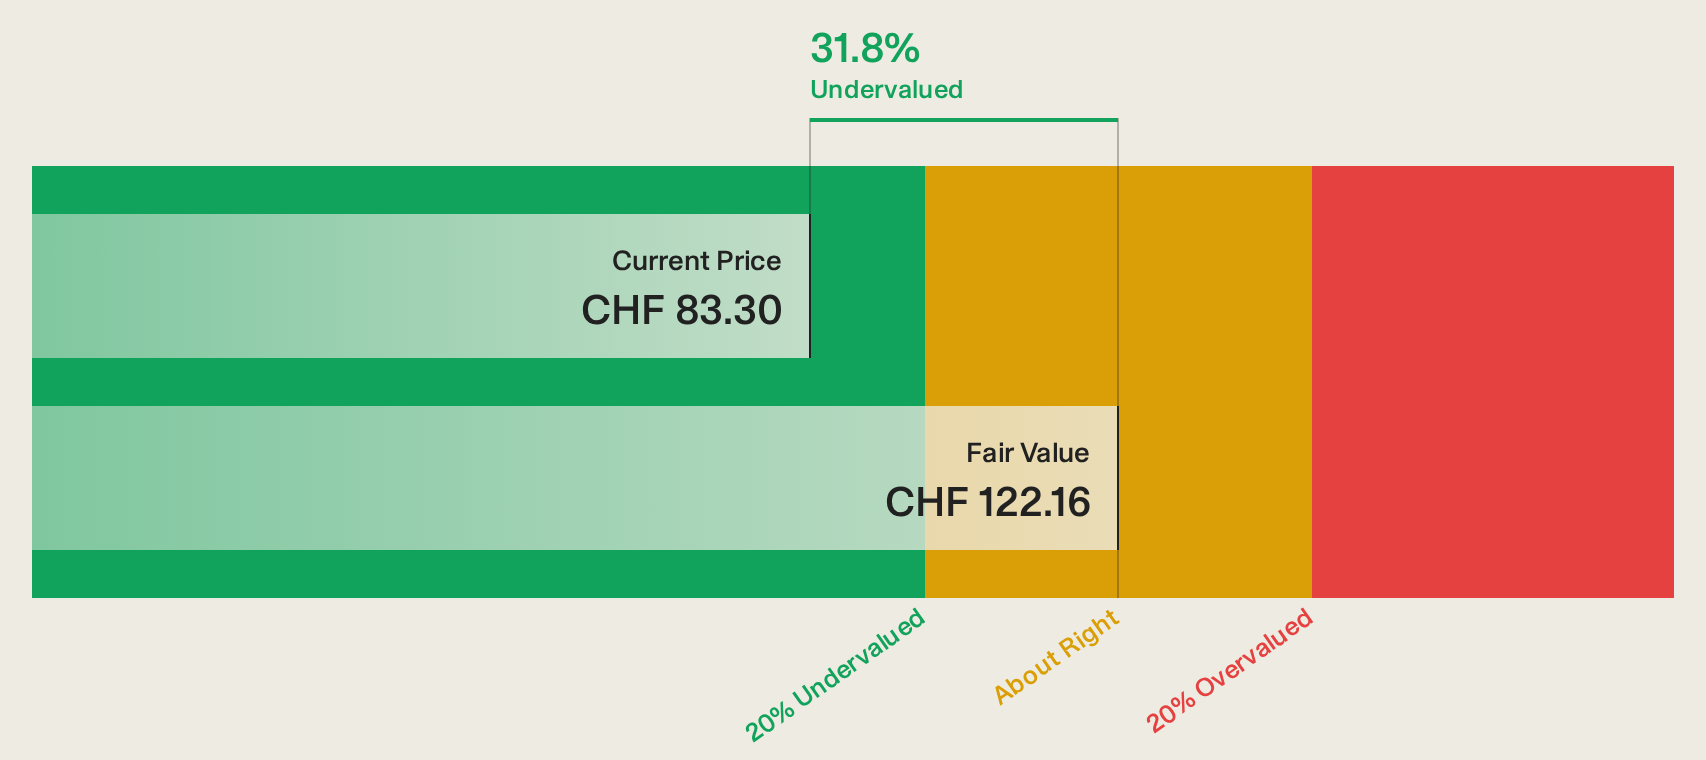
Estimated Discount To Fair Value: 33.1%
Logitech International is trading at CHF84.12, well below its estimated future cash flow value of CHF125.68, suggesting potential undervaluation based on cash flows. Recent earnings grew by 26%, yet forecasted annual profit growth of 2.4% remains below the Swiss market average of 12.4%. Despite this, Logitech's return on equity is projected to be robust at 31.9% in three years, and it offers good relative value compared to industry peers.
- Our growth report here indicates Logitech International may be poised for an improving outlook.
- Click here to discover the nuances of Logitech International with our detailed financial health report.
Voestalpine (WBAG:VOE)
Overview: Voestalpine AG is involved in processing, developing, manufacturing, and selling steel and technology products across Austria, the European Union, and internationally with a market cap of €7.26 billion.
Operations: The company's revenue is primarily derived from its Steel Division (€5.77 billion), Metal Forming Division (€3.08 billion), Metal Engineering Division (€4.02 billion), and High Performance Metals Division (€2.81 billion).
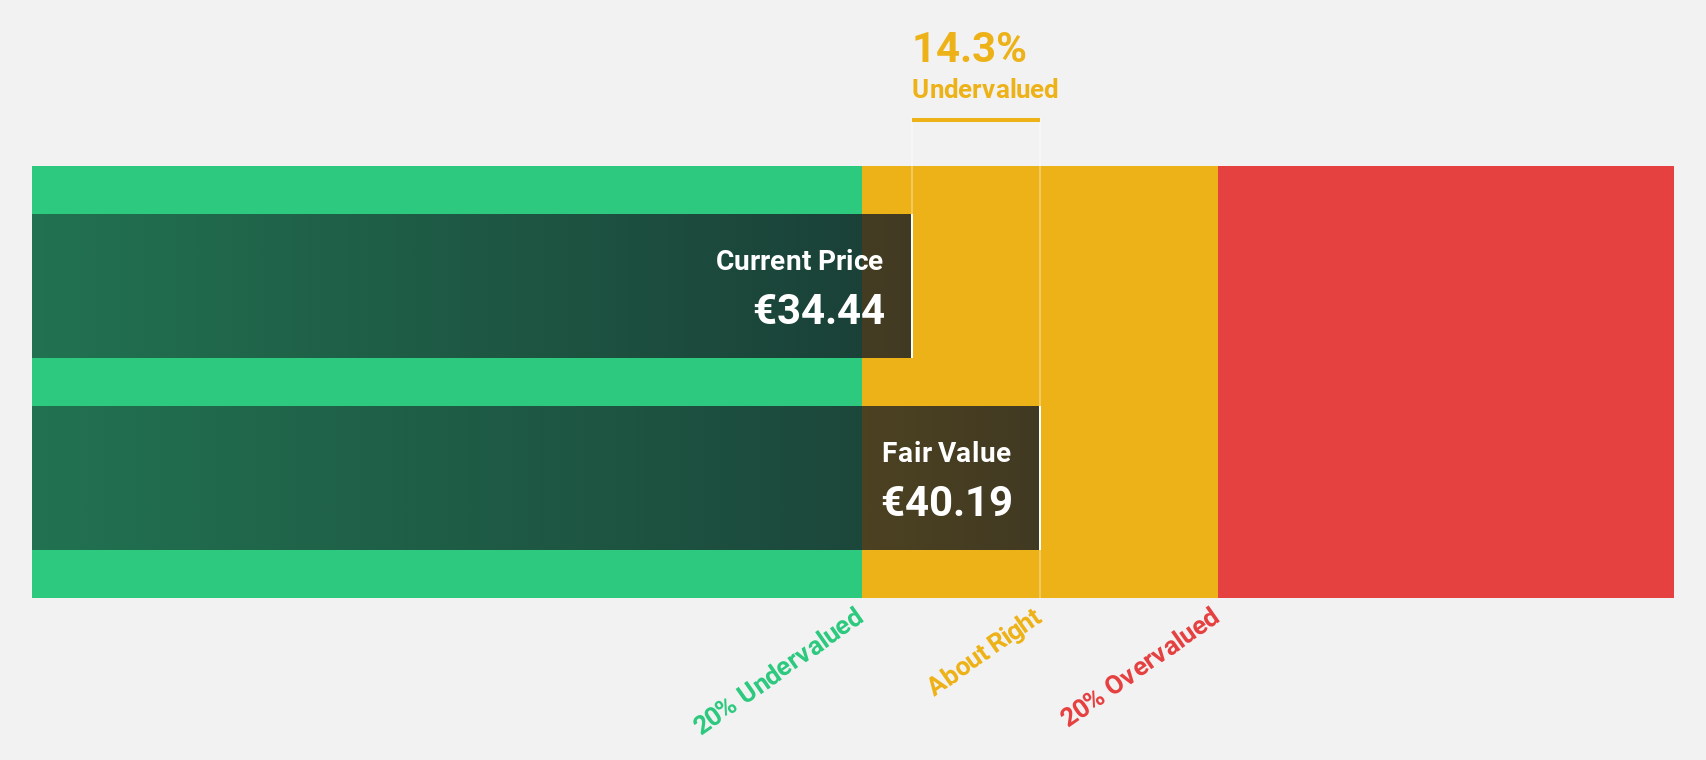
Estimated Discount To Fair Value: 35.2%
Voestalpine is trading at €42.36, significantly below its estimated future cash flow value of €65.37, highlighting its undervaluation based on cash flows. The company's earnings grew by a substantial 335.9% over the past year and are expected to continue growing at 21.3% annually, outpacing the Austrian market's average growth rate. Despite this positive outlook, revenue growth is forecasted to lag behind the market average, and return on equity remains modest at 10.1%.
- According our earnings growth report, there's an indication that Voestalpine might be ready to expand.
- Unlock comprehensive insights into our analysis of Voestalpine stock in this financial health report.
Taking Advantage
- Click here to access our complete index of 61 Undervalued European Stocks Based On Cash Flows.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com