
Centrus Energy (LEU) Signs Antares HALEU Deal, Is The Stock 25% Undervalued?
Centrus Energy (LEU) has signed a definitive multi-year deal to supply High-Assay Low-Enriched Uranium to Antares Nuclear, backed by customer prepayments and its licensed HALEU facility in Ohio.
For Centrus Energy, the new HALEU contract arrives in a period where momentum has cooled. The share price is at US$142.09, with a 30-day share price return down 23.41% and year-to-date share price return down 47.86%. At the same time, the 3-year total shareholder return is up 178.23%, so the recent swings around sector-wide uranium volatility and the Antares deal are playing out against a backdrop of strong longer-term gains but fading short-term enthusiasm.
Surf 16 nuclear energy infrastructure stocks that, like Centrus Energy, are tied to nuclear infrastructure catalysts and could be next in line when sentiment swings back toward the sector.Centrus Energy now trades far below some fair value estimates after that sharp pullback, so how much of the HALEU story is already in the price and how much still represents a discount?
Most Popular Narrative: 25% Undervalued
Centrus Energy closed at $142.09, while the most followed narrative on the stock assigns a fair value of $190. That gap is where believers in the HALEU story see mispricing tied directly to fuel supply rather than headline uranium prices.
HALEU availability represents a potential bottleneck for the next wave of nuclear technology. If reactor developers advance toward commercialization while fuel supply remains constrained, companies positioned within the enrichment and fuel supply chain could become strategically important.
See why 42 investors see Centrus Energy as 25% undervalued.
According to CentryResearch, that thesis leans heavily on Centrus Energy offering what is framed as the most direct public-market exposure to US HALEU production, a specialized segment that is not easily replicated. The narrative also flags that while the broader nuclear theme can be accessed through uranium producers or reactor developers, HALEU enrichment capacity is where much of the real constraint sits, which is why this contract pipeline and the licensed Ohio facility matter so much to the story.
That same storyline does not ignore risk. It highlights that Centrus Energy still needs to scale from proof-of-concept output to larger commercial volumes, that HALEU economics depend on government backing and customer follow-through, and that advanced reactor deployment could take longer than planned. Put differently, the fair value of $190 backed by a 7.108% discount rate assumes the bottleneck in fuel persists long enough for Centrus to earn a return on its $3.0b market cap that investors view as adequate for that level of risk.
For readers who want to see how that narrative fits alongside formal valuation work, forecasts and risk flags on Centrus Energy, the full narrative and valuation breakdown sit in one place See our AI narrative and valuation for Centrus Energy..
Result: Fair Value of $190 (UNDERVALUED)
Still, the Centrus Energy narrative can break if government HALEU support fades or if advanced reactor deployment slows enough to ease the fuel bottleneck.
Find out about the key risks to this Centrus Energy narrative.
Another View: Centrus Energy Looks Expensive On Earnings
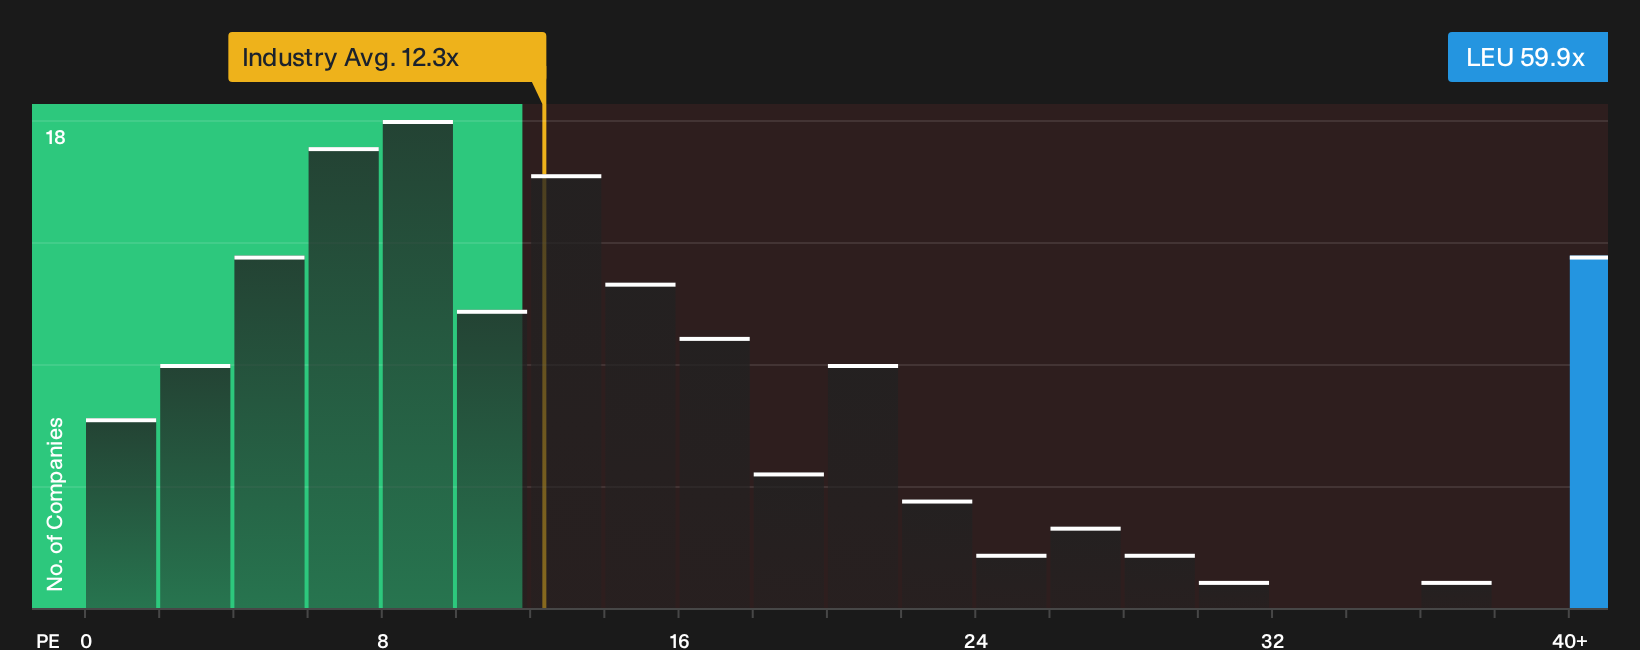
The fair value narrative pins Centrus Energy at $190, yet the P/E picture points in a different direction. At 59.9x earnings, the stock trades at almost 3x the US Oil and Gas industry on 12.3x and well above peers on 21.5x, while the fair ratio sits at just 10.1x.
That kind of gap raises a simple question for investors. Is the HALEU story strong enough to justify paying a much higher multiple than both sector averages and the fair ratio the market could move toward, or is sentiment asking too much from future profits?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed mood around Centrus Energy leaves you unsure, act quickly, review the data, and evaluate both the 1 key reward and 2 important warning signs.
Looking For More Ideas Beyond Centrus Energy?
Do not stop with Centrus Energy. Use the screener to surface other opportunities that match your style before the next wave of interest moves past you.
- Target resilient cash generators by scanning our list of solid balance sheet and fundamentals (25 results) that can help anchor a portfolio when sentiment swings.
- Hunt for mispriced potential with the 20 high quality undiscovered gems that many investors have not yet focused on.
- Prioritize calmer rides by checking the 31 resilient stocks with low risk scores that aim to keep drawdowns more manageable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com