
3 Australian Value Stocks For October 2026
High oil prices and rising US Treasury yields are pushing many investors toward safer income options like government bonds. That can leave some Australian cash rich businesses trading on the back foot, even when their future cash flows look solid based on discounted cash flow work. This disconnect can create mispricing. In this article you will see three stocks that currently screen as interesting value opportunities on cash flows.
The three stocks in this article are just a sample set from the cash flow screen. The full Simply Wall St filter surfaces 6 more businesses with equally compelling stories that are not covered below.
Identify your own highest conviction ideas by going straight to the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper producer focused on the Havieron project in Western Australia, where future mine cash flows drive its value case.
Operations: Greatland Resources currently reports A$2.26b in revenue from its Telfer-Havieron segment, reflecting its concentration in that single producing asset.
Market Cap: A$6.74b
Greatland Resources matters for this cash flow screen because the Havieron project turns what was once an exploration story into a business increasingly judged on real and projected mine cash generation.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
What could reshape the picture is how one unresolved pressure on future free cash flow ultimately feeds through to investor expectations.
That cash flow pressure is the real swing factor for Greatland Resources, and the full narrative for Greatland Resources shows how that risk could turn into accelerating upside.
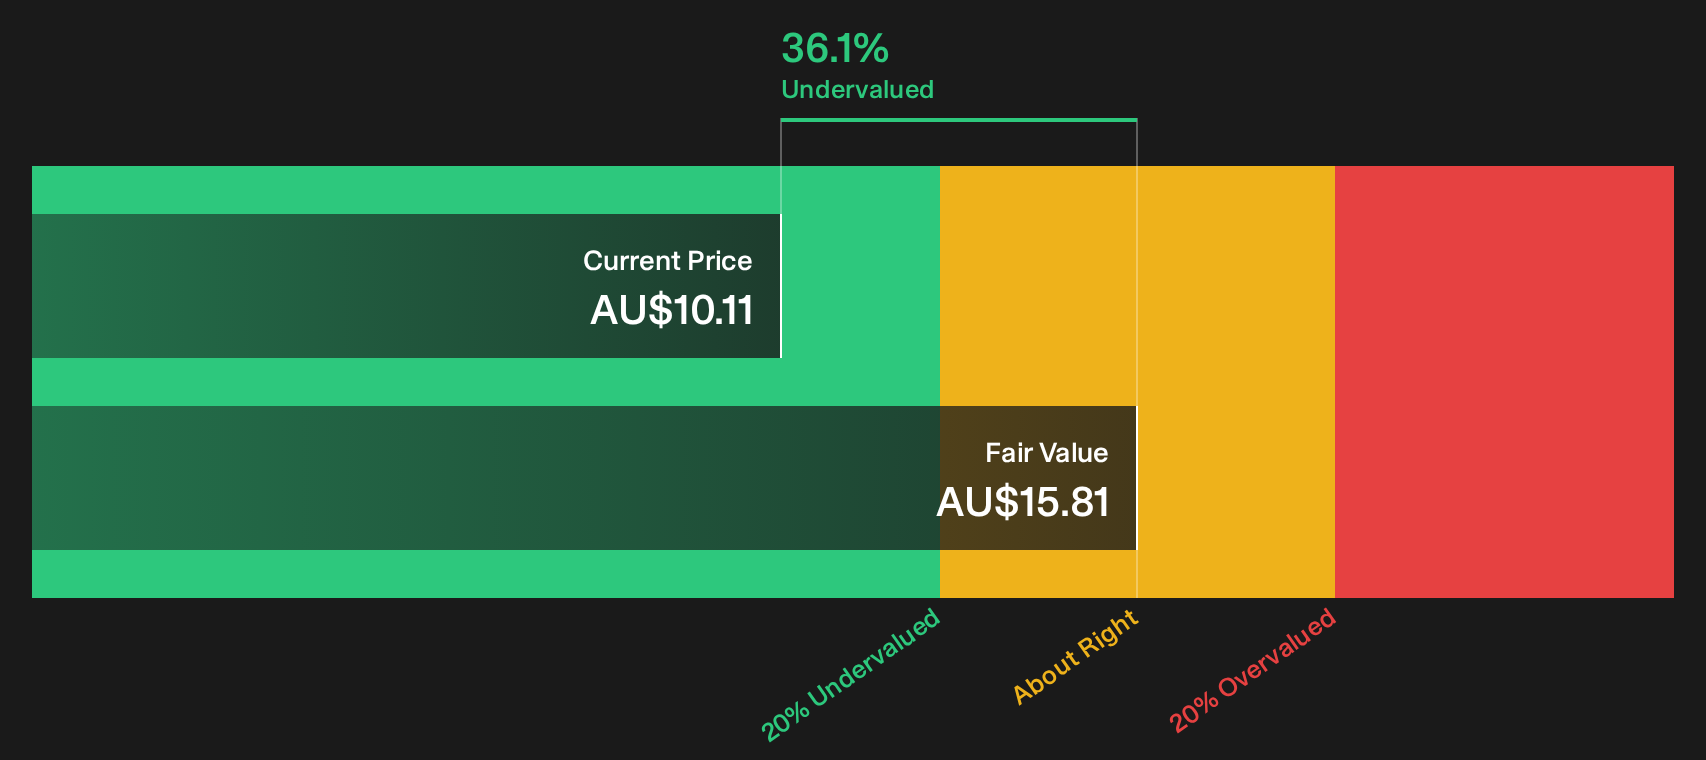
Ansell (ASX:ANN)
Overview: Ansell is a global PPE supplier. Its Healthcare glove brands generate recurring, cash-flow-focused sales to hospitals, labs, and industrial customers.
Operations: Ansell generates about US$1.19b from Healthcare and US$947 million from Industrial protection, with revenue spread across North America, Europe, Asia Pacific, Latin America, and Australia.
Market Cap: A$6.26b
Ansell matters for this cash-flow-focused screen because its Healthcare glove portfolio, including GAMMEX, MICROFLEX and TouchNTuff, often behaves like a repeat-order utility for hospitals and labs, even though the Industrial arm also contributes a large share of earnings.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
A key factor to watch is how one less visible pressure on future margins may shape the staying power of those recurring glove cash flows.
That margin pressure is the hinge. Read the full narrative for Ansell to see how pricing power, mix shifts and capital allocation could be quietly reshaping Ansell’s cash engine.

Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a global hydrocarbon producer with LNG projects that anchor long-dated cash flows alongside oil and lower carbon ventures.
Operations: Woodside Energy Group generates about $7.29b from Australia, $4.62b from International, and $1.93b from Marketing activities.
Market Cap: A$61.42b
Woodside Energy Group fits this cash flow screen because its LNG projects supply long contracts and visibility. These can anchor discounted cash flow work even as the rest of the portfolio evolves around them.
"Investor optimism appears driven by expectations for long-term demand growth in Asian and emerging markets, with Woodside's global LNG expansion (Louisiana, Scarborough) positioned to capture this demand. However, these assumptions may underestimate the potential for rapid decarbonization policies or renewable adoption, which could affect future revenue and volume trends if LNG demand softens in key markets."
The core question for investors is how one emerging constraint on future free cash flow may shape the relationship between LNG resilience and shareholder returns.
If that constraint on future free cash flow is on your mind, the full narrative for Woodside Energy Group reveals how Woodside Energy Group could still convert LNG resilience into accelerating outcomes.
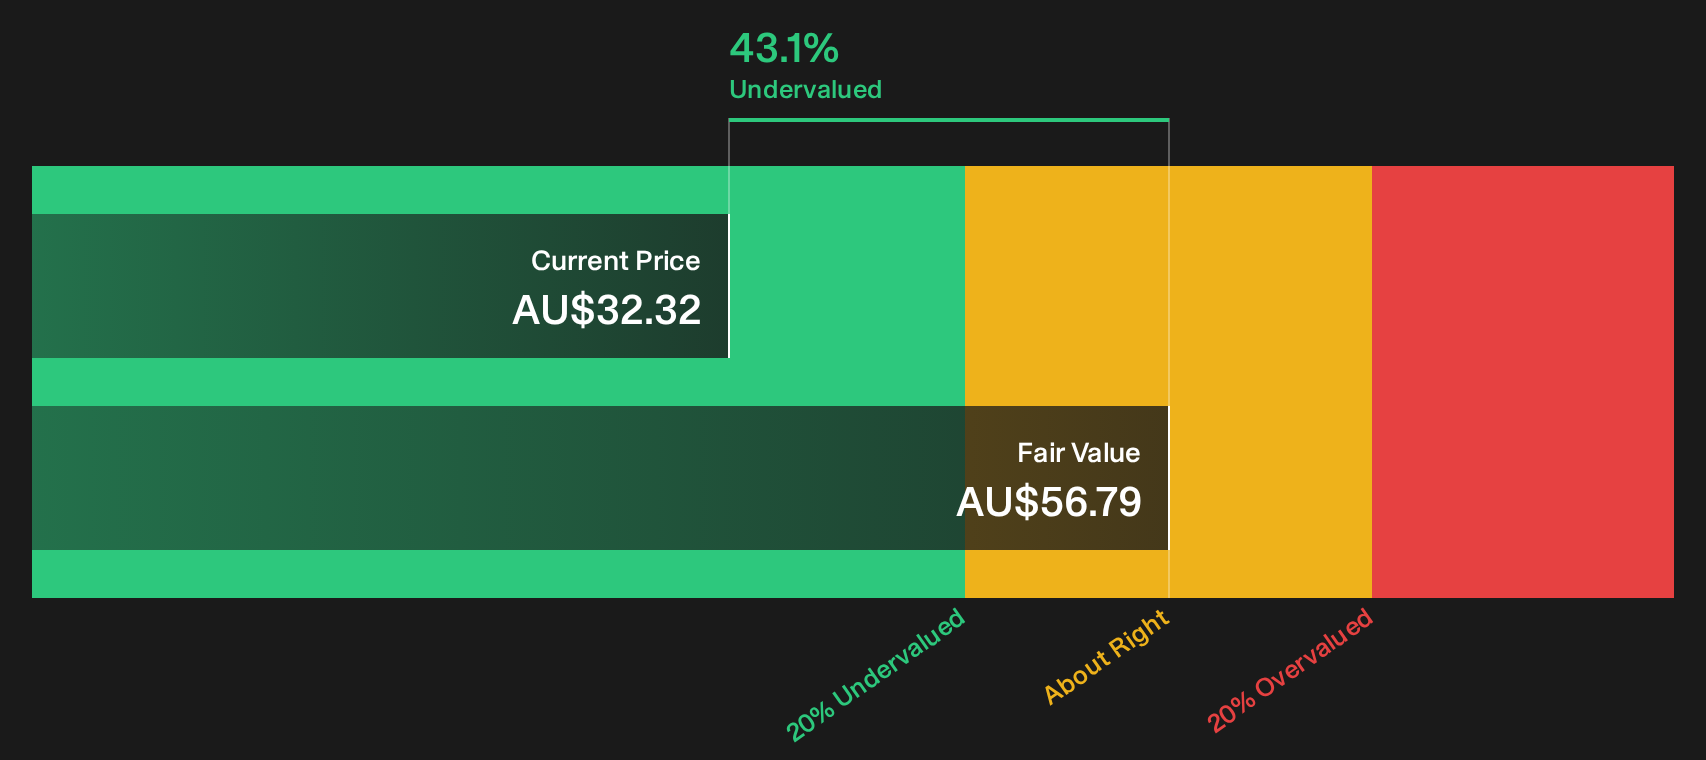
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first while older stories lose momentum. Before the next breakout list gets caught by the crowd, scan under the radar for now and act now.
- Spot cash rich businesses with strong balance sheets and shifting momentum by reviewing a curated list of solid balance sheet and fundamentals (12 results) before market attention catches up.
- Identify emerging themes in robotics, automation, and industrial efficiency by screening a hand picked pool of 88 robotics and automation stocks while adoption stories are still forming.
- Monitor potential shifts in interest in digital assets by checking a focused group of 20 cryptocurrency and blockchain stocks as sentiment and valuations evolve.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com