
Global Market Value Picks Featuring 3 Stocks Estimated Below Intrinsic Value
As global markets navigate a landscape marked by mixed economic signals, including fluctuating job growth and persistent inflation concerns, investors are increasingly focused on identifying opportunities that may offer value amid volatility. In such conditions, stocks estimated to be trading below their intrinsic value can present compelling prospects for those seeking to capitalize on potential market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Woori Financial Group (KOSE:A316140) | ₩32350.00 | ₩64525.41 | 49.9% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.90 | 49.4% |
| Nissui (TSE:1332) | ¥1086.50 | ¥2147.46 | 49.4% |
| Monde Nissin (PSE:MONDE) | ₱6.40 | ₱12.68 | 49.5% |
| Marco Polo Marine (SGX:5LY) | SGD0.118 | SGD0.23 | 49.4% |
| Kumagai GumiLtd (TSE:1861) | ¥1203.00 | ¥2368.59 | 49.2% |
| Innocean Worldwide (KOSE:A214320) | ₩17980.00 | ₩35599.11 | 49.5% |
| ING Groep (ENXTAM:INGA) | €29.425 | €58.51 | 49.7% |
| ENN Energy Holdings (SEHK:2688) | HK$49.14 | HK$96.85 | 49.3% |
| Double Medical Technology (SZSE:002901) | CN¥39.60 | CN¥79.04 | 49.9% |
We're going to check out a few of the best picks from our screener tool.
Tofas Türk Otomobil Fabrikasi Anonim Sirketi (IBSE:TOASO)
Overview: Tofas Türk Otomobil Fabrikasi Anonim Sirketi is involved in the manufacturing, exporting, and selling of passenger cars and light commercial vehicles in Turkey, with a market capitalization of TRY134.50 billion.
Operations: The company's revenue segments include Consumer Financing, generating TRY17.33 billion, and Trading of Spare Parts and Automobile, contributing TRY395.58 billion.
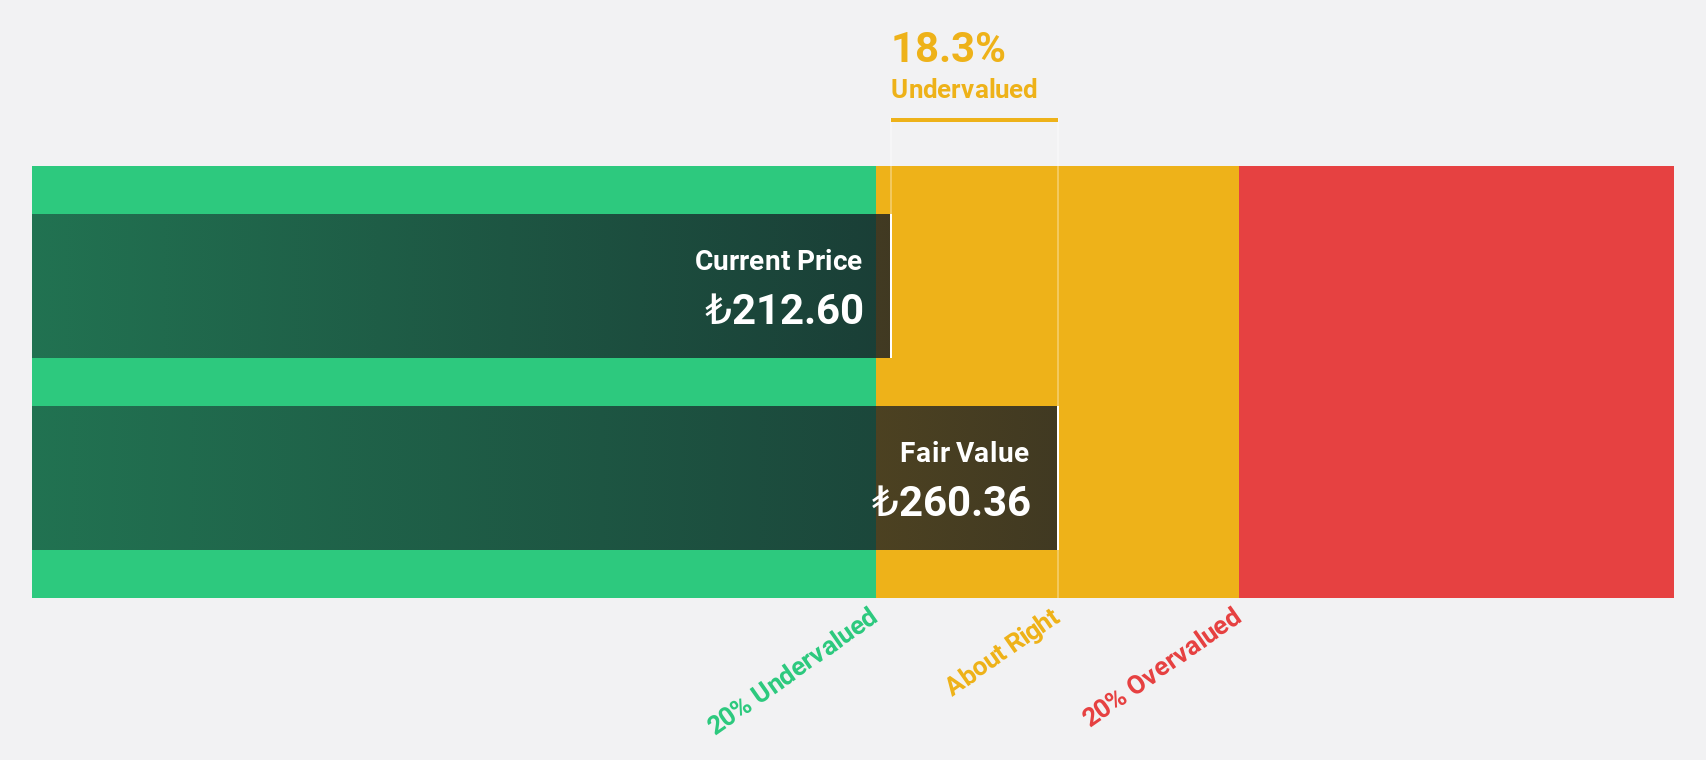
Estimated Discount To Fair Value: 30.3%
Tofas Türk Otomobil Fabrikasi Anonim Sirketi is trading at a substantial discount to its estimated fair value, with a price of TRY 269 against an estimated future cash flow value of TRY 385.7. Despite strong revenue growth forecasts of 33.3% annually, the dividend yield of 7.43% lacks coverage by free cash flows. The company reported robust earnings growth in the first half of 2026, supported by increased production and export market penetration, although debt coverage remains a concern.
- Our comprehensive growth report raises the possibility that Tofas Türk Otomobil Fabrikasi Anonim Sirketi is poised for substantial financial growth.
- Delve into the full analysis health report here for a deeper understanding of Tofas Türk Otomobil Fabrikasi Anonim Sirketi.
Monde Nissin (PSE:MONDE)
Overview: Monde Nissin Corporation is an investment holding company that manufactures and sells food products and beverages across the Philippines, Thailand, New Zealand, Singapore, the United Kingdom, and other international markets, with a market cap of ₱111.23 billion.
Operations: The company's revenue segments include Meat Alternative, generating ₱14.46 billion, and Asia-Pacific Branded Food and Beverage (APAC BFB), contributing ₱74.87 billion.
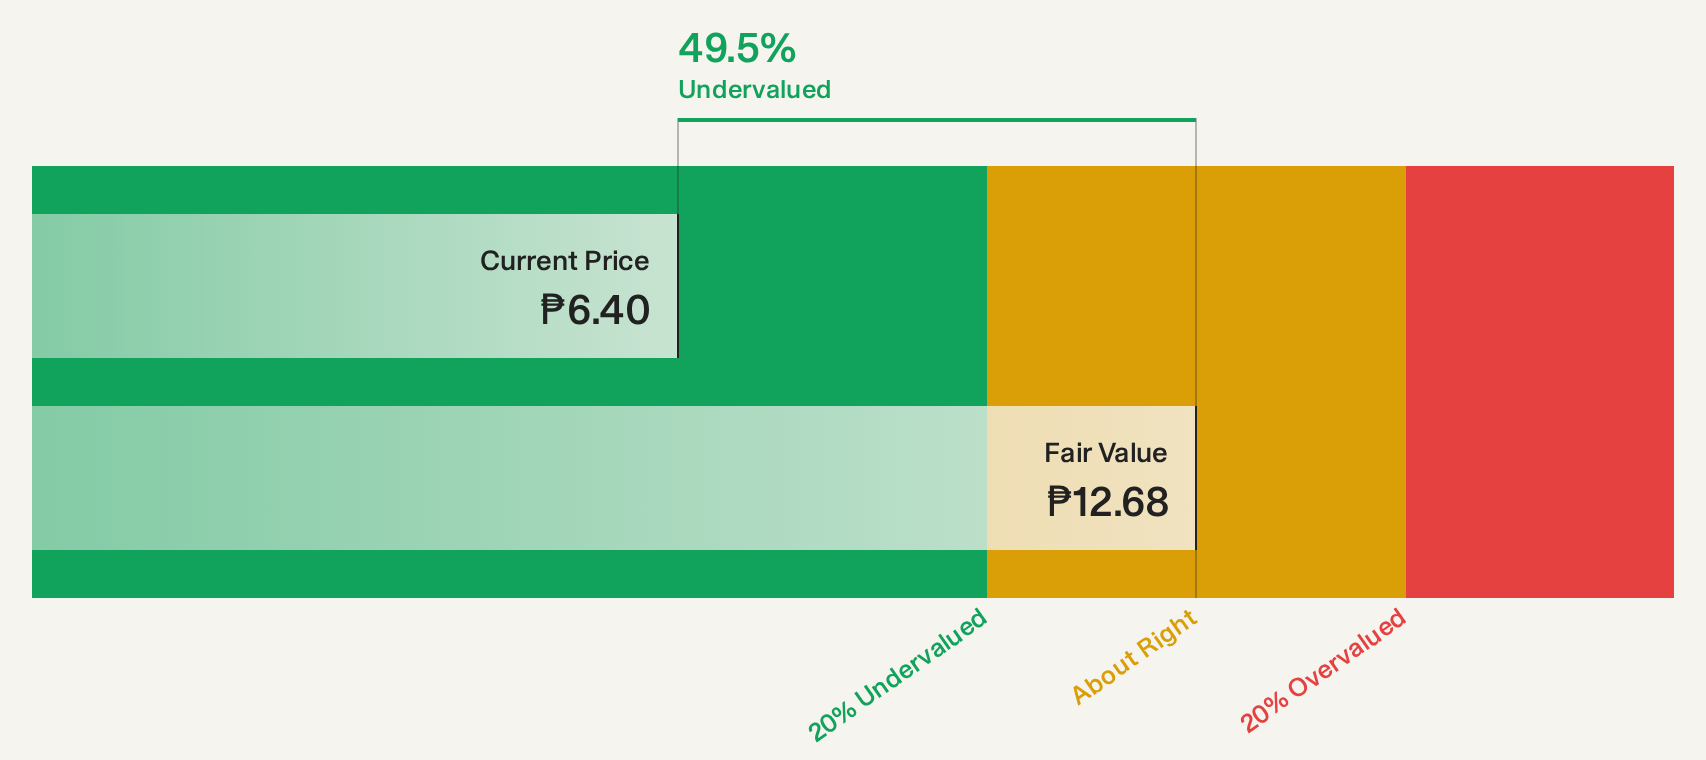
Estimated Discount To Fair Value: 49.5%
Monde Nissin is trading at ₱6.4, significantly below its estimated future cash flow value of ₱12.68, indicating potential undervaluation based on cash flows. Despite earnings growing by a very large margin over the past year, future growth forecasts are modest with annual profit and revenue expected to increase slower than the market averages. Recent results showed improved sales and net income for both the second quarter and first half of 2026, although dividend coverage remains weak.
- Upon reviewing our latest growth report, Monde Nissin's projected financial performance appears quite optimistic.
- Click to explore a detailed breakdown of our findings in Monde Nissin's balance sheet health report.
Philippine National Bank (PSE:PNB)
Overview: Philippine National Bank offers a range of banking and financial products and services, with a market cap of ₱112.60 billion.
Operations: The revenue segments include Treasury at ₱23.64 billion, Retail Banking at ₱29.76 billion, and Corporate Banking at ₱13.90 billion.
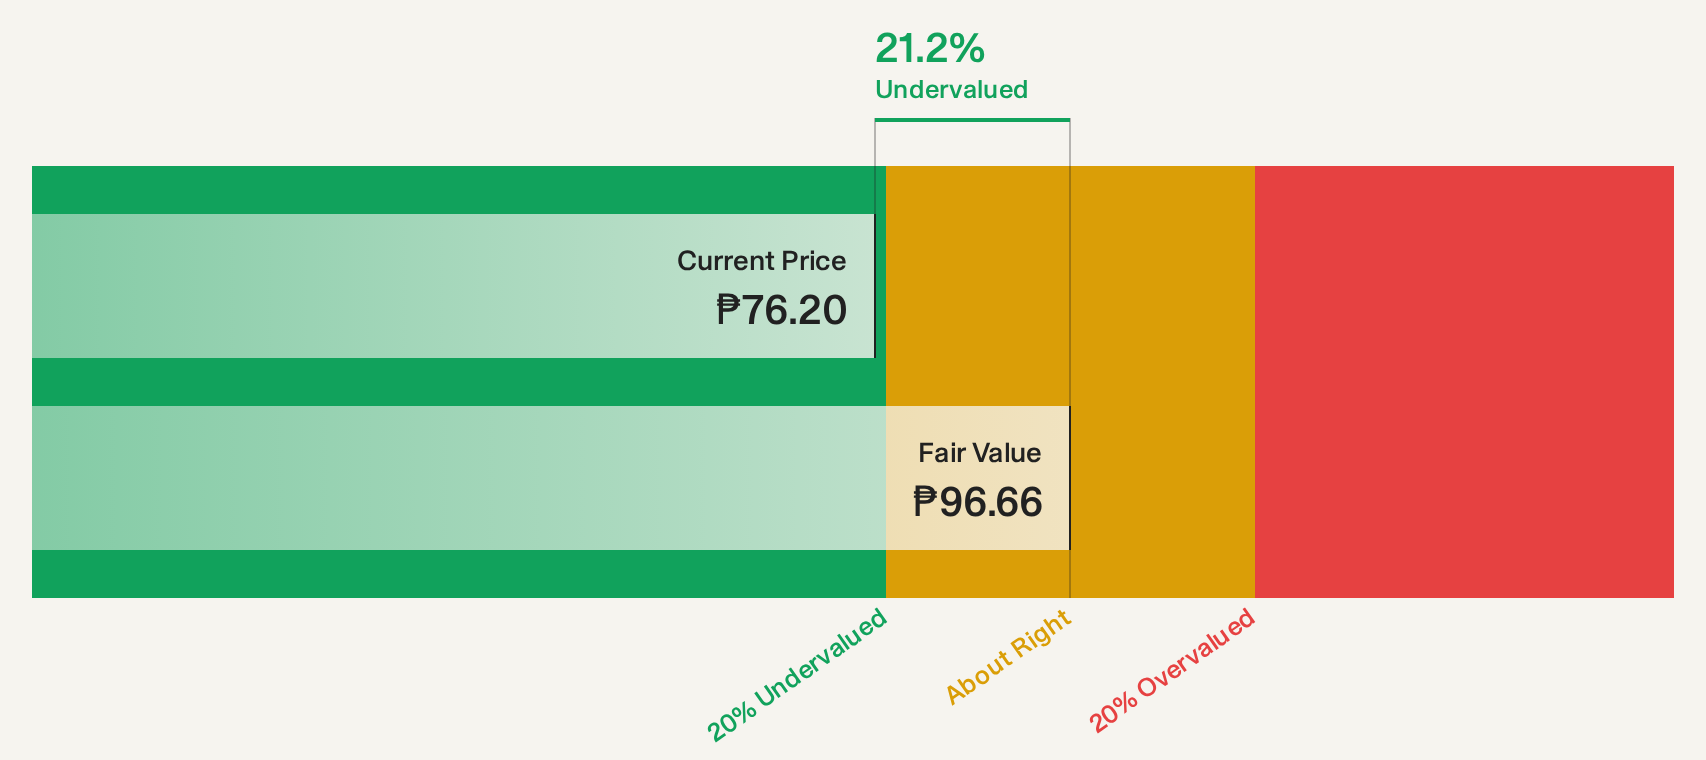
Estimated Discount To Fair Value: 21.2%
Philippine National Bank is trading at ₱76.2, below its estimated future cash flow value of ₱96.72, suggesting potential undervaluation based on cash flows. While earnings grew by 17.4% last year, future growth is modest with forecasts below market averages and a low return on equity expected in three years. Recent results showed improved net interest income and net income for the second quarter and first half of 2026, despite high bad loans and low allowances for them.
- The growth report we've compiled suggests that Philippine National Bank's future prospects could be on the up.
- Dive into the specifics of Philippine National Bank here with our thorough financial health report.
Turning Ideas Into Actions
- Discover the full array of 242 Undervalued Global Stocks Based On Cash Flows right here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com