
Discovering Undiscovered Gems in Global Stocks October 2026
As global markets navigate a landscape marked by mixed performance in major indices and persistent inflation concerns, investors are turning their attention to small-cap stocks that may offer unique opportunities. In this environment, discovering undiscovered gems requires identifying companies with strong fundamentals and growth potential that can thrive amid economic fluctuations.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Bastide Le Confort Médical | 263.37% | 2.00% | -22.93% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Framery Group Oyj (HLSE:FRAMERY)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Framery Group Oyj specializes in designing, manufacturing, and marketing soundproof private workspaces and related software solutions to address noise and privacy challenges in open offices across multiple regions worldwide, with a market capitalization of €506.79 million.
Operations: Revenue for Framery Group Oyj primarily comes from the Furniture & Fixtures segment, totaling €220.05 million. The company's financial performance is influenced by its ability to manage costs associated with designing and manufacturing soundproof workspaces.
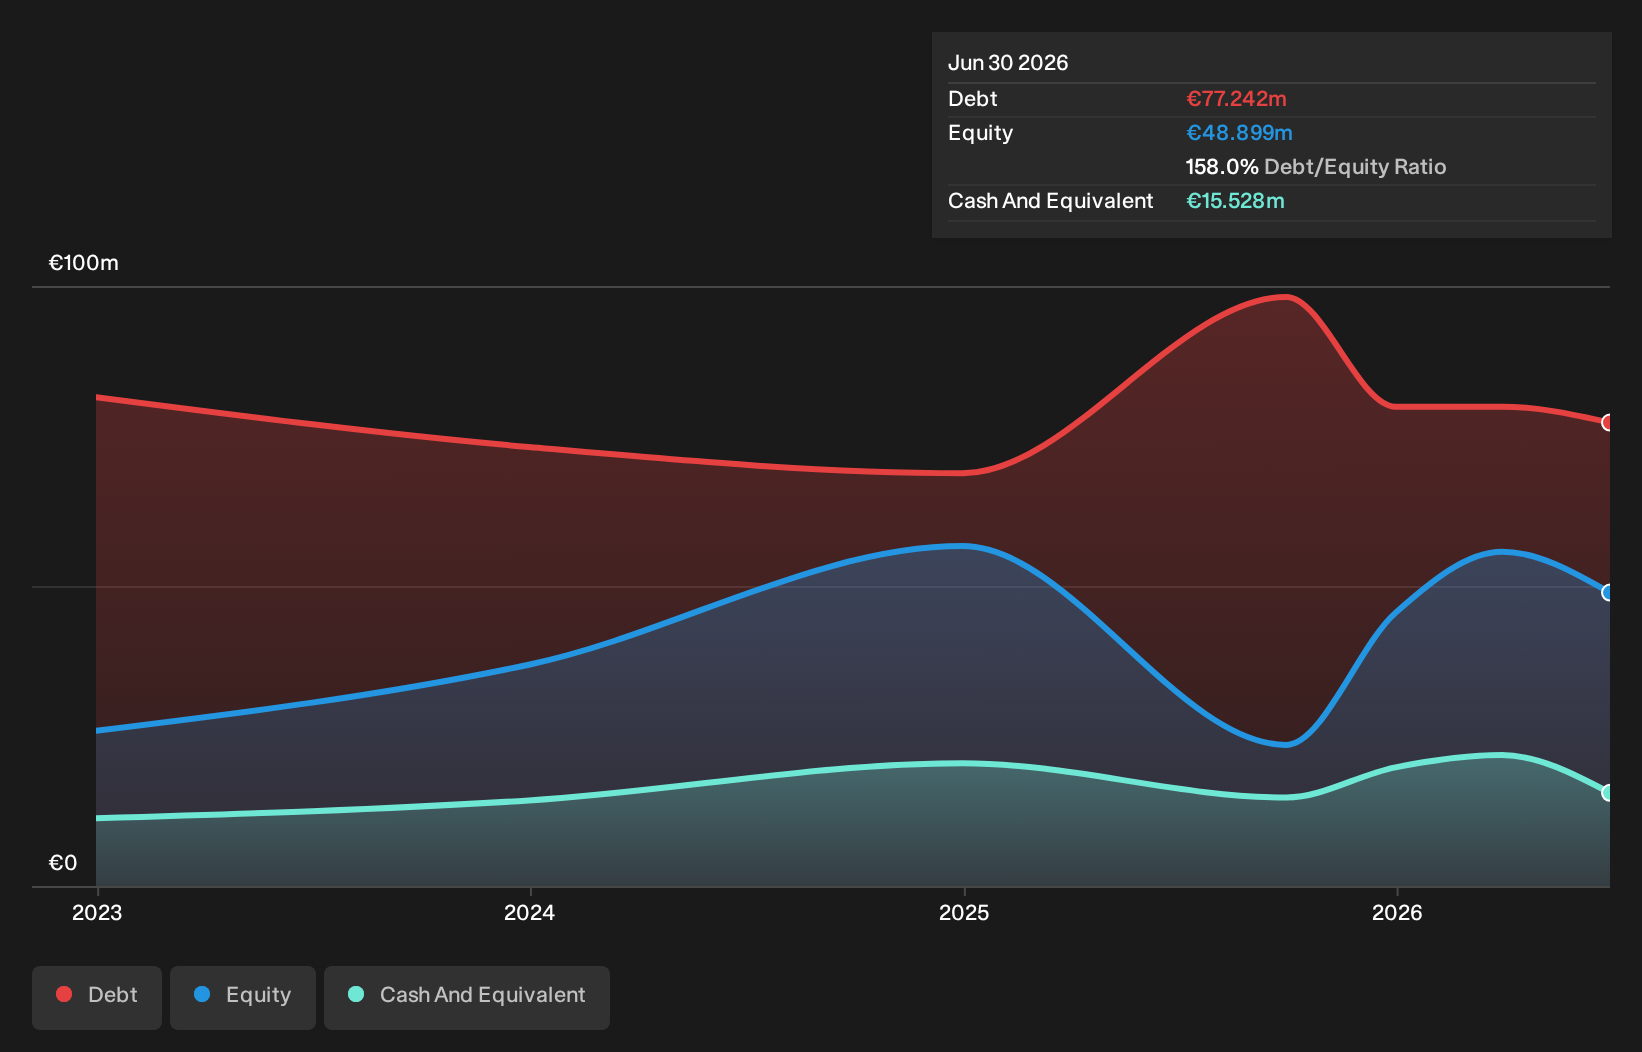
Framery Group Oyj, a promising player in the commercial services sector, showcases impressive earnings growth of 26.5% over the past year, outpacing industry averages. Despite a high net debt to equity ratio of 126.2%, their interest payments are well covered with EBIT at 4.9 times the interest repayments. Trading at nearly 60% below its estimated fair value presents potential for value seekers, although it's crucial to note their recent share repurchase program aimed at capital structure optimization and rewarding key personnel. With €11 million net income in Q2 2026 compared to €1 million previously, profitability remains robust despite challenges.
- Navigate through the intricacies of Framery Group Oyj with our comprehensive health report here.
Assess Framery Group Oyj's past performance with our detailed historical performance reports.
WONIK MaterialsLtd (KOSDAQ:A104830)
Simply Wall St Value Rating: ★★★★★☆
Overview: WONIK Materials Co., Ltd. specializes in the production and distribution of specialty gases across South Korea, China, and other international markets with a market capitalization of ₩516.93 billion.
Operations: The primary revenue stream for WONIK Materials comes from its Gas Sector, generating approximately ₩349.95 billion.
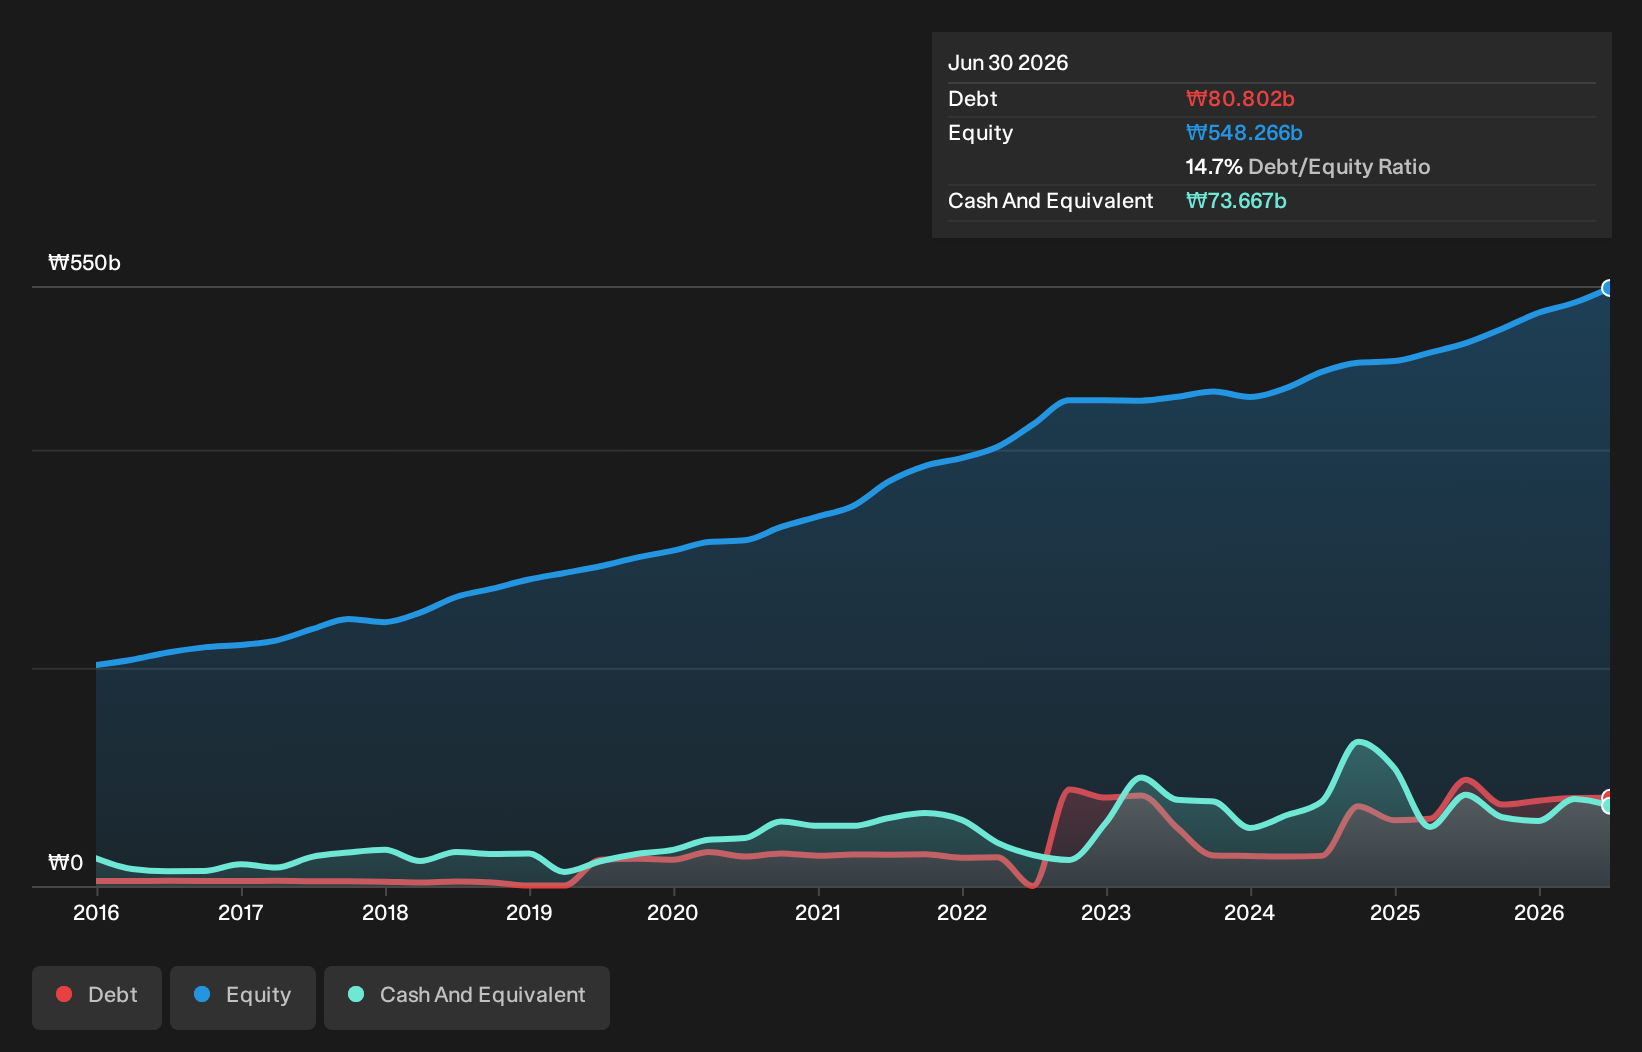
WONIK Materials shines with a net debt to equity ratio of 1.3%, which is comfortably low, indicating prudent financial management. The company reported a robust earnings growth of 76% over the past year, outpacing the Chemicals industry's 43%. Trading at an impressive 85.7% below its estimated fair value, it appears undervalued in the market. Recent results show sales climbing to KRW 92 billion from KRW 75 billion a year ago, while net income rose to KRW 13 billion from KRW 10 billion. These figures suggest strong operational performance and potential for continued growth in profitability and market presence.
- Take a closer look at WONIK MaterialsLtd's potential here in our health report.
Evaluate WONIK MaterialsLtd's historical performance by accessing our past performance report.
Zibuyu Group (SEHK:2420)
Simply Wall St Value Rating: ★★★★★☆
Overview: Zibuyu Group Limited is an investment holding company that functions as a cross-border e-commerce enterprise in China, serving markets in North America, Asia, Europe, and other international regions with a market capitalization of HK$2.52 billion.
Operations: Zibuyu Group generates revenue primarily from online retailers, amounting to CN¥5.53 billion. The company's market capitalization stands at HK$2.52 billion.
Zibuyu Group, a smaller player in the market, recently reported sales of CNY 2.83 billion for the first half of 2026, up from CNY 1.96 billion a year ago, with net income rising to CNY 137.67 million from CNY 105.91 million. The company seems to be trading at an attractive value compared to industry peers and has experienced significant earnings growth of 82.1% over the past year, outpacing the Specialty Retail industry average of 25.7%. With free cash flow turning positive and more cash than total debt on hand, Zibuyu's financial health appears robust as it continues leveraging AI for efficiency gains and expanding its global supply chain network.
- Get an in-depth perspective on Zibuyu Group's performance by reading our health report here.
Examine Zibuyu Group's past performance report to understand how it has performed in the past.

Taking Advantage
- Access the full spectrum of 162 Global Undiscovered Gems With Strong Fundamentals by clicking on this link.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com