
CoreWeave Heads 3 Top Growth Stocks With Insider Buying
As talk builds that US 10 year Treasury yields could reach 6% for the first time since 2000, investors are being paid more to sit in cash like assets. That pulls attention away from slower stories. It also shines a light on faster growing companies where management has serious skin in the game. This article highlights three such high growth, high insider ownership stocks from the US market.
The three stocks below are just a small sample. The full screen surfaced 183 more businesses with similarly strong growth stories and heavy insider ownership that are not covered here. To identify and analyze the highest conviction ideas that fit this theme, head straight to the Fast Growing Stocks With High Insider Ownership screener.
CoreWeave (CRWV)
Overview: CoreWeave runs a cloud platform that supplies GPU compute, AI development tools, and runtime services for large scale artificial intelligence workloads.
Operations: CoreWeave generates its US$7.59b of data processing revenue primarily in the United States at US$7.01b, with other regions contributing US$577m.
Market Cap: US$48.78b
CoreWeave matters for this screener because its AI infrastructure platform is tightly linked to real demand for GPU-heavy workloads. That growth story, however, leans on a funding model that only works if customers keep renting its capacity at scale.
"The financial structure is heavily weighted toward fixed debt and non-negotiable depreciation cycles. If major cloud providers internalize their compute capacity, CRWV faces a potential "stranded asset" risk with a high-interest debt burden that doesn't disappear when customers leave."
For investors watching CoreWeave, everything comes down to how one unseen pressure ultimately shapes pricing power and future margin potential.
That pressure point is exactly what the full narrative for CoreWeave unpacks, including where CoreWeave’s debt load could decouple from risk and keep upside alive.
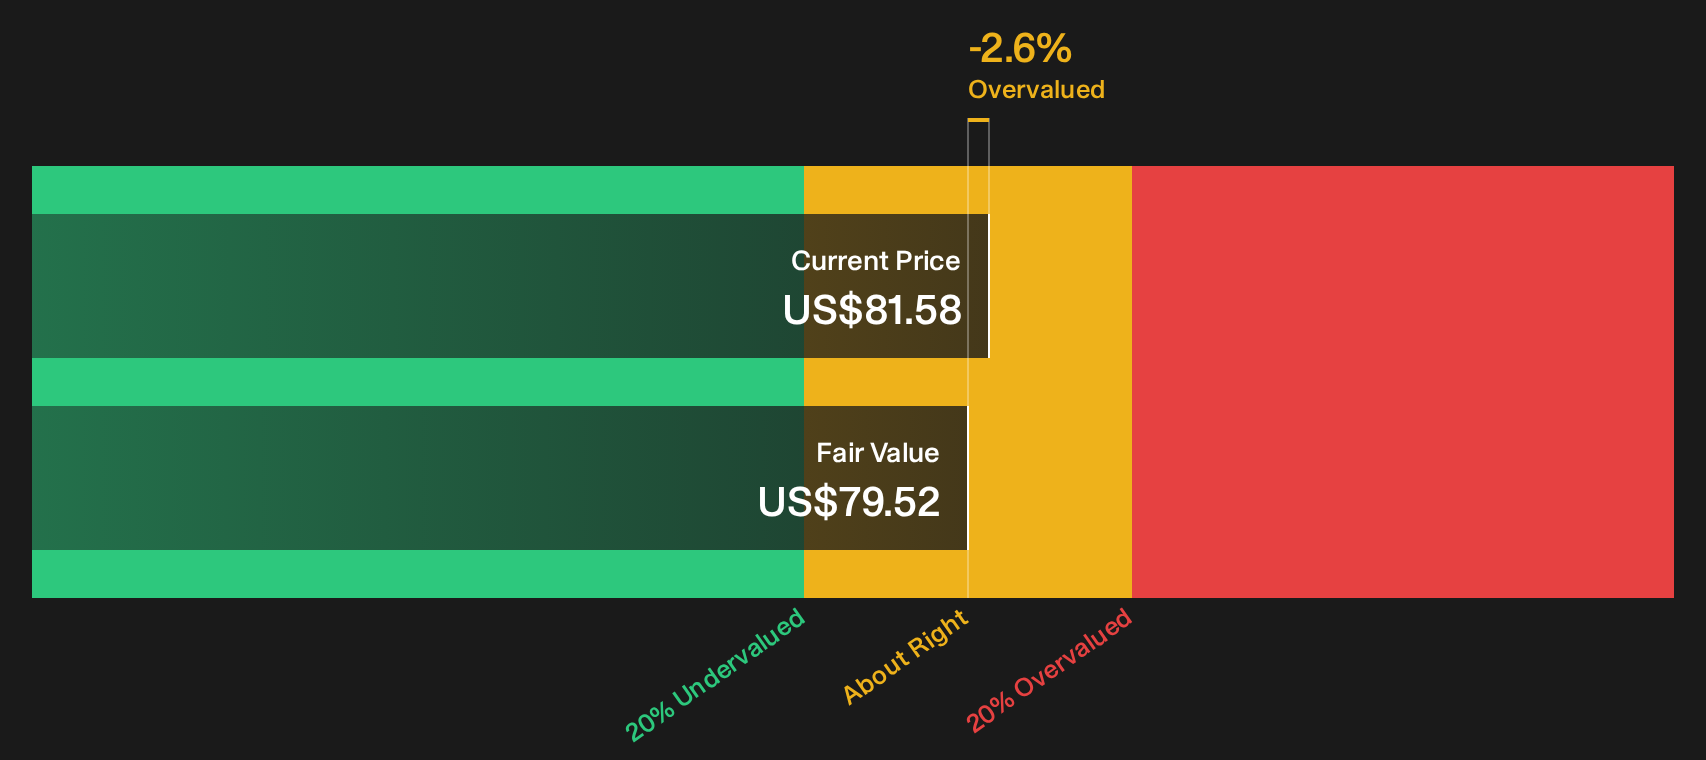
ERock (EROC)
Overview: ERock builds, installs, and runs modular natural gas power systems that provide data centers and industrial sites with reliable on site electricity.
Operations: ERock generates US$162 million of revenue from Electric Equipment in the United States, closely tied to distributed power projects.
Market Cap: US$3.53b
ERock is included in this screener because its modular, on site generation directly addresses demand from power intensive AI and data center facilities, and management has publicly indicated a strategy for faster expansion that corresponds with the high insider ownership signal.
"AI driven load growth and grid constraints are increasing demand for rapid, on site generation, and ERock's 1.7b contracted backlog and production capacity sold out through 2027 and into 2028 create visibility that can support future revenue and EBITDA as projects convert."
The key variable is how changes in future project timing and capital intensity may reshape both margin potential and the overall growth runway.
How that timing risk plays out is exactly what the full narrative for ERock unpacks, including where accelerating backlog conversion could reshape ERock’s long term earnings profile.

Tesla (TSLA)
Overview: Tesla designs and sells electric vehicles and related software, with energy generation and storage providing a sizeable but secondary revenue stream.
Operations: Tesla generates about US$90.82b from Automotive and US$12.8b from Energy Generation and Storage, with US$49.37b from the United States, US$21.21b from China, and US$33.04b from other international markets.
Market Cap: US$1,492.18b
Tesla matters for this fast growing, high insider ownership screen because its EV and software ecosystem gives analysts and management plenty of runway to point to, even as the energy and storage division quietly adds extra optionality on top of the headline automotive story.
"Tesla is pursuing a range of ambitious and, in some cases, speculative opportunities: AI leadership, robotaxis, humanoid robotics, and battery storage. While the company has achieved some success in energy storage, competition is intensifying there as well."
What really shapes the upside is how one unproven piece of that broader plan ultimately shows up in earnings power and cash generation.
That unproven pillar is exactly what the full narrative for Tesla lays out. It shows where Tesla's AI and robotics ambitions could accelerate or quietly reshape the whole earnings mix.

Seeking Alternatives Before The Crowd?
Fresh breakout stories can move quickly. Momentum can shift, prices can jump, and the cleanest entry points are often taken by early movers. Review these under the radar ideas to evaluate potential opportunities.
- Identify sturdy balance sheets before momentum traders arrive and review the curated list of solid balance sheet and fundamentals (25 results) that may still be reasonably priced for patient capital.
- Explore the next leg of the gold cycle by reviewing carefully filtered producers inside the 35 elite gold producer stocks while they remain less widely followed.
- Evaluate a potential electrification buildout and assess infrastructure players through the hand picked 43 power grid technology and infrastructure stocks before the trade becomes more crowded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com