
Flughafen Zürich (SWX:FHZN) Just Gave Investors Something To Think About
Recent Share Move Puts Flughafen Zürich Under The Microscope
Flughafen Zürich (SWX:FHZN) has drawn fresh attention after its share price closed at CHF 186.50 on 6 October 2026. The stock has been down over the past week, month and past 3 months.
The slide in Flughafen Zürich’s share price has not been a one day blip, with the stock down 5.0% over the past week and 10.5% over the last month, contributing to a 27.2% year to date share price decline. However, the 3 and 5 year total shareholder returns of 18.4% and 24.3% show that longer term holders have still seen gains. This suggests that recent weakness reflects a shift in sentiment around future prospects or perceived risk rather than the whole story on the business.
Scan how Flughafen Zürich compares with other airport and infrastructure operators by reviewing our hand picked list of solid balance sheet and fundamentals (206 results) in similar sectors.
With Flughafen Zürich down sharply this year yet still profitable and asset heavy, the key question is whether current levels already offer a reasonable entry or if patience could secure a more comfortable starting point.
Most Popular Narrative: 24.3% Undervalued
Against the last close of CHF186.50, the most followed narrative puts Flughafen Zürich’s fair value at CHF246.35, implying a sizeable valuation gap that investors now have to weigh against execution risks and capital needs.
Major capacity and infrastructure investments at Zurich (Dock A replacement, landside commercial expansion, new terminal projects), alongside international ventures (notably Noida Airport launching in late 2025 with a projected rapid passenger ramp up), are set to boost operational capacity, fee earning assets, and long term earnings diversification.
Uncover how 10 investors see Flughafen Zürich as 24% undervalued.
Result: Fair Value of CHF246.35 (UNDERVALUED)
Still, Flughafen Zürich’s story could be knocked off course if major capex projects overrun on cost, or if prolonged construction keeps squeezing commercial takings.
Find out about the key risks to this Flughafen Zürich narrative.
Another Take On Flughafen Zürich’s Value
The SWS DCF model paints a cooler picture than the analyst fair value of CHF 246.35. On those long term cash flow assumptions, Flughafen Zürich screens as overvalued at the current CHF 186.50, which raises a simple question: which set of expectations do you trust more, the earnings based target or the cash flow model?
For a closer look at how that cash flow view is built and what would need to change to shift it, Look into how the SWS DCF model arrives at its fair value.
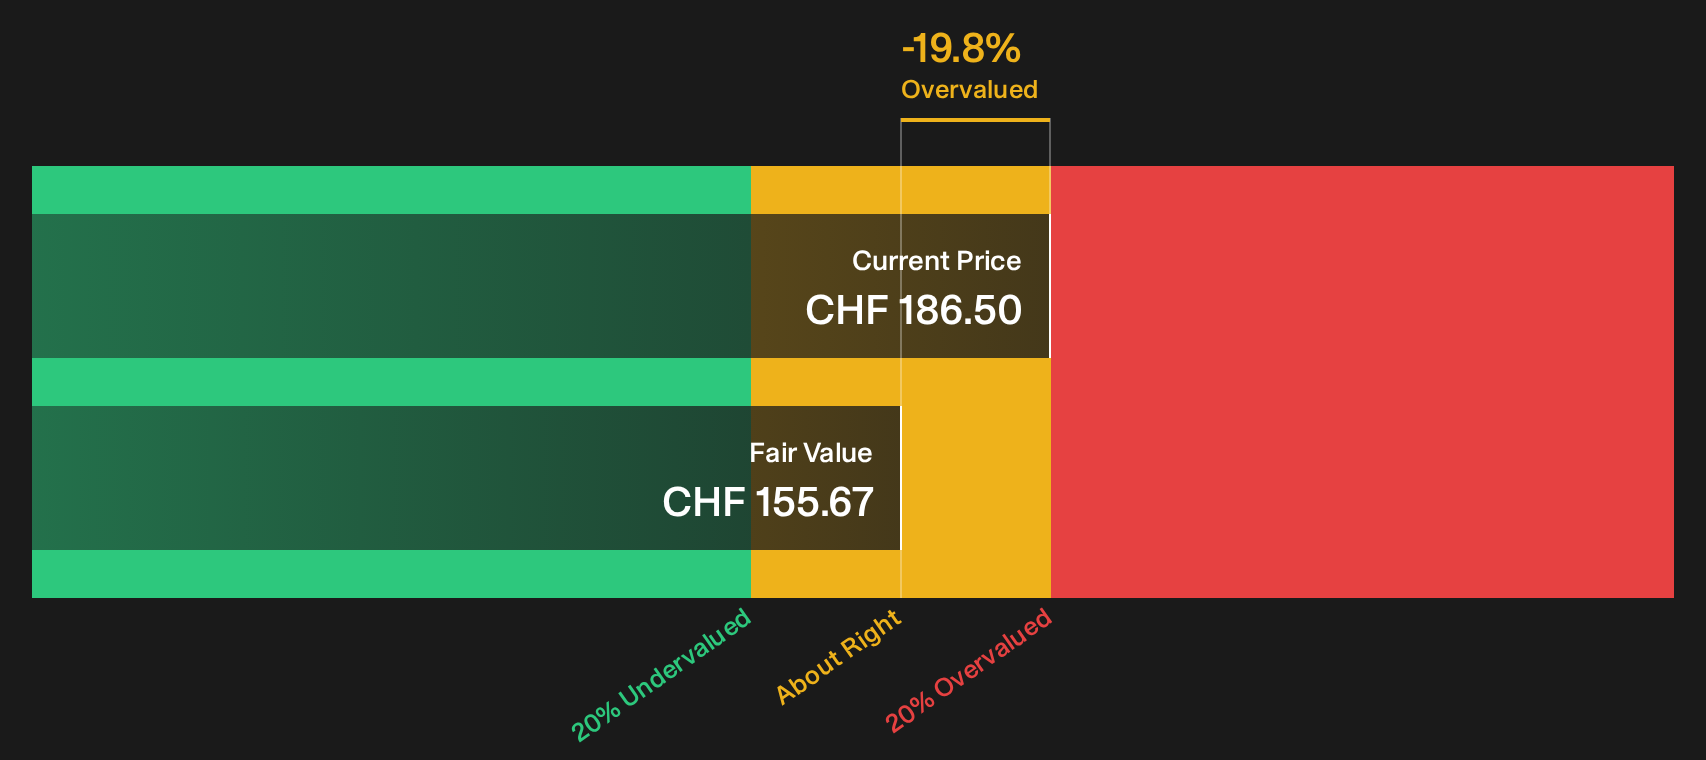
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Flughafen Zürich for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 177 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed messages on Flughafen Zürich leave you unsure, act quickly, review the data, and pressure test the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Flughafen Zürich?
Do not stop your research with one airport operator. Broaden your watchlist with other opportunities that fit your goals, risk tolerance, and income needs.
- Target resilient balance sheets and steadier financial profiles by scanning a 226 resilient stocks with low risk scores that filters for sturdier fundamentals.
- Hunt for mispriced potential by reviewing a curated 619 high quality undiscovered gems that highlights quality businesses the market may be overlooking.
- Strengthen your income plan by assessing a focused 225 dividend fortresses that surfaces higher yielding companies with the numbers to support those payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com