
Keurig Dr Pepper (KDP) Stock Could Be Overvalued Following Split CEO Appointment
Keurig Dr Pepper has delivered a solid 24.8% share price gain over the past year, and with the business reshaping itself around coffee and soft drinks, the core question now is whether that move is supported by its earnings power.
- The 24.8% one year return puts recent shareholders in a strong position. This raises the stakes on whether current earnings justify today’s valuation or simply reflect a hot streak in the stock.
- Management is integrating the large JDE Peet’s deal and preparing for a future split into separate coffee and beverage companies, which can reshape profit mix, capital needs and how investors think about the group’s earnings base.
- Your read on Keurig Dr Pepper is one view; the desks covering it have another. See what analysts think Keurig Dr Pepper's shares could be worth.
The issue now is whether Keurig Dr Pepper's current share price fairly reflects the earnings the business is generating today and is expected to produce over time.
To pressure test whether Keurig Dr Pepper's 24.8% one year return is backed by earnings strength, it helps to compare it with other consumer stocks screened for 27 high quality undervalued stocks
Does Keurig Dr Pepper Look Pricey on Earnings?
A P/E ratio fits Keurig Dr Pepper because earnings remain the main anchor investors use when weighing this kind of branded beverage group.
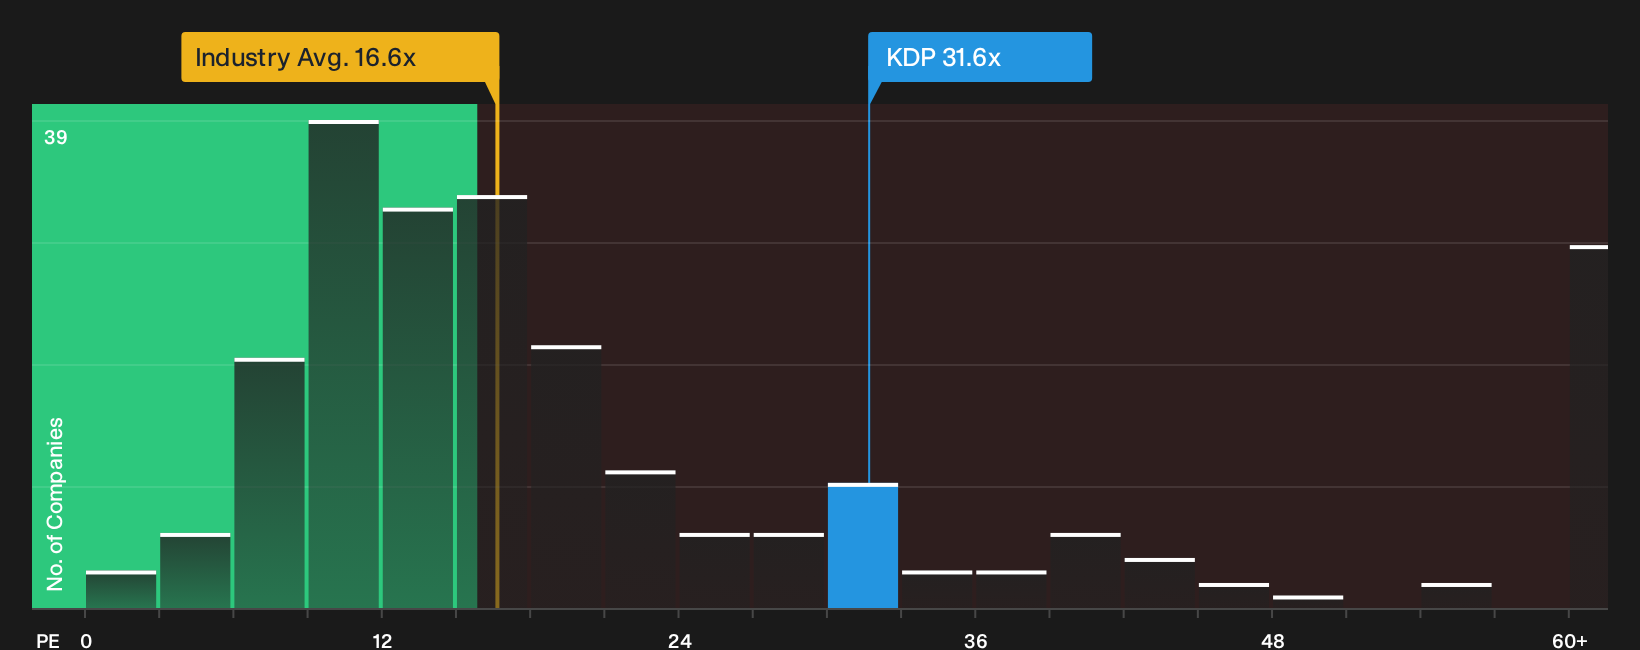
Right now the stock trades on roughly 31.6x earnings, which is well above the Beverage sector average of about 16.6x and also ahead of the peer group near 24.3x. The Fair Ratio model, which looks at factors such as growth profile, margins, size and risk, points to a lower multiple than where the shares trade today, so on this framework Keurig Dr Pepper screens as overvalued. Because the P/E already builds in a richer earnings tag than many beverage peers, buyers are paying a higher price for each dollar of profit.
Despite the lift from the JDE Peet’s acquisition and the planned split into separate coffee and soft drink businesses, the current P/E suggests the market has already priced in a lot of good news relative to sector norms. That leaves investors needing to judge whether future execution can justify a premium that screens above both the industry and this more tailored Fair Ratio yardstick. Explore the numbers behind Keurig Dr Pepper's P/E valuation.
The Keurig Dr Pepper Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the P/E puzzle leaves off for Keurig Dr Pepper, by explaining what kind of growth path, profit profile and earnings trajectory would need to occur for the shares to end up worth far more or materially less than they are today. Each narrative presents a fair value as a thesis about how the business might develop, so you can monitor over time whether the story holds up against new information.
One of the top community narratives on Keurig Dr Pepper: 14% undervalued
"The main thing that has to go right is that Keurig Dr Pepper continues to manage coffee cost volatility and U.S. Coffee volume headwinds..."
Discover why this Narrative puts Keurig Dr Pepper at 14% undervalued.
One more angle on Keurig Dr Pepper that could change how you see the stock
Everything so far has focused on what Keurig Dr Pepper earns today, but there is a separate lens in how professionals map out where profits might sit a few years from now. Explore where analysts expect Keurig Dr Pepper to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com