
What RB Global Stock's Leadership Reshuffle Means For Shareholders
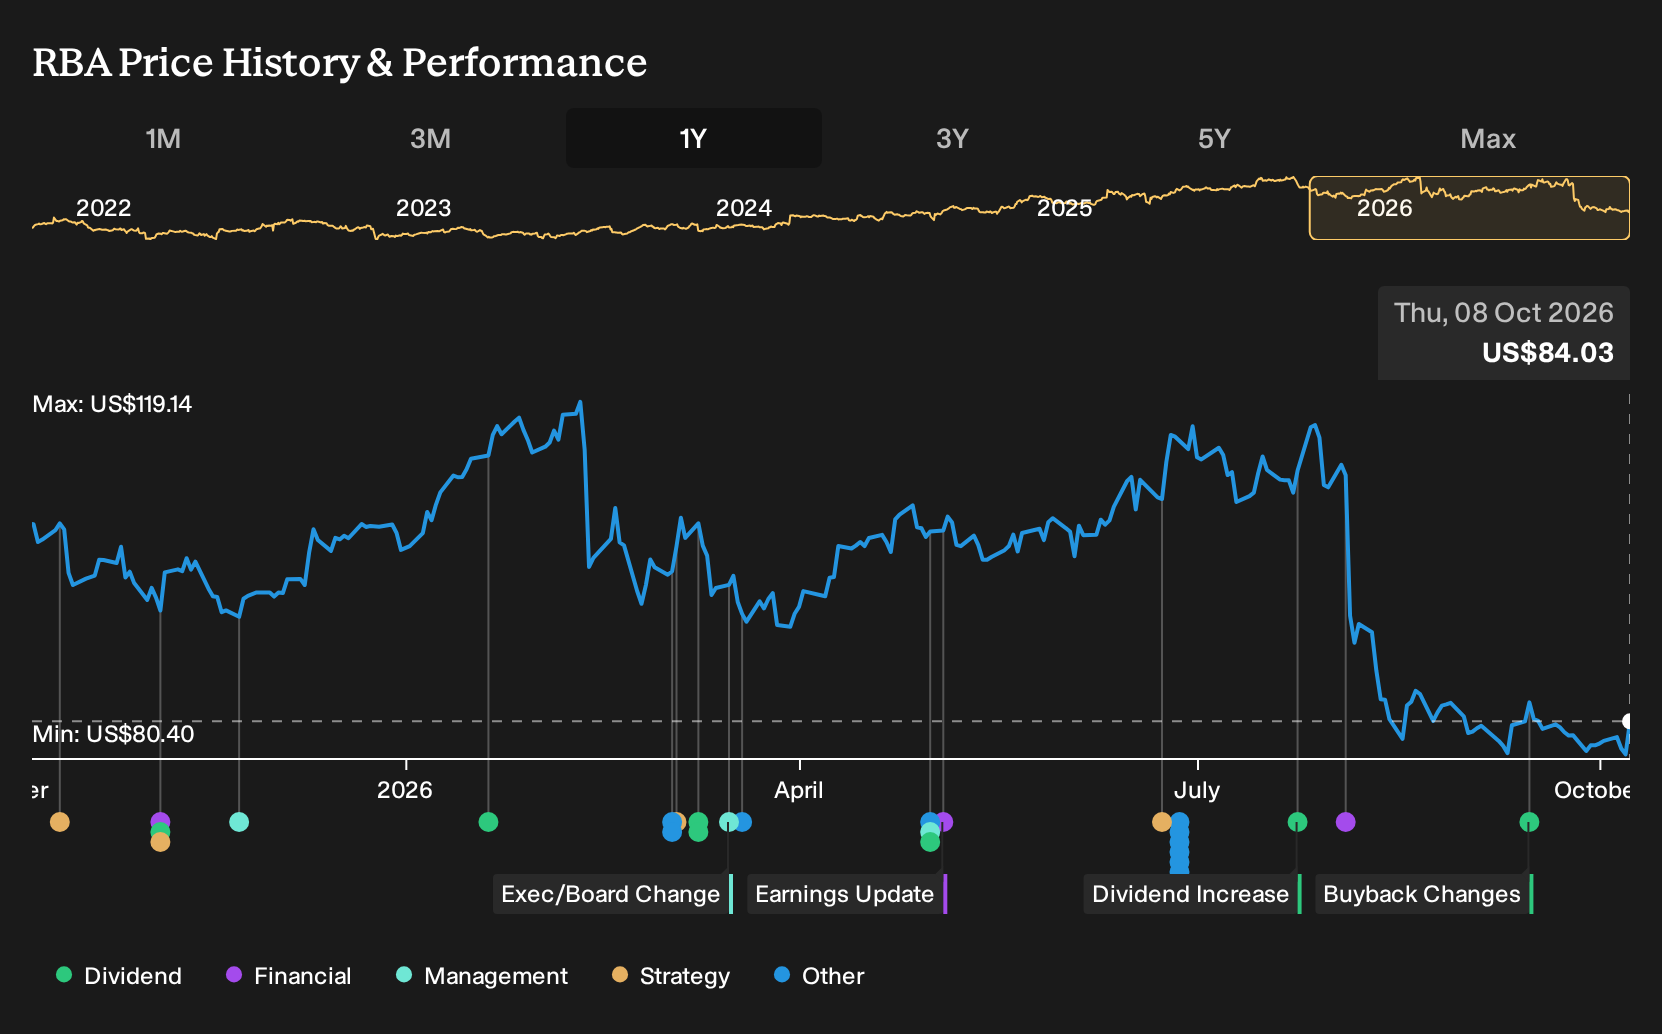
- RB Global promoted long time executive Steve Steinberg to Chief Financial Officer and elevated leaders across digital, heavy equipment, and auto units, while former CFO Eric Guerin and COO Steve Lewis departed, with management indicating that 2026 results are tracking toward the high end of prior guidance.
- The reshaped leadership team directly ties finance, digital strategy, and core marketplace operations together. This matters for how RB Global manages capital spending, pricing decisions, and execution on automotive and heavy equipment priorities.
- Now the focus shifts to how RB Global's refreshed leadership bench, including a new CFO, could reshape the existing investment narrative.
RB Global Investment Narrative Recap
To own RB Global, you need to believe its multi vertical marketplace model in heavy equipment, salvage autos and agriculture can keep pulling more transactions onto its platforms without sacrificing take rates too aggressively or letting higher costs overwhelm earnings. The near term swing factor is how well management turns planned US$350m to US$400m of annual capex and digital spend into usable tools that keep buyer engagement high.
The biggest current risk still sits in margin pressure. Service take rates have already compressed toward roughly 20%, while fuel and yard costs only partially pass through. The fresh leadership moves look important for execution quality but, on their own, do not materially change these core near term drivers.
The most relevant development for that story is the promotion of Shiv Dutt to Chief Digital and Strategy Officer, with direct responsibility for enterprise technology, digital roadmaps and M&A. RB Global is leaning heavily on online formats, mobile bidding and AI tools to keep buyer participation strong, which matters if service pricing stays tight.
Digital execution is now structurally tied to field operations in heavy equipment and autos, since Dutt continues to oversee Product and Engineering for the HE&T unit. That link will likely influence how effectively the group supports growth in salvage, international contracts and the BigIron agriculture platform while managing capex payback timelines and protecting free cash flow for dividends and buybacks.
RB Global's current analyst narrative points to about US$6.3b in revenue and US$946.3m in earnings by 2029, based on an assumed 9.1% yearly revenue growth rate and an earnings increase of roughly US$509.9m from US$436.4m today.
Uncover how RB Global's fair value indicates a 53% potential difference from its current price before sentiment around RB Global's new leadership recalibrates that gap.
Exploring Other Perspectives
One alternate view puts RB Global’s capital returns in the spotlight rather than margin pressure. The most optimistic analysts were already working off 2029 earnings of about US$980.9m and a P/E near 35x, higher than consensus assumptions. With a new CFO in place, you may see those bullish or cautious narratives shift again.
Explore 3 other RB Global fair value estimates, including one that suggests potential upside of up to 165% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RB Global research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RB Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RB Global's overall financial health at a glance.
Looking for more investment ideas beyond RB Global?
Once you have a view on RB Global, it can help to widen the lens and compare it with other opportunities that share similar qualities or offer a different risk profile. The Simply Wall St Screener can surface stocks that match the traits you care about most, whether that is value, balance sheet strength, or steadier risk characteristics.
- If you care most about paying a sensible price for quality, scan a focused set of 27 high quality undervalued stocks that combine robust fundamentals with more modest expectations baked into their valuations.
- For readers who want income to play a bigger role in returns, filter for companies in our 8 dividend fortresses and see which ones align with your tolerance for payout risk and sector exposure.
- If capital preservation is front of mind, narrow the field to a 31 resilient stocks with low risk scores that tend to have steadier balance sheets and business profiles, then decide which fit your own risk and return preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com