
Casey's General Stores (CASY) Leans Into Grocery, Is The Stock Still Cheap?
Casey's General Stores (CASY) is leaning harder into grocery and general merchandise after a fresh update on category trends, with management pointing to stronger beverage demand and value-focused offerings as key factors for the next phase.
Recent trading shows that sentiment around Casey's General Stores is mixed. The share price is down about 12% over the past month and 22% over 90 days. However, the year to date share price return of 15.46% and 1 year total shareholder return of 16.71% still point to positive momentum built over a longer stretch, supported by a very large 3 year total shareholder return of 144.5% and 5 year total shareholder return of 248.68% as investors weigh the latest inside sales guidance and category trends against earlier gains.
Spot opportunities beyond Casey's General Stores by scanning a curated group of value-focused retailers and consumer stocks through the 27 high quality undervalued stocks.The pullback in Casey's General Stores after a long stretch of strong returns raises a simple tension. Is this a reset driven by business fundamentals or a sentiment swing that has moved faster than the underlying results?
Most Popular Narrative: 19% Undervalued
Against a last close of $642.28, the most followed narrative pegs Casey's General Stores fair value at about $790.53. This frames the recent pullback as a potential gap between sentiment and modeled cash flows under a 7.24% discount rate.
Supply chain and procurement improvements (Fuel 3.0, self-distribution, vendor partnership funding on promotions) continue to lower cost of goods sold and optimize operating expenses, driving enhanced operating margins and earnings leverage. Progress toward converting and remodeling acquired stores for Casey's full food/kitchen model creates a future catalyst for gross margin expansion and synergy capture, with expected benefits becoming more pronounced in the following fiscal year and supporting multi-year EPS growth.
See why 23 investors see Casey's General Stores as 19% undervalued.
The same storyline assumes revenue growth of 5.9% a year and a profit margin near 4.4%, then applies a P/E of 36.5x to earnings of $979.7m by 2029 to arrive at that $790.53 mark. This sits materially above the current share price yet still below prior fair value estimates that were closer to $945.
Analysts in that framework model a slightly higher net margin, slower top line expansion, and a lower future multiple than before. The implied undervaluation therefore rests less on aggressive growth and more on Casey's General Stores executing consistently on integration, prepared foods, and its remodel program.
Result: Fair Value of $790.53 (UNDERVALUED)
Still, if fuel volumes weaken faster than expected or the CEFCO and ASAP store integrations drag on margins, the upside story for Casey's General Stores could fade quickly.
Find out about the key risks to this Casey's General Stores narrative.
Another View: Casey's General Stores Through The P/E Lens
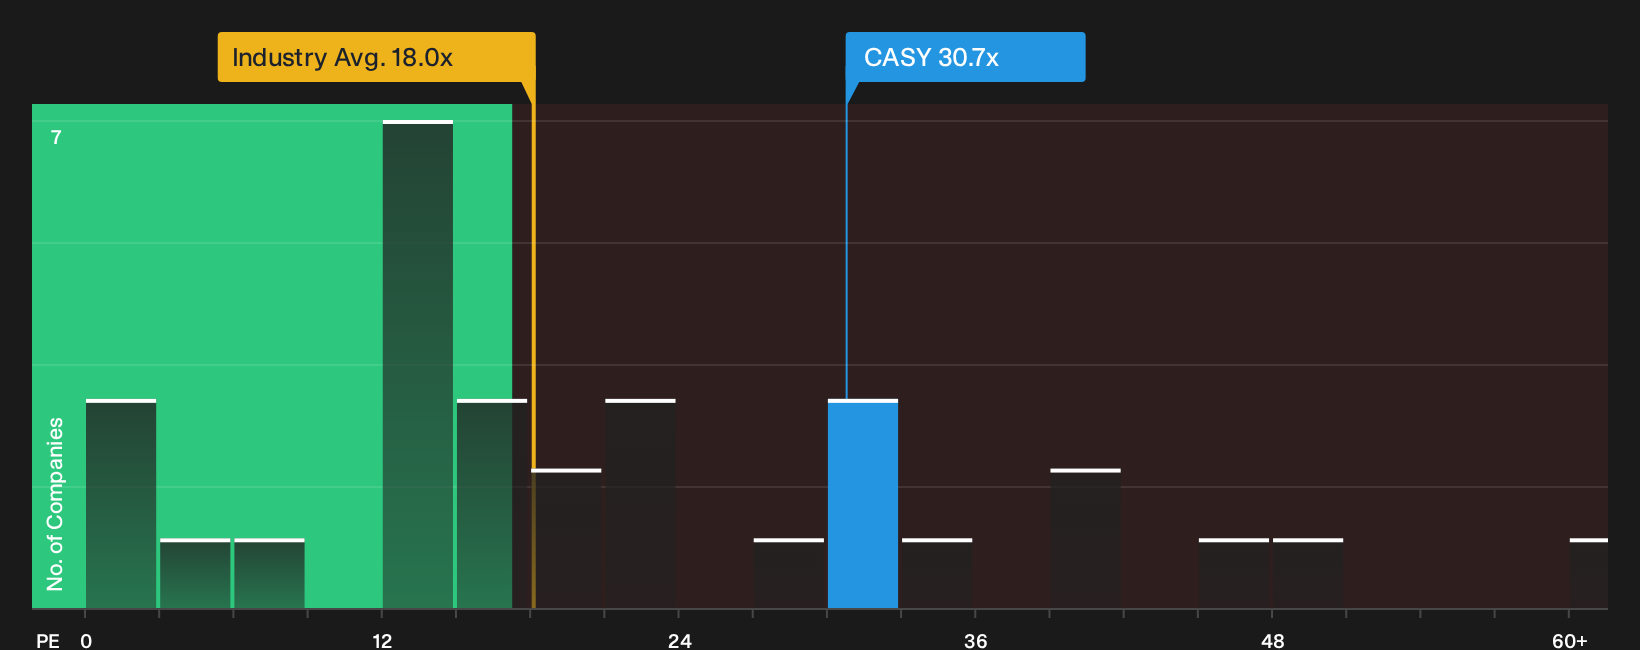
A different lens on Casey's General Stores comes from its P/E ratio of 30.7x. That sits well above the wider US Consumer Retailing group at 18x, yet below a peer average near 39.9x and above a fair ratio estimate of 23.6x that the market could gravitate toward over time.
This combination of a premium to the sector, a discount to close comparables, and a stretch versus the fair ratio points to valuation risk if growth cools, but also to possible upside if peers remain the key reference point. Which side of that trade off feels more realistic to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if they sharpen your own thinking. Move fast, test the assumptions yourself, and weigh the 4 key rewards and 2 important warning signs.
Ready For More Ideas Beyond Casey's General Stores?
If you stop with Casey's General Stores, you miss the chance to compare it with other potential opportunities that might fit your risk and return preferences even better.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that can anchor the more volatile parts of your portfolio.
- Hunt for mispriced quality by reviewing a focused 27 high quality undervalued stocks that filters for financial strength as well as potential upside.
- Build a stream of portfolio income by assessing a hand picked set of 8 dividend fortresses that combine higher yields with durable business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com