
Park Hotels And Resorts (PK) Stock Looks Reasonable Against Sales##
Park Hotels & Resorts has posted a strong multi year share price gain, which puts fresh attention on whether the current US$15.21 level is properly backed by its sales base. With investors also weighing recent balance sheet moves and analyst upgrades, the key issue is how much of the hotel owner's revenue power is already reflected in the valuation.
- Over the past 3 years the stock has returned about 79.1%, which raises the question of how closely that jump lines up with the underlying sales it produces.
- Management has repaid a US$1.275b loan tied to Hilton Hawaiian Village and refinanced other borrowings, which can reshape how much of Park Hotels & Resorts' revenue ultimately flows through to equity holders as interest costs and debt risk change.
- There is a second opinion on Park Hotels & Resorts worth weighing. See what analysts think Park Hotels & Resorts's shares could be worth.
The stock's next move may depend on whether Park Hotels & Resorts' current price can be squared with the sales it is expected to generate.
If you are weighing Park Hotels & Resorts against other opportunities that lean on sales power and balance sheet moves, it can help to line it up beside 27 high quality undervalued stocks.
Is Park Hotels & Resorts a Bargain on Sales?
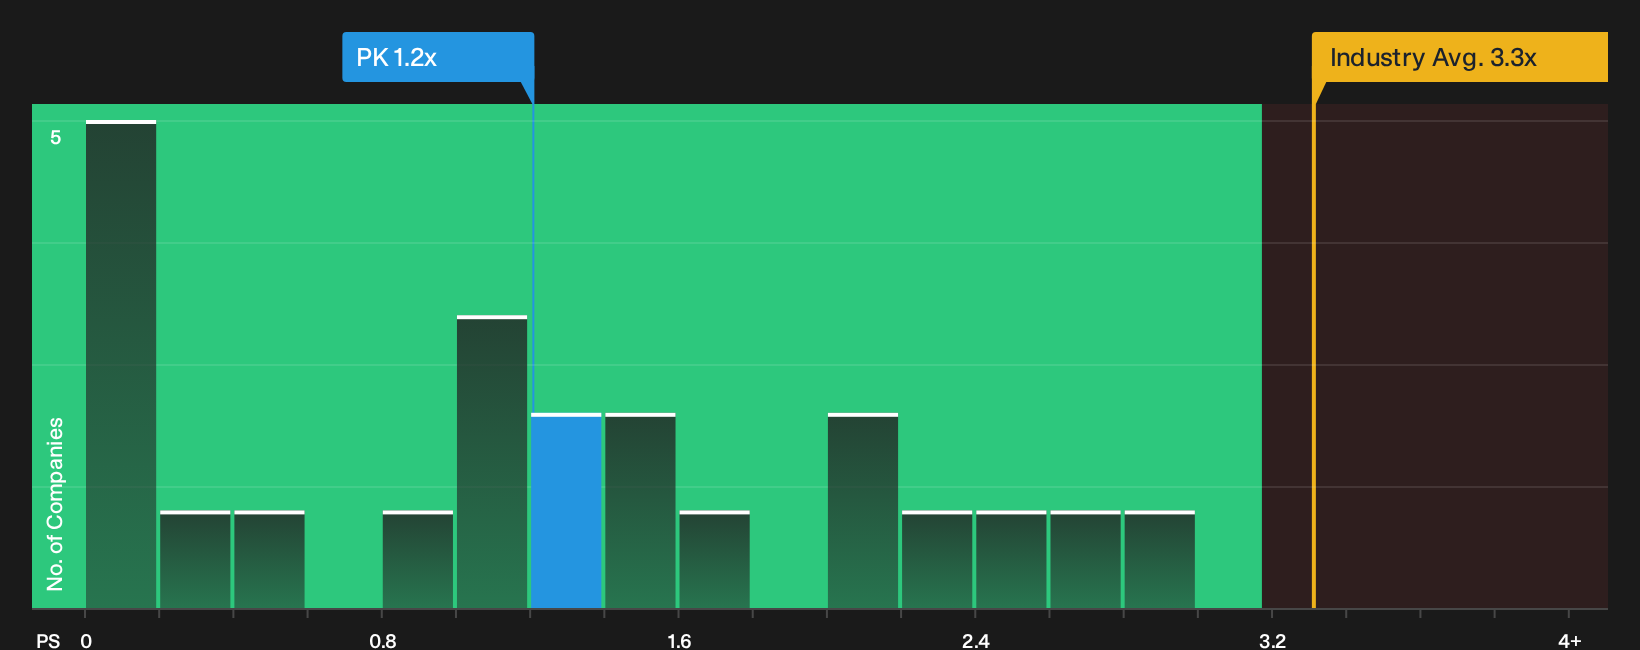
P/S works well for Park Hotels & Resorts because investors often look at what they are paying for each dollar of revenue in hotel REITs, where earnings can swing around financing and property level factors. On this yardstick, Park trades on a P/S of about 1.2x, which is below both the Hotel and Resort REITs industry average of roughly 3.3x and the peer group near 2.1x. Against the tailored fair P/S level implied by its own profile, the current ratio sits on the low side, which points to the shares screening as undervalued on this measure.
Because Raymond James recently upgraded Park to Strong Buy on expectations for stronger earnings around 2027, the fact that the P/S multiple still trails both sector norms and peer levels suggests sentiment has not fully closed that gap. For anyone comparing hotel REITs, the key question is whether the revenue base and balance sheet reshaping at Park Hotels & Resorts justify the current discount, or whether the multiple needs to move closer to that implied fair range before it looks more fully valued. Explore the numbers behind Park Hotels & Resorts's P/S valuation.
The Park Hotels & Resorts Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Park Hotels & Resorts valuation puzzle leaves off. They spell out which expectations on future sales, margins and earnings would need to hold for the shares to be worth materially more or less than today’s price on the Community page. Each one treats fair value as a thesis about Park Hotels & Resorts' business that you can track over time, rather than a single static estimate.
Community views on Park Hotels & Resorts split between those who see a cleaner, higher quality portfolio being underappreciated and those who worry that concentration and financing costs are being shrugged off.
Bull case: 5% undervalued
"Continuing portfolio reshaping at Park Hotels & Resorts, with 55 assets sold for more than US$3b and remaining non-core hotels now a small share of portfolio value, points to further mix shift toward higher RevPAR and higher margin core properties..."
Discover why this Narrative puts Park Hotels & Resorts at 5% undervalued.
Bear case: 38% overvalued
"Refinancing activity that repaid the large CMBS loan on Hilton Hawaiian Village and extended the weighted average debt maturity has come with guidance for a US$20 million to US$28 million increase in annualized interest expense..."
Explore why this Narrative puts Park Hotels & Resorts at 38% overvalued.
One more Park Hotels & Resorts checkpoint worth looking at
Before you file Park Hotels & Resorts away as simply cheap or expensive on sales, it helps to look at the specific risk flags our research has picked up and weigh what they might mean for you. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com