
General Electric (GE) Has Investors Asking A Bigger Question
General Electric (GE) is under fresh regulatory pressure after being referred to the Competition Tribunal over alleged anti-competitive practices in servicing medical imaging equipment, placing its aftermarket healthcare technology operations under closer scrutiny for investors.
Recent trading tells a mixed story for General Electric. The 30-day share price return is down 8.75% and the 90-day move is lower by 14.93%. Yet the 3-year total shareholder return of about 2.5x and 5-year total shareholder return nearing 4x point to powerful longer term momentum that shorter term weakness has not erased.
Spot potential alternatives to General Electric that are facing similar regulatory and aftermarket pressures by scanning our curated list of list of solid balance sheet and fundamentals (25 results).After a near 15% slide over 90 days, General Electric now trades at what looks like a discount to both analyst targets and intrinsic value estimates. Is that a genuine mispricing, or is the market correctly pricing in regulatory risk?
Most Popular Narrative: 40% Undervalued
General Electric last closed at $305.62, while the most followed narrative on the stock pegs fair value at about $307 and frames that level as roughly 40% below where the price could be in a fully rerated scenario, which is a big gap for any aviation heavyweight.
The long-term opportunity here is simply too big to ignore, but it is critical to be highly tactical about an entry point. Between the premium valuation and the messy aerospace supply chain, the stock is bound to face near-term turbulence. Rather than chasing the hype blindly at today''s hefty premium, building a position steadily on major pullbacks is presented as a way some investors attempt to manage risk while seeking long-term upside.
See why 32 investors see General Electric as 0% undervalued.
Result: Fair Value of $307 (UNDERVALUED)
Still, the bullish General Electric story collides with real threats, including Boeing production setbacks and any escalation of regulatory action on GE’s healthcare servicing practices.
Find out about the key risks to this General Electric narrative.
Another View: General Electric Through The P/E Lens
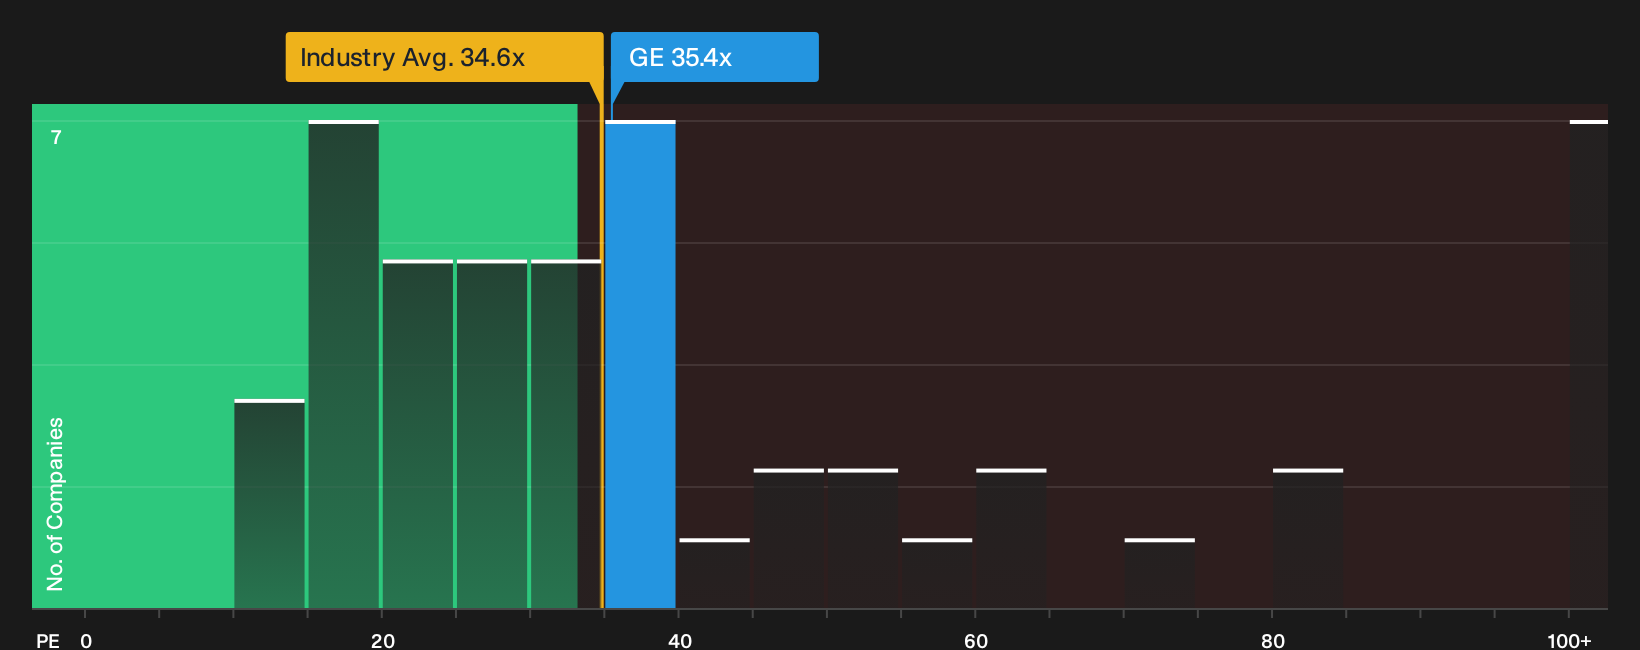
There is a different message when you look at General Electric through earnings multiples instead of fair value estimates. The stock trades on a P/E of 35.4x, slightly above both the US Aerospace & Defense average of 34.6x and its own fair ratio of 33.3x, which leans toward valuation risk rather than a clear bargain.
That kind of premium can reflect confidence in GE Aerospace's earnings quality and growth. However, it also gives less room for disappointment if forecasts or margins soften, so how much runway do you think is left for multiple expansion from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around General Electric's valuation and regulatory exposure create real debate. Move quickly, review the underlying data, and weigh both the upside and the downside for yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond General Electric?
If the General Electric story has you thinking about risk, value, and staying ahead of big shifts, do not stop with a single ticker. Use the Simply Wall Street Screener to compare different types of opportunities, cross-check your thesis, and avoid anchoring on just one stock when the data suggests better fits for your goals.
- Target resilient downside protection by scanning a focused universe of 31 resilient stocks with low risk scores that may help steady your portfolio when volatility spikes.
- Hunt for quality at a potential discount with our hand picked pool of 27 high quality undervalued stocks that combine solid fundamentals with pricing that some investors might overlook.
- Strengthen your income plan by reviewing yield focused picks in the 8 dividend fortresses that aim to pair robust payouts with business durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com