
What Does Bending Spoons (BSP) Being Picked For A $320 Million Fund Mean?
- Bending Spoons (NasdaqGS:BSP) was highlighted as a key portfolio company in Endeavor Catalyst's new Fund V.
- Endeavor Catalyst's Fund V totals $320 million and identifies Europe as the firm's fastest growing market.
- The fund's focus places Bending Spoons among a select group of high profile European technology companies backed by global investors.
- Being singled out in Endeavor Catalyst's $320 million Fund V only captures part of what is changing around Bending Spoons. We have also flagged 3 warning signs (1 major) for Bending Spoons.
For readers who want more ideas in this corner of the market, a natural next stop is 27 top founder-led companies.
Bending Spoons runs a portfolio of software and digital businesses across markets from the US to Europe, which gives this endorsement from a fund focused on European growth a direct link to its core operating footprint. For you as an investor, that cross-border reach is a key part of how the story around BSP is being framed today.
See how Bending Spoons's balance sheet measures up.
How does this new Endeavor Catalyst backing sit alongside Bending Spoons’ recent loan add ons?
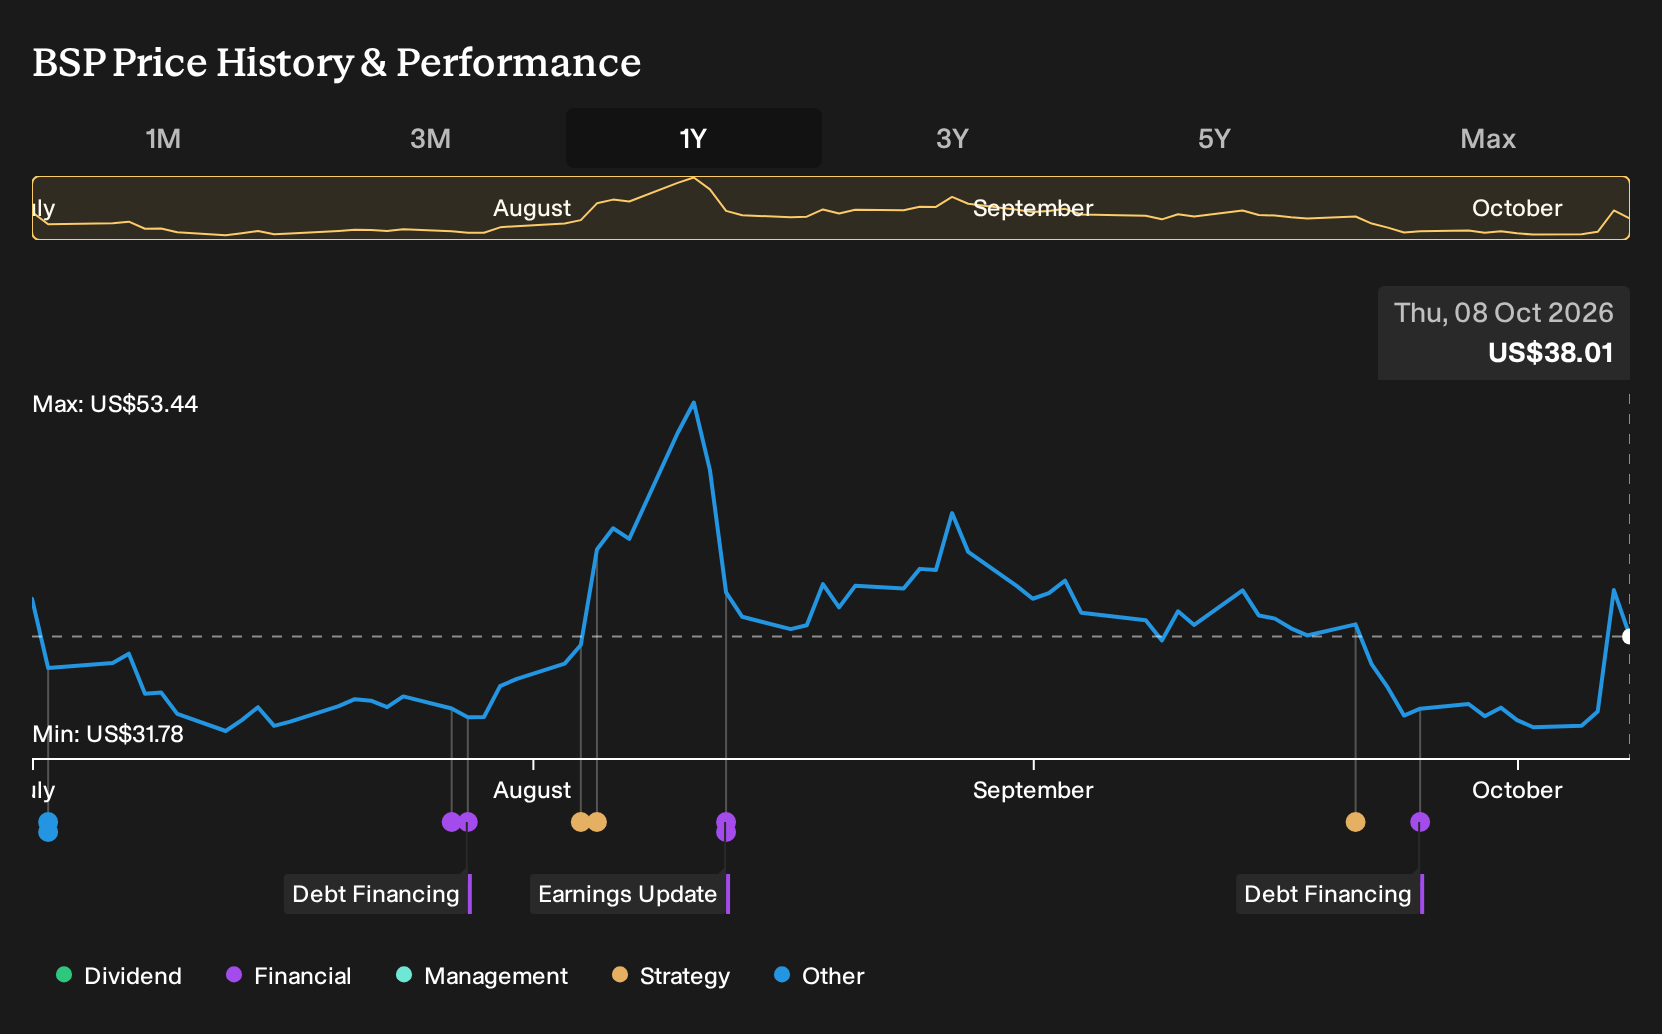
Endeavor Catalyst putting Bending Spoons in a short list of European portfolio companies lands just as the business prices a US$1.25b add on to its US dollar term loan B and a €395m add on to its euro term loan B, both due 2031. Equity investors and credit markets are supporting the same acquisition heavy playbook. This also means there is more leverage to monitor against future cash generation.
What does the term loan structure mean for Bending Spoons’ balance sheet and debt load?
The US dollar and euro term loan B add ons are fungible with existing tranches and share the 2031 maturity. As a result, Bending Spoons is layering extra secured debt onto an already leveraged model rather than shortening its repayment profile. With US$4.88b of long term borrowings and interest payments not well covered by earnings today, every new secured dollar tightens the interest coverage test you need to watch.
Does this news change the current Bending Spoons Narrative around growth via acquisitions and leverage?
The larger than targeted term loan B syndication directly supports the Narrative’s point that expanded access to term loans and revolving credit facilities can support ongoing M&A capacity, including deals like the Miro acquisition. At the same time, it amplifies the risk already flagged around a 2.4x leverage ratio and reliance on supportive credit markets to keep interest expense manageable.
See how these catalysts shape Bending Spoons' path to a $48.27 fair value.
What should you track next to see if this financing really pays off for Bending Spoons?
The key test is how the Miro deal and other acquired assets feed into earnings and free cash flow, relative to the heavier interest bill from the new loans over the next few reporting periods. Watch for updates on integration progress, any revised guidance for 2026 revenue or margins, and whether interest coverage metrics move closer to being comfortably covered by earnings.
One more thing Bending Spoons investors cannot ignore
All the headlines on funding and loans still leave out one crucial piece for you, which is what the stream of future cash moving through Bending Spoons suggests the entire business might be worth next to today’s share price. Find out exactly what Bending Spoons is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com