
Is First Merchants (FRME) Undervalued As CEO Succession And New Debt Reshape Its Outlook?
CEO transition and fresh debt issuance reshape the backdrop for First Merchants stock
First Merchants (FRME) has two clear inflection points in play. A planned CEO handover to Michael J. Stewart on January 1, 2027, and a recent US$100 million subordinated notes issue both color how you might think about the shares.
Recent returns underline that First Merchants has been more of a compounding story than a quick trade. The share price has delivered a year to date gain of 5.57% and a 3 year total shareholder return of 59.21%, even as the stock has drifted 3.84% lower over the past month and 8.14% over the past quarter. The current US$39.59 share price and 10.15% total shareholder return over one year suggest investors have been willing to reward the bank over time, while the softer near term share price performance around the CEO succession and new subordinated notes hints at some reassessment of growth prospects and risk.
Compare this CEO transition and new subordinated debt with peers by scanning our hand-picked list of solid balance sheet and fundamentals (25 results) that are also managing succession and capital structure with a focus on resilience.
First Merchants appears to be a solid Midwest banking franchise, supported by long-term shareholder returns and fresh capital in place for the next chapter. The real tension now lies in the price investors are paying today.
Most Popular Narrative: 16% Undervalued
On the narrative view, First Merchants carries a fair value of $47 against a $39.59 share price, which points to a gap investors need to judge for themselves. The story rests on whether the bank can translate its Midwest footprint, balance sheet remix and capital plans into the earnings path that narrative outlines.
Rapid migration and economic growth in core Midwest markets is fueling strong, broad-based loan demand, now reflected in nearly 6% annualized commercial and consumer loan growth in Q2 2026 within the three state footprint. This supports the view that First Merchants can continue to grow revenue as these regional trends play through.
See why 3 investors see First Merchants as 16% undervalued.
Result: Fair Value of $47 (UNDERVALUED)
Still, the story for First Merchants can change quickly if credit issues broaden beyond the recent US$33m provision spike, or if the higher cost 6.75% subordinated notes drag more heavily on earnings power.
Find out about the key risks to this First Merchants narrative.
Another View: What First Merchants’ P/E Is Telling You
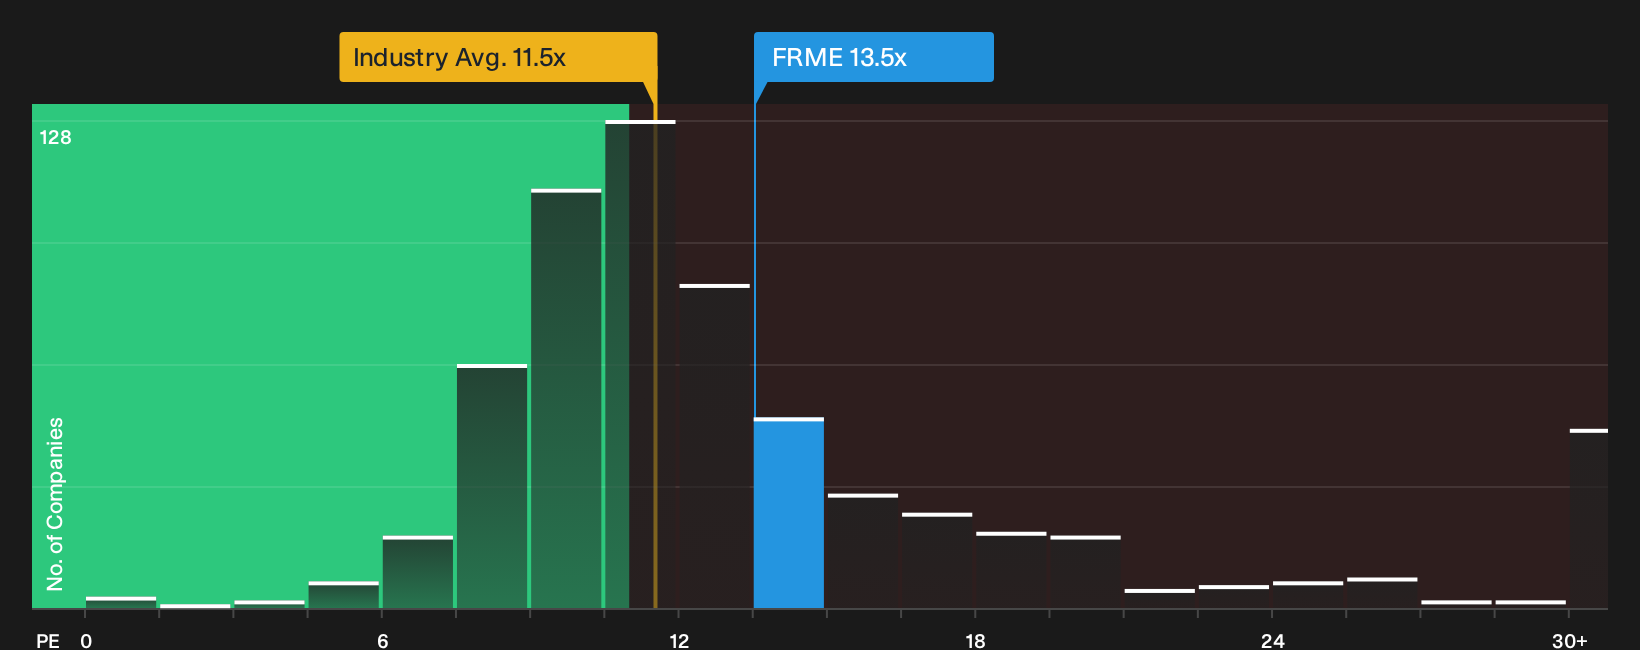
There is a catch. On earnings multiples, First Merchants trades on a P/E of 13.5x, which is higher than both the US Banks industry at 11.4x and a peer average of 12.9x, even though the fair ratio is 14.3x. That gap points to real valuation risk if expectations slip, but also some room if the market leans toward the fair ratio.
If you want to stress test that earnings based view against a fuller valuation picture, take a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on First Merchants so far. If you want to move fast and judge the trade off yourself, start by weighing its 3 key rewards.
Looking for more investment ideas beyond First Merchants?
If First Merchants has you thinking more carefully about price, risk and balance sheets, widening your opportunity set with a few targeted screeners can sharpen your next move.
- Spot potential value plays early by scanning the 27 high quality undervalued stocks that already combine quality fundamentals with a price that still looks reasonable.
- Strengthen the income side of your portfolio by checking out the 8 dividend fortresses that aim to pair higher yields with resilient cash flows.
- Sleep easier through market swings by focusing on the 31 resilient stocks with low risk scores that score well on financial strength and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com