
Will Dividend Growth Outlook Change Kimco Realty (KIM) Narrative
- Kimco Realty recently attracted attention as a dividend stock with a 5.06% yield, a five year pattern of regular dividend increases, and management commentary pointing to earnings strength in fiscal 2026 as support for ongoing payouts.
- The combination of an above average yield and a history of dividend growth positions Kimco Realty as a case study in how income focused real estate owners can align capital allocation, earnings power, and investor demand for reliable cash returns.
- We will look at how Kimco Realty's investment narrative is influenced by its dividend profile, which remains ahead of industry and market averages.
Compare Kimco Realty's income profile with a curated 8 dividend fortresses that is built around consistent payouts and higher-than-average yields.
Kimco Realty Investment Narrative Recap
To own Kimco Realty, you need to be comfortable with a REIT that focuses on grocery anchored centers, a sizeable signed but not open rent pipeline, and a dividend policy that currently offers a 5.06% yield. The recent emphasis on dividend growth is tied to expectations for earnings strength in fiscal 2026, which management has described as a key support for distributions.
The most important short term swing factor remains execution on leasing and redevelopment that converts the signed pipeline into cash flow, while interest costs and legal issues remain in the background. Rising refinancing costs on 2026 debt and the tenant lawsuit are still the biggest operational risks, and the latest dividend commentary does not materially change that picture.
The key new piece of information is the clarified dividend profile. Kimco Realty has raised its payout five times in five years, with an average annual increase of 14.37%, and now offers a 5.06% yield that stands above both its industry and the S&P 500 averages. Management has linked this track record to expected earnings strength in fiscal 2026 as an important underpinning.
This matters because the overall rental income story, including about US$95 million of signed but not open annual base rent, is most relevant for income-focused investors if it translates into durable funds from operations that comfortably cover interest and distributions. With interest expenses identified as a pressure point and a lawsuit that could add to costs, the announced dividend profile serves as a real time test of how effectively the business can balance refinancing, capital recycling, and cash returns to shareholders.
Kimco Realty Analyst Assumptions Behind the Dividend Story
Income investors looking at Kimco Realty's payout often want to know how the underlying earnings profile lines up with the current dividend approach. Analyst assumptions give a sense of how much financial headroom might be available if the business follows the path currently mapped out in consensus models.
On the top line, analysts are working with revenue growth assumptions of 3.4% a year over the next three years, paired with a slight margin squeeze from 26.2% today to 25.7% by around 2029. That combination points to a scenario where rental income rises gradually while profitability edges down, which matters for a real estate owner that pays out a large share of funds from operations as dividends.
Earnings expectations sit at the center of this view. Consensus calls for earnings to move from US$573.8 million today to US$621.3 million by 2029, largely in agreement across covering analysts. That is an increase of about US$47.5 million, which is modest in headline terms but still meaningful when investors are scrutinizing coverage ratios for a 5.06% yield and watching interest costs and legal expenses for any signs of pressure.
Valuation assumptions reflect this earnings path. The stock would need to trade at a P/E of 35.8x on those forecast 2029 earnings, up from 26.4x today and above the current 26.3x P/E for the US Retail REITs industry, to match the consensus price target. That gap highlights that analyst targets rely not only on the forecast profit pool but also on investors being willing to pay a richer multiple for Kimco Realty's portfolio and dividend characteristics.
Kimco Realty's narrative projects US$2.4b revenue and US$621.3 million earnings by 2029. This is built on 3.4% yearly revenue growth and an earnings increase of about US$47.5 million from US$573.8 million today.
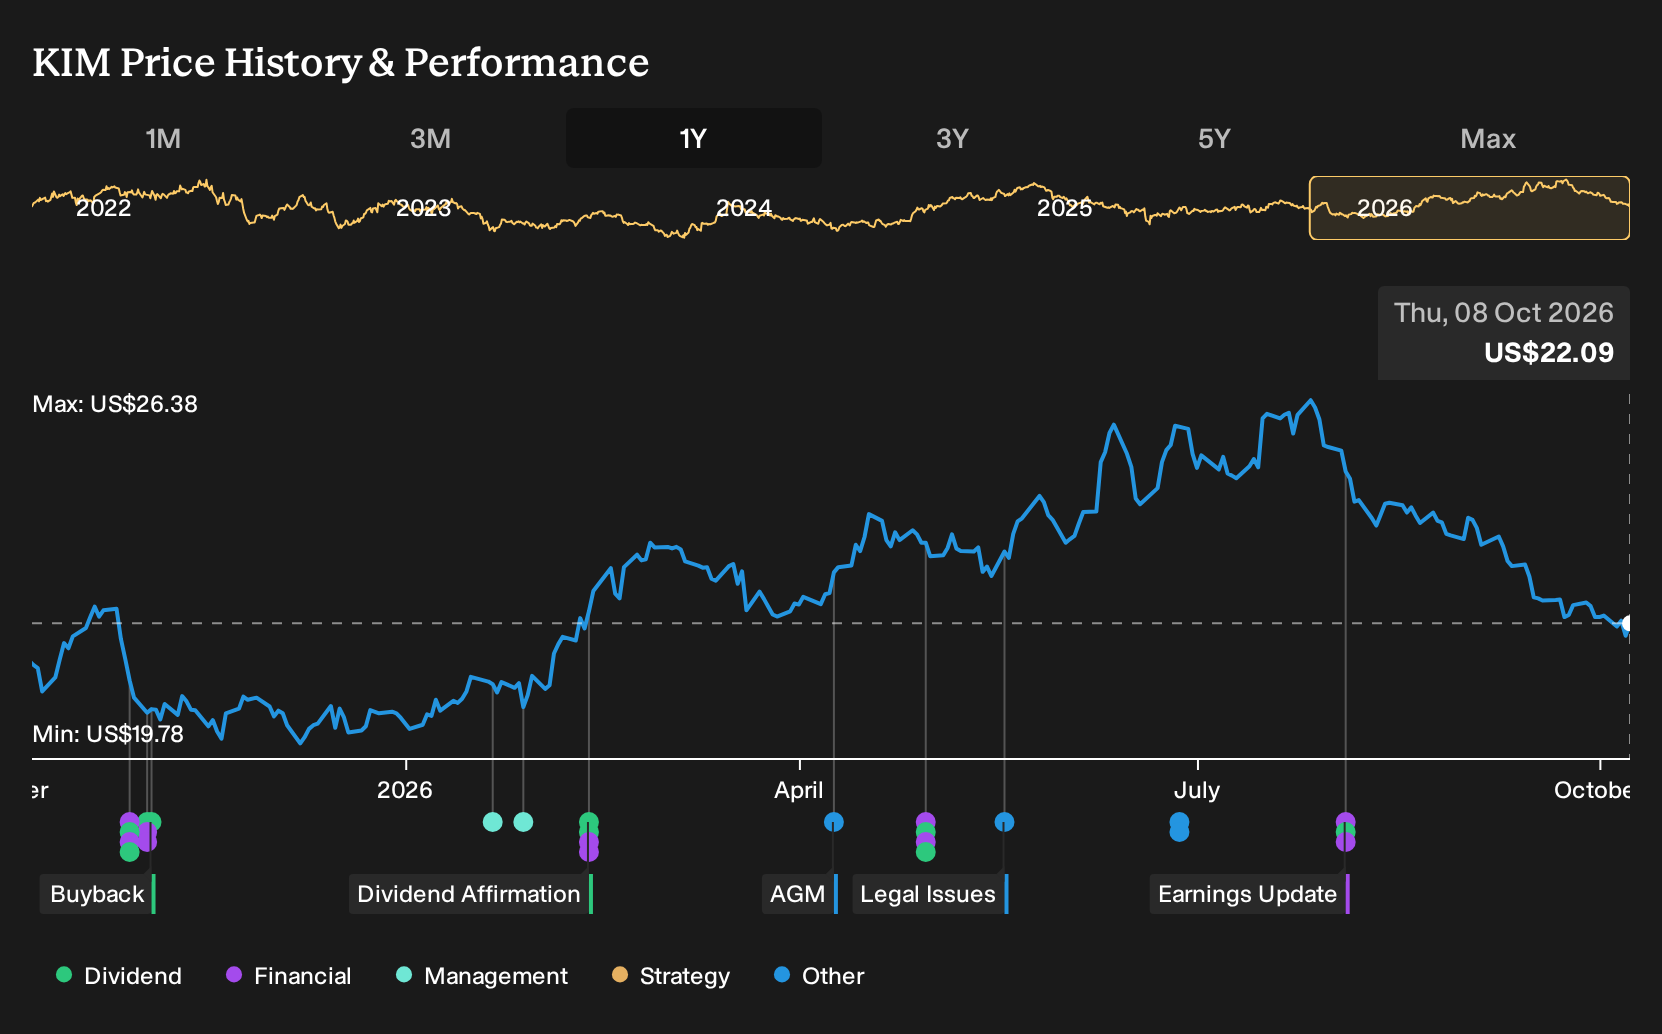
Uncover how Kimco Realty's fair value indicates a 22% potential upside to its current price, which could narrow quickly if sentiment shifts toward Kimco Realty.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$26.92 and US$32.91 a share, which already shows how far opinions on Kimco Realty can stretch. Set those crowd views against refinancing risk on 2026 debt and the tenant lawsuit, and you can see why investor takes diverge so sharply. Explore several of these viewpoints before forming your own stance.
Explore another Kimco Realty fair value estimate, including one that suggests it could be worth just $26.92!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kimco Realty research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kimco Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kimco Realty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kimco Realty?
If Kimco Realty's income story has your attention, it can be useful to compare it with other opportunities that line up with your own risk tolerance and return goals. The Simply Wall St Screener is built for exactly that kind of side by side check.
- If income stability matters most to you, look at a 8 dividend fortresses that focuses on consistent payouts and yields that sit above the market.
- If you want to keep risk in check, filter for a 31 resilient stocks with low risk scores that scores well on balance sheet strength and volatility.
- If you are hunting for less crowded ideas, scan a 20 high quality undiscovered gems that highlights companies with solid fundamentals that are still under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com