
J. M. Smucker (SJM) Stock Climbed, What Is Behind The Fresh Attention?
J. M. Smucker (SJM) just rolled out a fresh wave of fall themed products across Hostess, Milk-Bone, and Uncrustables. These seasonal launches highlight how its brands focus on limited time offerings.
Recent trading suggests investors are warming to J. M. Smucker again, with a 3% 1-day share price return and a 7% 90-day share price gain. This is despite the 30-day share price return declining 4.21% and the 1-year total shareholder return sitting at 18.27%, which signals momentum that has picked up over the course of the year.
Scan other consumer brands that lean on seasonal demand with a hand picked set of 20 high quality undiscovered gems that, like J. M. Smucker, use limited time offerings to keep shoppers engaged.
J. M. Smucker now trades at a sizeable discount to both analyst targets and estimated fair value after its recent rebound. Is the gap signaling opportunity, or is the market still pricing in real risks?
Most Popular Narrative: 16% Undervalued
J. M. Smucker’s most followed narrative pegs fair value at $142.13, above the recent $119.41 close. This frames the current discount as a call to examine how the business converts its brands into cash over time.
The main factor that has to go right is that J. M. Smucker converts momentum in core growth brands and ongoing cost discipline into sustained free cash flow around the current US$1.1 billion level while it continues to deleverage and manage the Hostess turnaround.
Sustained free cash flow around the US$1.1b to US$1.2b level, combined with leverage already at about 2.9x net debt to EBITDA, gives J. M. Smucker additional flexibility to keep reducing interest expense, consider future buybacks or reinvest behind high return brands. This can support future EPS growth.
See why 16 investors see J. M. Smucker as 16% undervalued.
Result: Fair Value of $142.13 (UNDERVALUED)
Still, the J. M. Smucker story depends on two pressure points not getting worse: softer FY27 sales guidance and the slow repair job in Sweet Baked Snacks.
Find out about the key risks to this J. M. Smucker narrative.
Another View: What J. M. Smucker’s P/E Is Telling You
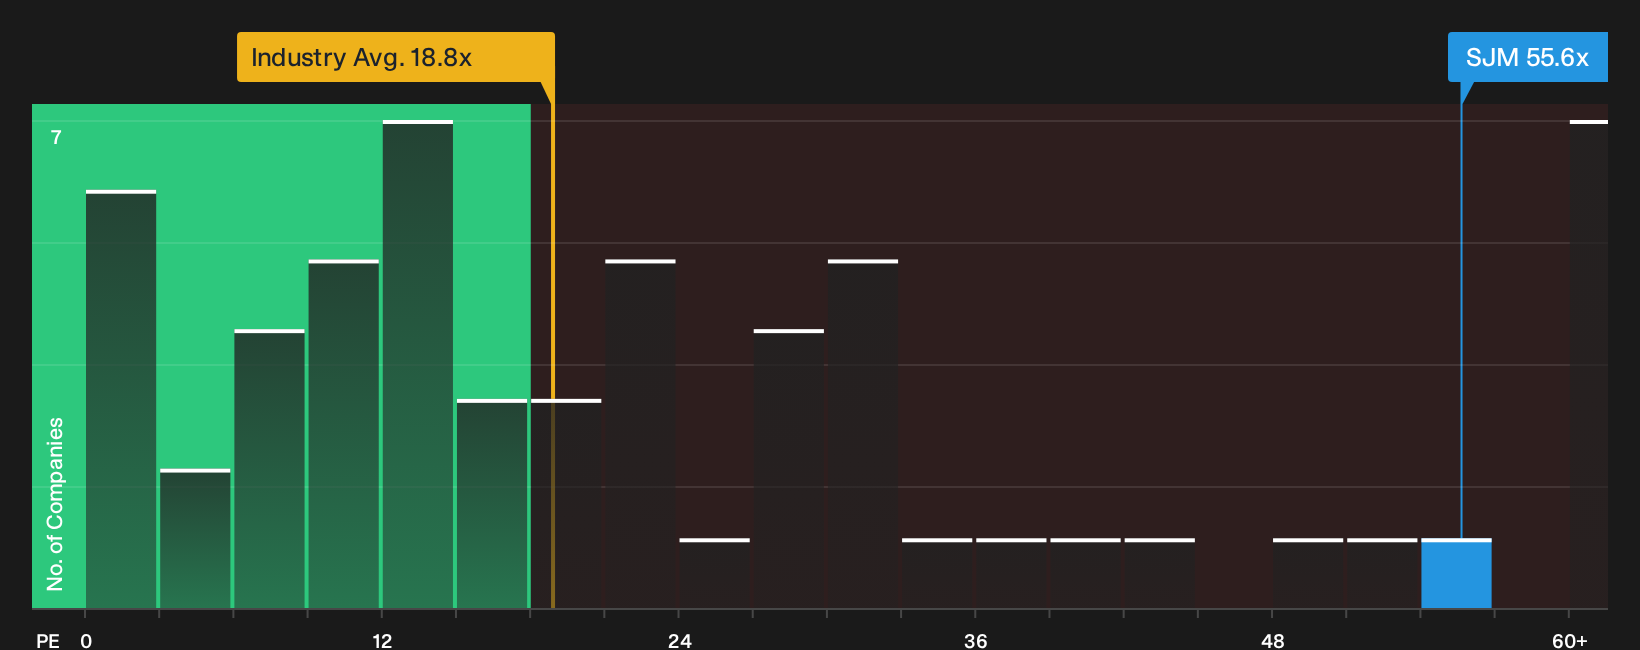
The SWS DCF model points to J. M. Smucker trading well below an estimated future cash flow value of $268.06, yet the current P/E of 55.6x is far higher than the US Food industry at 17.9x, the peer average at 20.9x, and the fair ratio of 24.2x. That gap suggests investors need to weigh rich earnings multiples against a model that signals undervaluation and decide which risk matters more for them.
To pressure test how that earnings multiple might evolve if sentiment or results shift, take a closer look at the valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
For a visual read on how J. M. Smucker’s current valuation stacks up against sector peers, review the latest relative P/E snapshot in
Next Steps
If the J. M. Smucker story feels finely balanced between promise and concern, move quickly instead. Test that tension against the data for yourself, then weigh the 3 key rewards and 3 important warning signs.
Looking for more J. M. Smucker investment ideas?
If J. M. Smucker has your attention, keep going. The next smart move is widening your watchlist so you can compare risks, returns, and balance sheet strength in one place.
- Target potential mispricings by scanning a curated pool of quality companies that still trade at appealing valuations through the 27 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses with robust payouts and strong coverage ratios using the 8 dividend fortresses.
- Lean toward resilience by filtering for companies with healthier leverage and liquidity profiles through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com