
Credit Saison (TSE:8253) Files Bond Shelf As Fair Value Questions Return
Credit Saison (TSE:8253) has filed a shelf registration to issue up to ¥300 billion in bonds, adding new funding capacity and raising questions about how management plans to allocate that capital.
The bond shelf lands at a time when Credit Saison’s share price has eased back, with the 30 day share price return down 7.44% and the 90 day share price return down 7.99%, even though the year to date share price return is slightly positive and the 1 year total shareholder return is 11.92%.
Scan how Credit Saison compares with other lenders and financiers under pressure or quietly rebuilding by using our curated list of list of solid balance sheet and fundamentals (23 results)
Bulls point to Credit Saison’s newly issued bonds and recent earnings trends as support for what they view as a discounted share price. Bears focus on funding risk and a declining three month return. Which side does the current valuation appear to favor?
Preferred P/E of 8.9x for Credit Saison: Is it justified?
On the numbers alone, Credit Saison looks inexpensive, with the shares at ¥4,216 and the stock trading on a P/E of 8.9x that points to a cheaper tag than many peers despite the multi year total return track record.
The P/E compares the current share price to earnings per share and gives you a shorthand for how much investors are paying for each unit of profit. For a lender and finance platform like Credit Saison, which reports earnings of ¥68,405 million on revenue of ¥551,917 million, this metric is a quick way to stack the valuation against other consumer finance players that also rely heavily on interest income and credit risk management.
Credit Saison screens on what looks like a discounted multiple, with the P/E of 8.9x described as good value versus both peers at 12.1x and the wider Asian Consumer Finance industry at 12x. When framed against an estimated fair P/E of 15.3x, the gap appears even starker and highlights a level the market could move towards if sentiment and fundamentals line up over time.
Explore the SWS fair ratio for Credit Saison.
Result: Price-to-earnings of 8.9x (UNDERVALUED)
Still, Credit Saison’s recent three month share price decline and the planned ¥300b bond capacity both leave plenty of room for funding and sentiment risk to reprice the story.
Find out about the key risks to this Credit Saison narrative.
Another view on Credit Saison’s value
The earlier P/E workup presents Credit Saison as inexpensive. The SWS DCF model goes even further, with an estimated future cash flow value of ¥9,927.94 per share versus a market price of ¥4,216, which suggests a large undervaluation. That gap raises a sharper question: Is this a mispricing or a warning on risk?
Look into how the SWS DCF model arrives at its fair value.
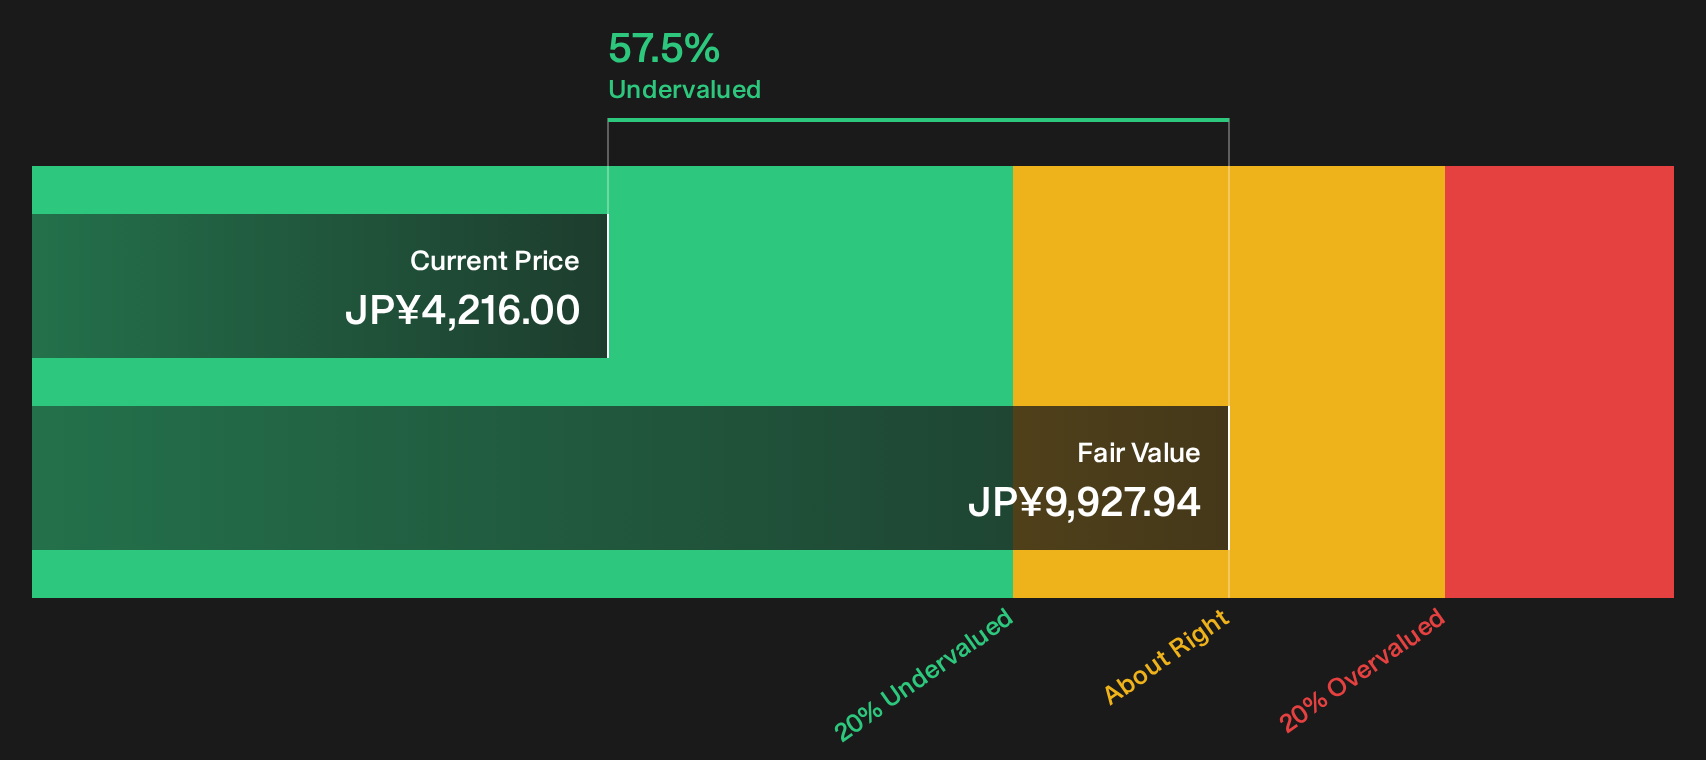
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Credit Saison for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Credit Saison’s valuation and funding plan can feel messy, so move quickly, test the numbers yourself, and weigh both sides of the story using our breakdown of 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond Credit Saison?
Do not stop with one opportunity. Broaden your watchlist using focused screens that surface stocks by quality, value, and resilience so you are not reacting late to the next move.
- Hunt for potential bargains that pair solid fundamentals with lower valuations by scanning our list of 13 high quality undervalued stocks.
- Lock in income ideas by zeroing in on companies built around robust payouts and balance sheets through our hand picked 28 dividend fortresses.
- Protect your capital first and let growth follow by filtering for resilient businesses using the targeted 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com